Advanced Porous Materials Market
Advanced Porous Materials Market Forecasts To 2034 – Global Analysis By Material Type (Porous Ceramics, Porous Metals, Porous Polymers, Porous Carbon Materials, Porous Silica Materials, Porous Glass, Metal–Organic Frameworks, Porous Composites and Porous Hybrid Materials), Pore Structure, Functional Property, Aerospace Application, Aircraft and Spacecraft Type, Component, Form, Manufacturing Technology, Advanced Technology, End User and By Geography
According to Stratistics MRC, the Global Advanced Porous Materials Market is accounted for $47.9 billion in 2026 and is expected to reach $96.9 billion by 2034 growing at a CAGR of 9.2% during the forecast period. Architected materials are intentionally designed structures that use controlled geometry and composition to deliver specialized properties not typically achievable with conventional materials. Their architecture can be engineered at different scales to optimize mechanical strength, lightweight performance, thermal behavior, electrical conductivity, optical response, and acoustic characteristics. Key forms include metamaterials, lattice-based structures, porous materials, and architected composites. Additive manufacturing plays an important role in producing their intricate and highly customized designs. These materials are gaining adoption across aerospace, automotive, healthcare, electronics, energy, and defense sectors, particularly where weight reduction, structural efficiency, multifunctional performance, and application-specific material characteristics are essential for advanced technologies.
Market Dynamics:
Driver:
Increasing Demand for Lightweight and High-Strength Materials
Rising requirements for materials that combine low weight with superior strength are significantly supporting the growth of architected materials. Aerospace, automotive, defense, and other performance-driven industries are seeking structural solutions that minimize mass without reducing reliability or durability. Architected designs, including lattice and cellular structures, can provide exceptional strength-to-weight performance by efficiently managing applied loads. Reduced material weight can also improve fuel economy, decrease energy consumption, and support lower emissions. As manufacturers focus on improving resource efficiency and meeting sustainability targets, materials capable of delivering high structural performance with reduced mass are becoming increasingly attractive, creating strong opportunities for architected materials across advanced engineering and manufacturing sectors.
Restraint:
High Manufacturing Costs
Elevated production expenses can limit the widespread adoption of architected materials. Manufacturing intricate structures frequently depends on expensive additive manufacturing equipment, specialized feedstocks, advanced design software, and tightly controlled processing environments. These factors can increase capital requirements as well as operating and inspection costs when compared with traditional production techniques. Limited production volumes can also result in higher unit costs, making large-scale commercialization challenging. Furthermore, customized designs may require substantial engineering, modeling, validation, and testing before they can be manufactured reliably. Such financial barriers can reduce adoption among cost-sensitive manufacturers, making improvements in production efficiency, scalability, and cost competitiveness essential for expanding the architected materials market.
Opportunity:
Development of Advanced Energy and Thermal Management Systems
Rising requirements for improved thermal and energy efficiency are opening new avenues for architected materials. Their internal geometry can be precisely engineered to control heat movement, fluid circulation, insulation, energy absorption, and electromagnetic behavior. Such capabilities make these materials attractive for applications including heat exchangers, thermal protection systems, batteries, fuel cells, and energy-storage technologies. Their ability to provide extensive functional surface area while maintaining low weight can improve system efficiency and material utilization. Increasing development of electric mobility, renewable-energy technologies, advanced batteries, and high-performance thermal systems is strengthening demand for innovative architectures. These trends offer significant opportunities for architected materials within emerging energy technologies.
Threat:
Rapid Technological Changes and Material Substitution
Fast-paced innovation across materials and manufacturing technologies can challenge the long-term competitiveness of architected materials. New developments in nanotechnology, smart materials, advanced composites, metamaterials, and other engineered solutions may deliver comparable or improved performance for targeted applications. Enhancements in conventional material formulations and production processes can similarly narrow the performance advantages of architected structures. If alternative technologies provide lower costs, simpler manufacturing, faster scaling, or better overall efficiency, industrial customers may redirect investments toward those solutions. The constantly evolving technological landscape can therefore increase market uncertainty and place pressure on architected material companies to maintain continuous research, development, and process innovation.
Covid-19 Impact:
The COVID-19 pandemic negatively affected the architected materials market by disrupting global supply chains, manufacturing operations, research activities, and industrial investments. Lockdowns and restrictions caused delays in production, transportation, and procurement of specialized materials and components. Aerospace, automotive, and construction industries experienced reduced demand, leading several manufacturers to postpone advanced material projects. Research institutions and laboratories also faced temporary closures, slowing development and testing activities. However, healthcare applications created opportunities for architected materials in medical devices, implants, protective equipment, and biomedical research. As restrictions eased, manufacturing operations resumed, supply chains gradually stabilized, and investments in advanced manufacturing and additive technologies supported market recovery and renewed growth.
The Porous Ceramics segment is expected to be the largest during the forecast period
The Porous Ceramics segment is expected to account for the largest market share during the forecast period, The Porous Ceramics segment is expected to account for the largest market share during the forecast period, owing to the distinctive combination of low weight, thermal stability, chemical resistance, and precisely controllable pore architectures offered by these materials. Their structures can be customized to deliver specific permeability, mechanical strength, insulation, filtration, and surface characteristics. This versatility supports their use in aerospace, medical technologies, energy systems, filtration equipment, environmental applications, and industrial processes. Their capacity to withstand demanding temperatures and aggressive environments further increases their suitability for specialized applications. Ongoing improvements in ceramic fabrication, additive manufacturing, and pore engineering are expected to expand their functionality and industrial utilization.
The Battery Components segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Battery Components segment is predicted to witness the highest growth rate, supported by rising requirements for lightweight, thermally optimized, and structurally engineered materials for advanced energy-storage applications. Architected structures can be designed with controlled porosity and high surface-area characteristics, enabling improved thermal management, ion movement, mechanical stability, and overall weight efficiency. These capabilities make them increasingly relevant to emerging battery designs used in electric vehicles, renewable-energy storage systems, consumer electronics, and next-generation energy technologies. Expanding investments in advanced batteries, combined with progress in additive manufacturing and material engineering, are expected to create greater opportunities for architected materials and accelerate their integration into future battery components.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by its strong technological base, sophisticated manufacturing capabilities, and high levels of research activity. The region benefits from established aerospace, automotive, medical, electronics, and energy industries that are actively exploring lightweight and high-performance material solutions. A strong presence of additive manufacturing firms, research organizations, and technology innovators is also encouraging advancements in architected material development. Increasing use of 3D printing and other advanced fabrication techniques is supporting the production of complex structures with customized properties. Continued investment in innovative engineering technologies is expected to reinforce North America's leading market position.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, driven by expanding industrial activity, developing manufacturing infrastructure, and rising interest in advanced material solutions. The region's established automotive, aerospace, electronics, medical, and energy sectors are increasingly exploring lightweight and high-performance technologies. Greater use of additive manufacturing and sophisticated production methods is supporting the creation of customized and complex material architectures. China, Japan, South Korea, and India are also increasing their focus on research, innovation, and advanced manufacturing capabilities. Rapid industrial modernization, infrastructure expansion, and technological investment are expected to further strengthen the adoption of architected materials across the region.
Key players in the market
Some of the key players in Advanced Porous Materials Market include Saint-Gobain, Porvair plc, Enersens, Aerogel Core Ltd., Aspen Aerogels, Inc., Morgan Advanced Materials plc, CoorsTek, Inc., CeramTec GmbH, SGL Carbon SE, Kyocera Corporation, BASF SE, Cabot Corporation, Aerogel Technologies, LLC, 3A Composites GmbH, Arceon B.V., Svenska Aerogel AB, Nippon Sheet Glass Co., Ltd. and Materion Corporation.
Key Developments:
In June 2026, spen Aerogels announced that it had been named a 2025 General Motors Supplier of the Year. The official announcement specifically describes the continuing Aspen–GM partnership supporting GM’s EV thermal-management strategy and notes Aspen’s role in the development and production of thermal-barrier solutions.
In March 2026, Saint-Gobain announced its continued partnership with ChangeNOW, marking the sixth consecutive year of collaboration. The partnership brings together innovators, investors, businesses, and other stakeholders to accelerate environmental solutions.
Material Types Covered:
• Porous Ceramics
• Porous Metals
• Porous Polymers
• Porous Carbon Materials
• Porous Silica Materials
• Porous Glass
• Metal–Organic Frameworks
• Porous Composites
• Porous Hybrid Materials
Pore Structures Covered:
• Microporous
• Mesoporous
• Macroporous
• Hierarchical Porous
• Interconnected Porous
Functional Properties Covered:
• Thermal Insulation
• Filtration and Separation
• Adsorption
• Catalysis
• Acoustic Insulation
• Lightweight Structural Support
• Energy Storage and Conversion
• Sensing
• Electromagnetic Shielding
Aerospace Applications Covered:
• Thermal Protection Systems
• Thermal Management
• Acoustic Insulation
• Lightweight Structural Components
• Air Filtration and Purification
• Gas Separation and Storage
• Catalytic Systems
• Energy Storage and Conversion
• Environmental Control Systems
• Sensors and Detection Systems
• Electromagnetic Shielding
• Spacecraft Life-Support Systems
Aircraft and Spacecraft Types Covered:
• Commercial Aircraft
• Military Aircraft
• Business Jets
• Unmanned Aerial Vehicles
• Launch Vehicles
• Satellites
• Spacecraft
• Space Stations
Components Covered:
• Thermal Protection Components
• Heat Exchangers
• Filters
• Catalytic Converters
• Insulation Components
• Structural Components
• Battery Components
• Fuel-System Components
• Environmental Control Components
• Sensor Components
Forms Covered:
• Monoliths
• Membranes
• Foams
• Coatings
• Powders
• Pellets
• Films
• Fibers
• 3D-Printed Structures
Manufacturing Technologies Covered:
• Sol–Gel Processing
• Template-Assisted Synthesis
• Freeze Drying
• Foaming
• Powder Metallurgy
• Additive Manufacturing
• Electrospinning
• Chemical Vapor Deposition
• Hydrothermal and Solvothermal Synthesis
• Etching and Dealloying
Advanced Technologies Covered:
• Nanoporous Material Engineering
• Hierarchical Pore Engineering
• Surface Functionalization
• Porous Material Coating Technology
• 3D-Printed Porous Structures
• Digital Materials Design
• Computational Modeling and Simulation
• In-Situ Monitoring and Characterization
End Users Covered:
• Aircraft Manufacturers
• Spacecraft Manufacturers
• Aerospace Component Manufacturers
• Defense Organizations
• Space Agencies
• Airlines and Commercial Aviation Operators
• Satellite Operators
• Launch Service Providers
• Research and Development Organizations
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Advanced Porous Materials Market, By Material Type
5.1 Porous Ceramics
5.2 Porous Metals
5.3 Porous Polymers
5.4 Porous Carbon Materials
5.5 Porous Silica Materials
5.6 Porous Glass
5.7 Metal–Organic Frameworks
5.8 Porous Composites
5.9 Porous Hybrid Materials
6 Global Advanced Porous Materials Market, By Pore Structure
6.1 Microporous
6.2 Mesoporous
6.3 Macroporous
6.4 Hierarchical Porous
6.5 Interconnected Porous
7 Global Advanced Porous Materials Market, By Functional Property
7.1 Thermal Insulation
7.2 Filtration and Separation
7.3 Adsorption
7.4 Catalysis
7.5 Acoustic Insulation
7.6 Lightweight Structural Support
7.7 Energy Storage and Conversion
7.8 Sensing
7.9 Electromagnetic Shielding
8 Global Advanced Porous Materials Market, By Aerospace Application
8.1 Thermal Protection Systems
8.2 Thermal Management
8.3 Acoustic Insulation
8.4 Lightweight Structural Components
8.5 Air Filtration and Purification
8.6 Gas Separation and Storage
8.7 Catalytic Systems
8.8 Energy Storage and Conversion
8.9 Environmental Control Systems
8.10 Sensors and Detection Systems
8.11 Electromagnetic Shielding
8.12 Spacecraft Life-Support Systems
9 Global Advanced Porous Materials Market, By Aircraft and Spacecraft Type
9.1 Commercial Aircraft
9.2 Military Aircraft
9.3 Business Jets
9.4 Unmanned Aerial Vehicles
9.5 Launch Vehicles
9.6 Satellites
9.7 Spacecraft
9.8 Space Stations
10 Global Advanced Porous Materials Market, By Component
10.1 Thermal Protection Components
10.2 Heat Exchangers
10.3 Filters
10.4 Catalytic Converters
10.5 Insulation Components
10.6 Structural Components
10.7 Battery Components
10.8 Fuel-System Components
10.9 Environmental Control Components
10.10 Sensor Components
11 Global Advanced Porous Materials Market, By Form
11.1 Monoliths
11.2 Membranes
11.3 Foams
11.4 Coatings
11.5 Powders
11.6 Pellets
11.7 Films
11.8 Fibers
11.9 3D-Printed Structures
12 Global Advanced Porous Materials Market, By Manufacturing Technology
12.1 Sol–Gel Processing
12.2 Template-Assisted Synthesis
12.3 Freeze Drying
12.4 Foaming
12.5 Powder Metallurgy
12.6 Additive Manufacturing
12.7 Electrospinning
12.8 Chemical Vapor Deposition
12.9 Hydrothermal and Solvothermal Synthesis
12.10 Etching and Dealloying
13 Global Advanced Porous Materials Market, By Advanced Technology
13.1 Nanoporous Material Engineering
13.2 Hierarchical Pore Engineering
13.3 Surface Functionalization
13.4 Porous Material Coating Technology
13.5 3D-Printed Porous Structures
13.6 Digital Materials Design
13.7 Computational Modeling and Simulation
13.8 In-Situ Monitoring and Characterization
14 Global Advanced Porous Materials Market, By End User
14.1 Aircraft Manufacturers
14.2 Spacecraft Manufacturers
14.3 Aerospace Component Manufacturers
14.4 Defense Organizations
14.5 Space Agencies
14.6 Airlines and Commercial Aviation Operators
14.7 Satellite Operators
14.8 Launch Service Providers
14.9 Research and Development Organizations
15 Global Advanced Porous Materials Market, By Geography
15.1 North America
15.1.1 United States
15.1.2 Canada
15.1.3 Mexico
15.2.1 Europe
15.2.1 United Kingdom
15.2.2 Germany
15.2.3 France
15.2.4 Italy
15.2.5 Spain
15.2.6 Netherlands
15.2.7 Belgium
15.2.8 Sweden
15.2.9 Switzerland
15.2.10 Poland
15.2.11 Rest of Europe
15.3 Asia Pacific
15.3.1 China
15.3.2 Japan
15.3.3 India
15.3.4 South Korea
15.3.5 Australia
15.3.6 Indonesia
15.3.7 Thailand
15.3.8 Malaysia
15.3.9 Singapore
15.3.10 Vietnam
15.3.11 Rest of Asia Pacific
15.4 South America
15.4.1 Brazil
15.4.2 Argentina
15.4.3 Colombia
15.4.4 Chile
15.4.5 Peru
15.4.6 Rest of South America
15.5 Rest of the World (RoW)
15.5.1 Middle East
15.5.1.1 Saudi Arabia
15.5.1.2 United Arab Emirates
15.5.1.3 Qatar
15.5.1.4 Israel
15.5.1.5 Rest of Middle East
15.5.2 Africa
15.5.2.1 South Africa
15.5.2.2 Egypt
15.5.2.3 Morocco
15.5.2.4 Rest of Africa
16 Strategic Market Intelligence
16.1 Industry Value Network and Supply Chain Assessment
16.2 White-Space and Opportunity Mapping
16.3 Product Evolution and Market Life Cycle Analysis
16.4 Channel, Distributor, and Go-to-Market Assessment
17 Industry Developments and Strategic Initiatives
17.1 Mergers and Acquisitions
17.2 Partnerships, Alliances, and Joint Ventures
17.3 New Product Launches and Certifications
17.4 Capacity Expansion and Investments
17.5 Other Strategic Initiatives
18 Company Profiles
18.1 Saint-Gobain
18.2 Porvair plc
18.3 Enersens
18.4 Aerogel Core Ltd.
18.5 Aspen Aerogels, Inc.
18.6 Morgan Advanced Materials plc
18.7 CoorsTek, Inc.
18.8 CeramTec GmbH
18.9 SGL Carbon SE
18.10 Kyocera Corporation
18.11 BASF SE
18.12 Cabot Corporation
18.13 Aerogel Technologies, LLC
18.14 3A Composites GmbH
18.15 Arceon B.V.
18.16 Svenska Aerogel AB
18.17 Nippon Sheet Glass Co., Ltd.
18.18 Materion Corporation
List of Tables
Table 1 Global Advanced Porous Materials Market Outlook, By Region (2023-2034) ($MN)
Table 2 Global Advanced Porous Materials Market Outlook, By Material Type (2023-2034) ($MN)
Table 3 Global Advanced Porous Materials Market Outlook, By Porous Ceramics (2023-2034) ($MN)
Table 4 Global Advanced Porous Materials Market Outlook, By Porous Metals (2023-2034) ($MN)
Table 5 Global Advanced Porous Materials Market Outlook, By Porous Polymers (2023-2034) ($MN)
Table 6 Global Advanced Porous Materials Market Outlook, By Porous Carbon Materials (2023-2034) ($MN)
Table 7 Global Advanced Porous Materials Market Outlook, By Porous Silica Materials (2023-2034) ($MN)
Table 8 Global Advanced Porous Materials Market Outlook, By Porous Glass (2023-2034) ($MN)
Table 9 Global Advanced Porous Materials Market Outlook, By Metal–Organic Frameworks (MOFs) (2023-2034) ($MN)
Table 10 Global Advanced Porous Materials Market Outlook, By Porous Composites (2023-2034) ($MN)
Table 11 Global Advanced Porous Materials Market Outlook, By Porous Hybrid Materials (2023-2034) ($MN)
Table 12 Global Advanced Porous Materials Market Outlook, By Pore Structure (2023-2034) ($MN)
Table 13 Global Advanced Porous Materials Market Outlook, By Microporous (2023-2034) ($MN)
Table 14 Global Advanced Porous Materials Market Outlook, By Mesoporous (2023-2034) ($MN)
Table 15 Global Advanced Porous Materials Market Outlook, By Macroporous (2023-2034) ($MN)
Table 16 Global Advanced Porous Materials Market Outlook, By Hierarchical Porous (2023-2034) ($MN)
Table 17 Global Advanced Porous Materials Market Outlook, By Interconnected Porous (2023-2034) ($MN)
Table 18 Global Advanced Porous Materials Market Outlook, By Functional Property (2023-2034) ($MN)
Table 19 Global Advanced Porous Materials Market Outlook, By Thermal Insulation (2023-2034) ($MN)
Table 20 Global Advanced Porous Materials Market Outlook, By Filtration and Separation (2023-2034) ($MN)
Table 21 Global Advanced Porous Materials Market Outlook, By Adsorption (2023-2034) ($MN)
Table 22 Global Advanced Porous Materials Market Outlook, By Catalysis (2023-2034) ($MN)
Table 23 Global Advanced Porous Materials Market Outlook, By Acoustic Insulation (2023-2034) ($MN)
Table 24 Global Advanced Porous Materials Market Outlook, By Lightweight Structural Support (2023-2034) ($MN)
Table 25 Global Advanced Porous Materials Market Outlook, By Energy Storage and Conversion (2023-2034) ($MN)
Table 26 Global Advanced Porous Materials Market Outlook, By Sensing (2023-2034) ($MN)
Table 27 Global Advanced Porous Materials Market Outlook, By Electromagnetic Shielding (2023-2034) ($MN)
Table 28 Global Advanced Porous Materials Market Outlook, By Aerospace Application (2023-2034) ($MN)
Table 29 Global Advanced Porous Materials Market Outlook, By Thermal Protection Systems (2023-2034) ($MN)
Table 30 Global Advanced Porous Materials Market Outlook, By Thermal Management (2023-2034) ($MN)
Table 31 Global Advanced Porous Materials Market Outlook, By Acoustic Insulation (2023-2034) ($MN)
Table 32 Global Advanced Porous Materials Market Outlook, By Lightweight Structural Components (2023-2034) ($MN)
Table 33 Global Advanced Porous Materials Market Outlook, By Air Filtration and Purification (2023-2034) ($MN)
Table 34 Global Advanced Porous Materials Market Outlook, By Gas Separation and Storage (2023-2034) ($MN)
Table 35 Global Advanced Porous Materials Market Outlook, By Catalytic Systems (2023-2034) ($MN)
Table 36 Global Advanced Porous Materials Market Outlook, By Energy Storage and Conversion (2023-2034) ($MN)
Table 37 Global Advanced Porous Materials Market Outlook, By Environmental Control Systems (2023-2034) ($MN)
Table 38 Global Advanced Porous Materials Market Outlook, By Sensors and Detection Systems (2023-2034) ($MN)
Table 39 Global Advanced Porous Materials Market Outlook, By Electromagnetic Shielding (2023-2034) ($MN)
Table 40 Global Advanced Porous Materials Market Outlook, By Spacecraft Life-Support Systems (2023-2034) ($MN)
Table 41 Global Advanced Porous Materials Market Outlook, By Aircraft and Spacecraft Type (2023-2034) ($MN)
Table 42 Global Advanced Porous Materials Market Outlook, By Commercial Aircraft (2023-2034) ($MN)
Table 43 Global Advanced Porous Materials Market Outlook, By Military Aircraft (2023-2034) ($MN)
Table 44 Global Advanced Porous Materials Market Outlook, By Business Jets (2023-2034) ($MN)
Table 45 Global Advanced Porous Materials Market Outlook, By Unmanned Aerial Vehicles (2023-2034) ($MN)
Table 46 Global Advanced Porous Materials Market Outlook, By Launch Vehicles (2023-2034) ($MN)
Table 47 Global Advanced Porous Materials Market Outlook, By Satellites (2023-2034) ($MN)
Table 48 Global Advanced Porous Materials Market Outlook, By Spacecraft (2023-2034) ($MN)
Table 49 Global Advanced Porous Materials Market Outlook, By Space Stations (2023-2034) ($MN)
Table 50 Global Advanced Porous Materials Market Outlook, By Component (2023-2034) ($MN)
Table 51 Global Advanced Porous Materials Market Outlook, By Thermal Protection Components (2023-2034) ($MN)
Table 52 Global Advanced Porous Materials Market Outlook, By Heat Exchangers (2023-2034) ($MN)
Table 53 Global Advanced Porous Materials Market Outlook, By Filters (2023-2034) ($MN)
Table 54 Global Advanced Porous Materials Market Outlook, By Catalytic Converters (2023-2034) ($MN)
Table 55 Global Advanced Porous Materials Market Outlook, By Insulation Components (2023-2034) ($MN)
Table 56 Global Advanced Porous Materials Market Outlook, By Structural Components (2023-2034) ($MN)
Table 57 Global Advanced Porous Materials Market Outlook, By Battery Components (2023-2034) ($MN)
Table 58 Global Advanced Porous Materials Market Outlook, By Fuel-System Components (2023-2034) ($MN)
Table 59 Global Advanced Porous Materials Market Outlook, By Environmental Control Components (2023-2034) ($MN)
Table 60 Global Advanced Porous Materials Market Outlook, By Sensor Components (2023-2034) ($MN)
Table 61 Global Advanced Porous Materials Market Outlook, By Form (2023-2034) ($MN)
Table 62 Global Advanced Porous Materials Market Outlook, By Monoliths (2023-2034) ($MN)
Table 63 Global Advanced Porous Materials Market Outlook, By Membranes (2023-2034) ($MN)
Table 64 Global Advanced Porous Materials Market Outlook, By Foams (2023-2034) ($MN)
Table 65 Global Advanced Porous Materials Market Outlook, By Coatings (2023-2034) ($MN)
Table 66 Global Advanced Porous Materials Market Outlook, By Powders (2023-2034) ($MN)
Table 67 Global Advanced Porous Materials Market Outlook, By Pellets (2023-2034) ($MN)
Table 68 Global Advanced Porous Materials Market Outlook, By Films (2023-2034) ($MN)
Table 69 Global Advanced Porous Materials Market Outlook, By Fibers (2023-2034) ($MN)
Table 70 Global Advanced Porous Materials Market Outlook, By 3D-Printed Structures (2023-2034) ($MN)
Table 71 Global Advanced Porous Materials Market Outlook, By Manufacturing Technology (2023-2034) ($MN)
Table 72 Global Advanced Porous Materials Market Outlook, By Sol–Gel Processing (2023-2034) ($MN)
Table 73 Global Advanced Porous Materials Market Outlook, By Template-Assisted Synthesis (2023-2034) ($MN)
Table 74 Global Advanced Porous Materials Market Outlook, By Freeze Drying (2023-2034) ($MN)
Table 75 Global Advanced Porous Materials Market Outlook, By Foaming (2023-2034) ($MN)
Table 76 Global Advanced Porous Materials Market Outlook, By Powder Metallurgy (2023-2034) ($MN)
Table 77 Global Advanced Porous Materials Market Outlook, By Additive Manufacturing (2023-2034) ($MN)
Table 78 Global Advanced Porous Materials Market Outlook, By Electrospinning (2023-2034) ($MN)
Table 79 Global Advanced Porous Materials Market Outlook, By Chemical Vapor Deposition (2023-2034) ($MN)
Table 80 Global Advanced Porous Materials Market Outlook, By Hydrothermal and Solvothermal Synthesis (2023-2034) ($MN)
Table 81 Global Advanced Porous Materials Market Outlook, By Etching and Dealloying (2023-2034) ($MN)
Table 82 Global Advanced Porous Materials Market Outlook, By Advanced Technology (2023-2034) ($MN)
Table 83 Global Advanced Porous Materials Market Outlook, By Nanoporous Material Engineering (2023-2034) ($MN)
Table 84 Global Advanced Porous Materials Market Outlook, By Hierarchical Pore Engineering (2023-2034) ($MN)
Table 85 Global Advanced Porous Materials Market Outlook, By Surface Functionalization (2023-2034) ($MN)
Table 86 Global Advanced Porous Materials Market Outlook, By Porous Material Coating Technology (2023-2034) ($MN)
Table 87 Global Advanced Porous Materials Market Outlook, By 3D-Printed Porous Structures (2023-2034) ($MN)
Table 88 Global Advanced Porous Materials Market Outlook, By Digital Materials Design (2023-2034) ($MN)
Table 89 Global Advanced Porous Materials Market Outlook, By Computational Modeling and Simulation (2023-2034) ($MN)
Table 90 Global Advanced Porous Materials Market Outlook, By In-Situ Monitoring and Characterization (2023-2034) ($MN)
Table 91 Global Advanced Porous Materials Market Outlook, By End User (2023-2034) ($MN)
Table 92 Global Advanced Porous Materials Market Outlook, By Aircraft Manufacturers (2023-2034) ($MN)
Table 93 Global Advanced Porous Materials Market Outlook, By Spacecraft Manufacturers (2023-2034) ($MN)
Table 94 Global Advanced Porous Materials Market Outlook, By Aerospace Component Manufacturers (2023-2034) ($MN)
Table 95 Global Advanced Porous Materials Market Outlook, By Defense Organizations (2023-2034) ($MN)
Table 96 Global Advanced Porous Materials Market Outlook, By Space Agencies (2023-2034) ($MN)
Table 97 Global Advanced Porous Materials Market Outlook, By Airlines and Commercial Aviation Operators (2023-2034) ($MN)
Table 98 Global Advanced Porous Materials Market Outlook, By Satellite Operators (2023-2034) ($MN)
Table 99 Global Advanced Porous Materials Market Outlook, By Launch Service Providers (2023-2034) ($MN)
Table 100 Global Advanced Porous Materials Market Outlook, By Research and Development Organizations (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
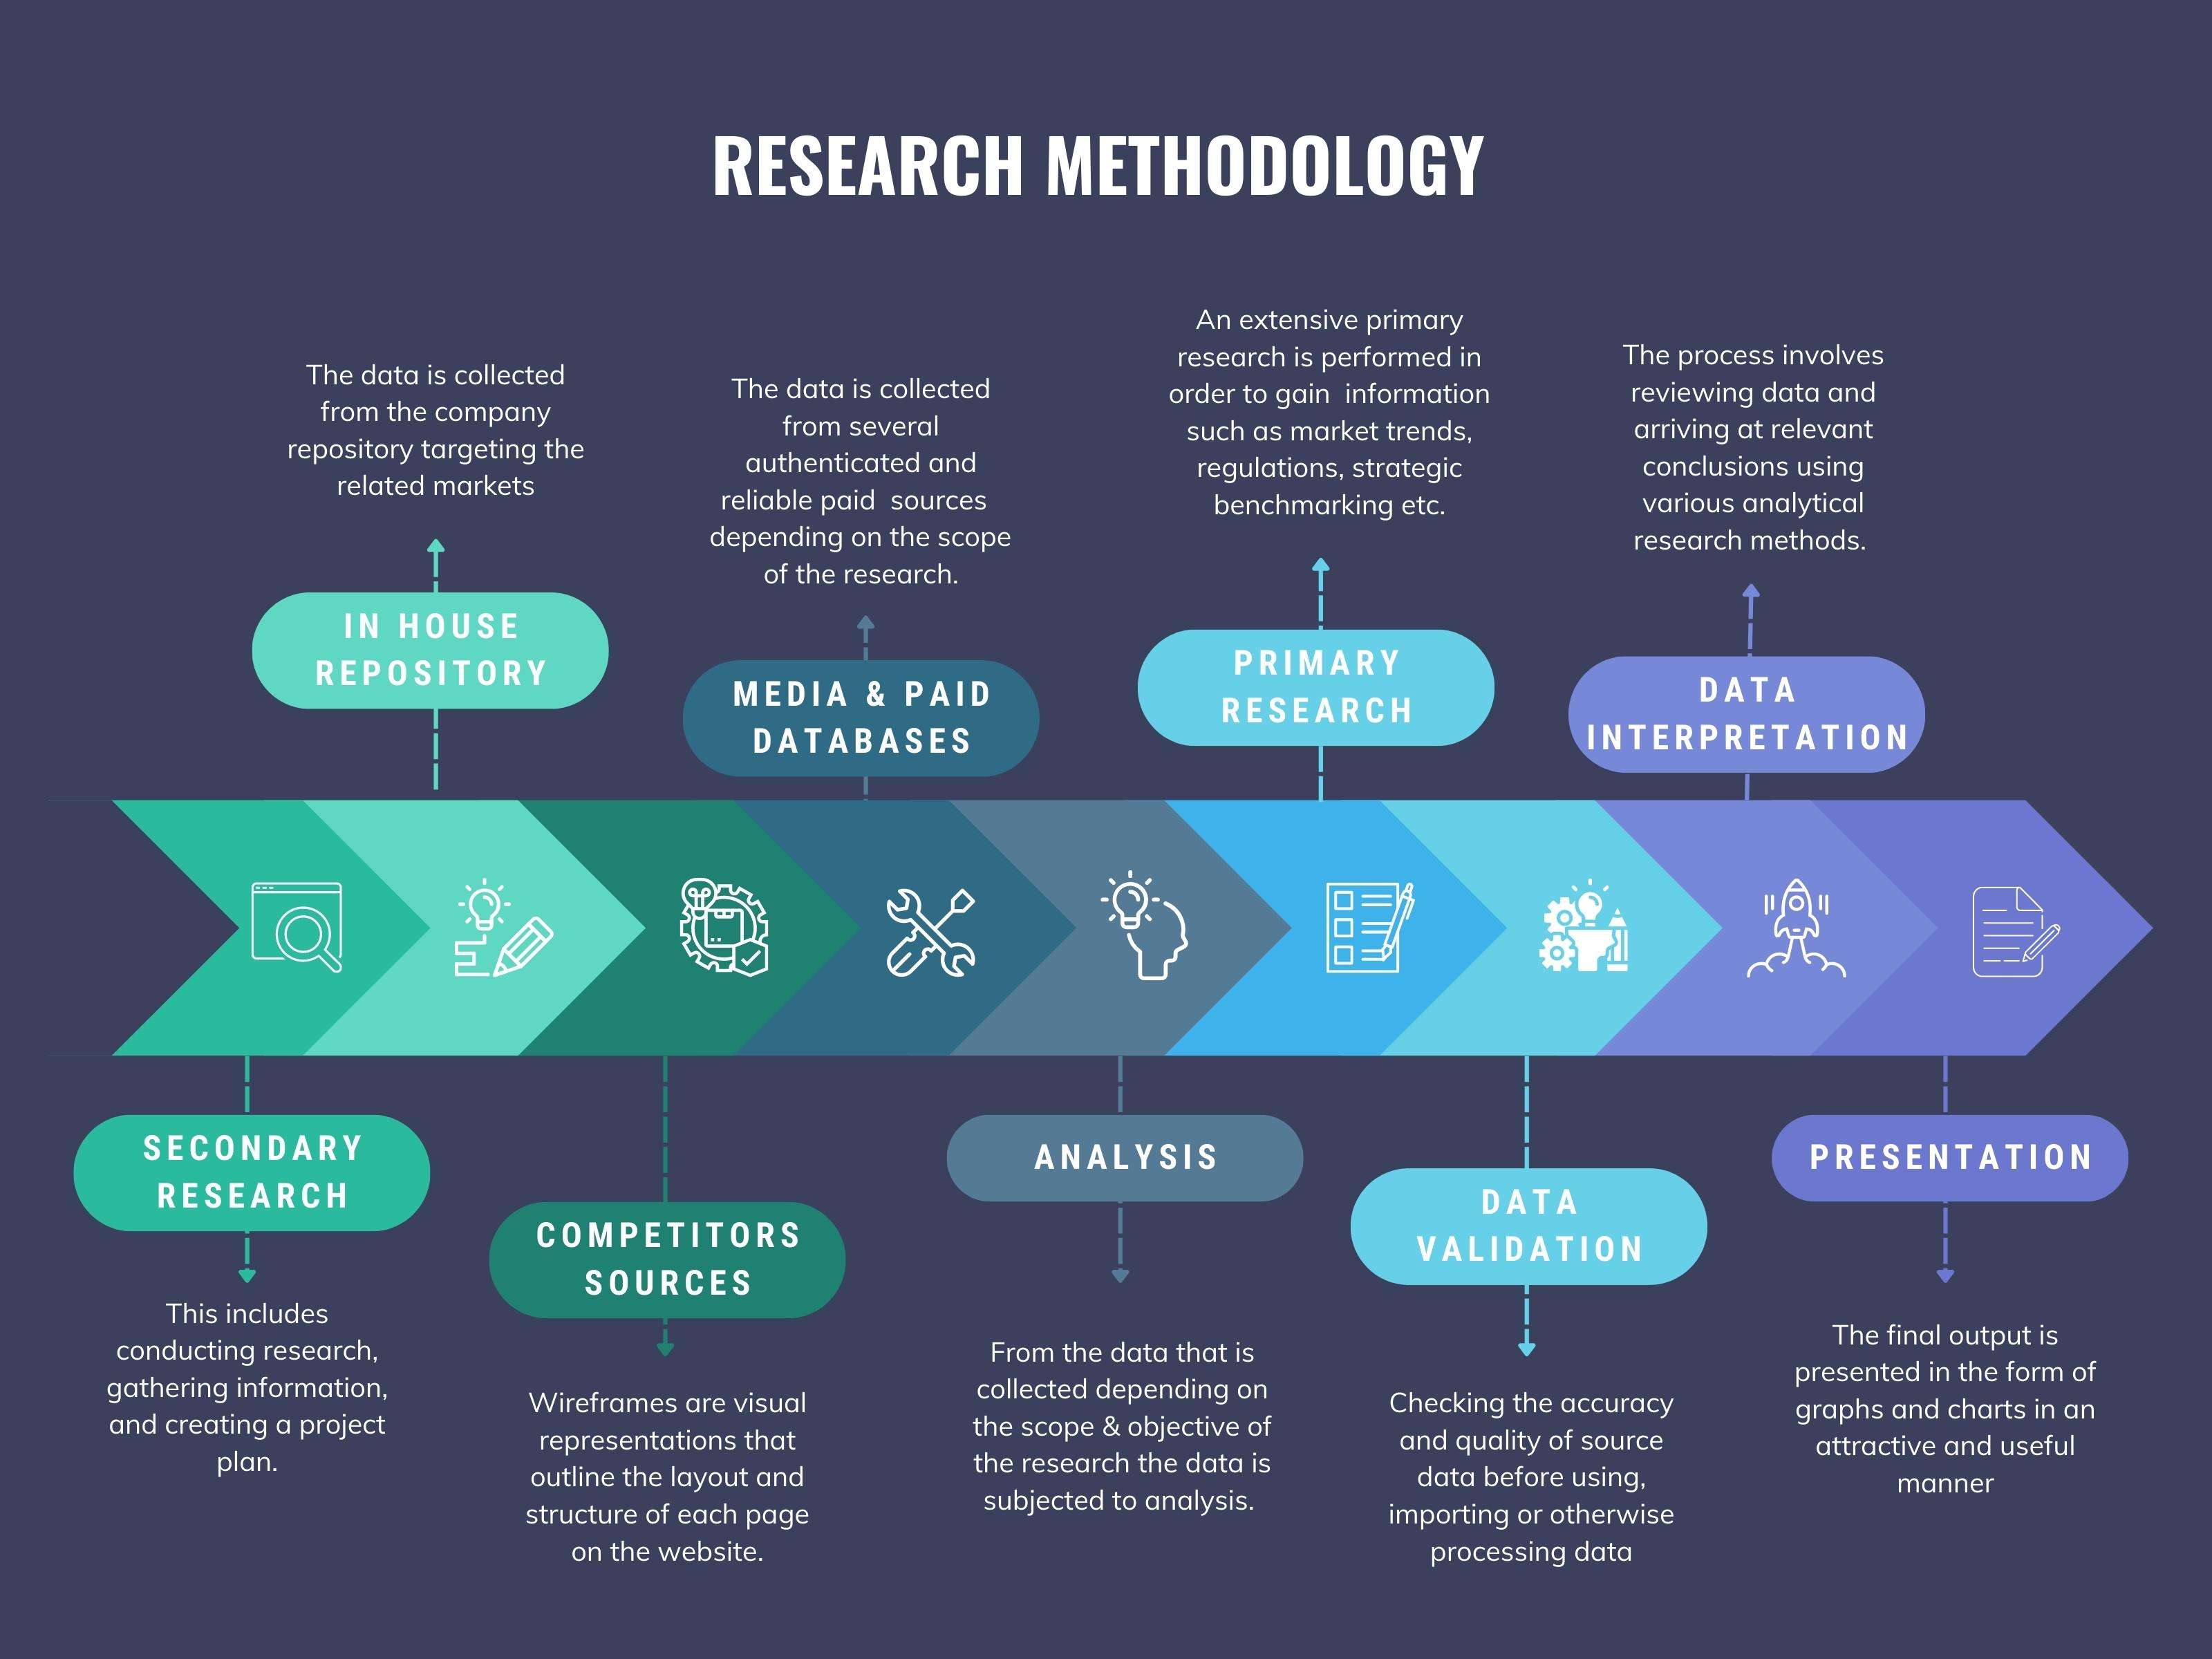
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.