Automotive Copper Free Brake Pad Market
Automotive Copper-Free Brake Pad Market Forecasts to 2034 – Global Analysis By Friction Formulation (Ceramic and Copper-Free NAO, Low-Metallic Copper-Free Formulations, Semi-Metallic Copper-Free Formulations, and Low-Dust and Low-Emission Materials), Product Type, Vehicle Type, and By Geography
Market Dynamics:
Driver:
Copper restrictions reshape friction-material purchasing requirements
Requirements intended to reduce copper release from vehicle brakes have encouraged manufacturers and distributors to move toward qualifying lower-copper formulations. Once a compliant product range is established, suppliers can simplify purchasing by offering suitable materials across several markets rather than maintaining numerous regional recipes. Customers still expect familiar braking response, noise control, and service life, making the transition an engineering task as well as a compliance exercise. Replacement channels need clear markings and reliable product records to distinguish current offerings from legacy inventory. These practical purchasing requirements support continuing demand for qualified copper-free pads across vehicle classes.
Restraint:
Replacing copper requires a complete formulation review
Removing a familiar ingredient can change heat transfer, friction stability, surface-layer formation, and wear behavior. The development task therefore extends beyond selecting a direct substitute at similar cost. Manufacturers must validate the resulting compound with the intended disc and assess the effects of production variation, moisture, and temperature. An acceptable passenger-car recipe may require substantial changes for a commercial vehicle with higher braking energy. The expense of this work can constrain smaller producers and complicate broad catalogue conversion. Maintaining consistent performance while controlling ingredient cost remains a central challenge for suppliers pursuing large replacement volumes.
Opportunity:
Unified compliant ranges can simplify aftermarket distribution
Distributors and repair networks benefit when a clearly identified pad range meets relevant copper requirements without sacrificing application coverage. Suppliers can build that proposition around vehicle-specific compounds, dependable certification records, and installation kits that reduce service errors. Electric and hybrid applications offer additional opportunities to refine corrosion tolerance and first-stop behavior under intermittent friction-brake use. Commercial fleets may also value a consistent material policy across operating regions. The opportunity is strongest when environmental attributes are connected to reliable procurement and service performance, giving customers a practical reason to standardize on a qualified product family.
Threat:
Poorly differentiated claims can obscure braking suitability
A copper-free designation describes one aspect of composition and does not establish that a pad is appropriate for every rotor, vehicle weight, or duty cycle. Marketing that overlooks these differences can lead customers to select an unsuitable product and blame the broader category when performance disappoints. Low-priced competitors may also underinvest in validation while relying heavily on environmental labels. Changes in raw-material supply can threaten formulation consistency after approval. Suppliers need strong quality controls and clear application boundaries to prevent cost pressure from undermining the braking characteristics that made the original copper-free formulation acceptable.
Covid-19 Impact:
Pandemic conditions disrupted the normal turnover of brake-pad inventory as vehicle mileage and workshop visits fell. This could slow the replacement of older stock even while manufacturers continued working on material transitions. Factory interruptions and delayed testing also complicated qualification schedules for new compounds. Demand recovered unevenly across private cars, commercial fleets, and regional service networks, requiring careful inventory planning. For copper-free products, accurate documentation remained important throughout the disruption so that distributors could identify the applicable formulation and avoid treating similar-looking legacy and newly qualified pads as interchangeable parts.
The Disc Brake Pads segment is expected to be the largest during the forecast period
Disc Brake Pads are expected to hold the largest product share because they address a wide range of modern passenger and light-commercial vehicles and generate recurring replacement demand. Their visibility in routine service makes them a natural focus for copper-free product conversion and distributor stocking. A broad disc-pad catalogue can support both vehicle manufacturers and independent workshops, spreading formulation-development costs across many fitments. The category also includes several material families, allowing suppliers to adapt performance to different duty cycles. This breadth gives disc pads a substantial commercial base even as individual vehicle architectures and braking-control strategies evolve.
The Low-Dust and Low-Emission Materials segment is expected to have the highest CAGR during the forecast period
Low-Dust and Low-Emission Materials are anticipated to grow fastest as customers look beyond copper content to the overall wear behavior of the friction pair. Reducing visible wheel dust and limiting material loss require coordination among the pad recipe, rotor surface, and operating conditions. This encourages more specialized product development and careful test methods. Premium vehicles and fleets seeking predictable maintenance can provide useful early markets. Growth will depend on demonstrating that the material retains appropriate braking performance while delivering the intended wear benefit, since a broad low-emission claim cannot substitute for evidence from the relevant vehicle application.
Region with largest share:
North America is expected to account for the largest regional share because copper-related brake requirements and established replacement distribution have supported broad availability of qualifying formulations. The region's vehicle population includes substantial passenger-car, pickup, and commercial-van demand, each requiring appropriately tuned compounds. Aftermarket brands can use familiar product lines to extend compliant coverage across both domestic and imported vehicles. Clear application data and traceable classification are particularly valuable when legacy stock remains in distribution. These factors support a mature purchasing environment in which environmental composition and practical braking performance are considered together.
Region with highest CAGR:
Asia Pacific is projected to achieve the highest CAGR as regional suppliers expand qualified copper-free offerings for domestic vehicles and international customers. Export programs can encourage common formulation standards, while growing premium and electrified-vehicle production raises expectations for noise, dust, and durability. Local manufacturing scale offers a route to competitive pricing once compounds and production controls are validated. Adoption will vary across markets with different purchasing priorities, so suppliers need flexible catalogues rather than a single regional strategy. Technical support for workshops and reliable product identification can help convert increasing availability into sustained replacement demand.
Key players in the market
Some of the key players in the Automotive Copper-Free Brake Pad Market include Akebono Brake Industry Co., Ltd., Brembo N.V., Tenneco Inc., Robert Bosch GmbH, ZF Friedrichshafen AG, Nisshinbo Holdings Inc., ADVICS Co., Ltd., Aisin Corporation, Astemo, Ltd., Frasle Mobility S.A., TMD Friction Holdings GmbH, Sangsin Brake Co., Ltd., ASK Automotive Limited, Miba AG, and EBC Brakes.
Key Developments:
In May 2025, TMD Friction launched Virtual Brake Sets in the parent braking aftermarket, connecting pads, discs, and relevant indicators in a single catalogue reference. The development supports more accurate replacement selection, an important distribution consideration when workshops choose among friction formulations with different composition and application requirements.
In February 2025, EBC Brakes published a product update describing its Redstuff copper-free, ceramic-granule-enhanced organic pads. The communication detailed the existing compound's low-dust positioning and bedding coating; it was a technical product update, not an announcement that the formulation had just entered production.
In January 2025, Washington's statutory limit of 0.5% copper and its compounds by weight took effect for covered brake-friction-material sales. The requirement reinforced the transition toward qualifying copper-free formulations, with application-specific exemptions and legacy-product provisions requiring separate attention in distribution and service planning.
Friction Formulations Covered:
• Ceramic and Copper-Free NAO
• Low-Metallic Copper-Free Formulations
• Semi-Metallic Copper-Free Formulations
• Low-Dust and Low-Emission Materials
Product Types Covered:
• Disc Brake Pads
• Drum Brake Linings
• Commercial Vehicle Brake Pads
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles
• Heavy Commercial Vehicles
• Electric and Hybrid Vehicles
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
▪ Saudi Arabia
▪ United Arab Emirates
▪ Qatar
▪ Israel
▪ Rest of Middle East
o Africa
▪ South Africa
▪ Egypt
▪ Morocco
▪ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Copper-Free Brake Pad Market, By Friction Formulation
5.1 Ceramic and Copper-Free NAO
5.2 Low-Metallic Copper-Free Formulations
5.3 Semi-Metallic Copper-Free Formulations
5.4 Low-Dust and Low-Emission Materials
6 Global Automotive Copper-Free Brake Pad Market, By Product Type
6.1 Disc Brake Pads
6.2 Drum Brake Linings
6.3 Commercial Vehicle Brake Pads
7 Global Automotive Copper-Free Brake Pad Market, By Vehicle Type
7.1 Passenger Cars
7.2 Light Commercial Vehicles
7.3 Heavy Commercial Vehicles
7.4 Electric and Hybrid Vehicles
8 Global Automotive Copper-Free Brake Pad Market, By Geography
8.1 North America
8.1.1 United States
8.1.2 Canada
8.1.3 Mexico
8.2 Europe
8.2.1 United Kingdom
8.2.2 Germany
8.2.3 France
8.2.4 Italy
8.2.5 Spain
8.2.6 Netherlands
8.2.7 Belgium
8.2.8 Sweden
8.2.9 Switzerland
8.2.10 Poland
8.2.11 Rest of Europe
8.3 Asia Pacific
8.3.1 China
8.3.2 Japan
8.3.3 India
8.3.4 South Korea
8.3.5 Australia
8.3.6 Indonesia
8.3.7 Thailand
8.3.8 Malaysia
8.3.9 Singapore
8.3.10 Vietnam
8.3.11 Rest of Asia Pacific
8.4 South America
8.4.1 Brazil
8.4.2 Argentina
8.4.3 Colombia
8.4.4 Chile
8.4.5 Peru
8.4.6 Rest of South America
8.5 Rest of the World (RoW)
8.5.1 Middle East
8.5.1.1 Saudi Arabia
8.5.1.2 United Arab Emirates
8.5.1.3 Qatar
8.5.1.4 Israel
8.5.1.5 Rest of Middle East
8.5.2 Africa
8.5.2.1 South Africa
8.5.2.2 Egypt
8.5.2.3 Morocco
8.5.2.4 Rest of Africa
9 Strategic Market Intelligence
9.1 Industry Value Network and Supply Chain Assessment
9.2 White-Space and Opportunity Mapping
9.3 Product Evolution and Market Life Cycle Analysis
9.4 Channel, Distributor, and Go-to-Market Assessment
10 Industry Developments and Strategic Initiatives
10.1 Mergers and Acquisitions
10.2 Partnerships, Alliances, and Joint Ventures
10.3 New Product Launches and Certifications
10.4 Capacity Expansion and Investments
10.5 Other Strategic Initiatives
11 Company Profiles
11.1 Akebono Brake Industry Co., Ltd.
11.2 Brembo N.V.
11.3 Tenneco Inc.
11.4 Robert Bosch GmbH
11.5 ZF Friedrichshafen AG
11.6 Nisshinbo Holdings Inc.
11.7 ADVICS Co., Ltd.
11.8 Aisin Corporation
11.9 Astemo, Ltd.
11.10 Frasle Mobility S.A.
11.11 TMD Friction Holdings GmbH
11.12 Sangsin Brake Co., Ltd.
11.13 ASK Automotive Limited
11.14 Miba AG
11.15 EBC Brakes
List of Tables
1 Global Automotive Copper-Free Brake Pad Market Outlook, By Region (2023–2034) ($MN)
2 Global Automotive Copper-Free Brake Pad Market Outlook, By Friction Formulation (2023–2034) ($MN)
3 Global Automotive Copper-Free Brake Pad Market Outlook, By Ceramic and Copper-Free NAO (2023–2034) ($MN)
4 Global Automotive Copper-Free Brake Pad Market Outlook, By Low-Metallic Copper-Free Formulations (2023–2034) ($MN)
5 Global Automotive Copper-Free Brake Pad Market Outlook, By Semi-Metallic Copper-Free Formulations (2023–2034) ($MN)
6 Global Automotive Copper-Free Brake Pad Market Outlook, By Low-Dust and Low-Emission Materials (2023–2034) ($MN)
7 Global Automotive Copper-Free Brake Pad Market Outlook, By Product Type (2023–2034) ($MN)
8 Global Automotive Copper-Free Brake Pad Market Outlook, By Disc Brake Pads (2023–2034) ($MN)
9 Global Automotive Copper-Free Brake Pad Market Outlook, By Drum Brake Linings (2023–2034) ($MN)
10 Global Automotive Copper-Free Brake Pad Market Outlook, By Commercial Vehicle Brake Pads (2023–2034) ($MN)
11 Global Automotive Copper-Free Brake Pad Market Outlook, By Vehicle Type (2023–2034) ($MN)
12 Global Automotive Copper-Free Brake Pad Market Outlook, By Passenger Cars (2023–2034) ($MN)
13 Global Automotive Copper-Free Brake Pad Market Outlook, By Light Commercial Vehicles (2023–2034) ($MN)
14 Global Automotive Copper-Free Brake Pad Market Outlook, By Heavy Commercial Vehicles (2023–2034) ($MN)
15 Global Automotive Copper-Free Brake Pad Market Outlook, By Electric and Hybrid Vehicles (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
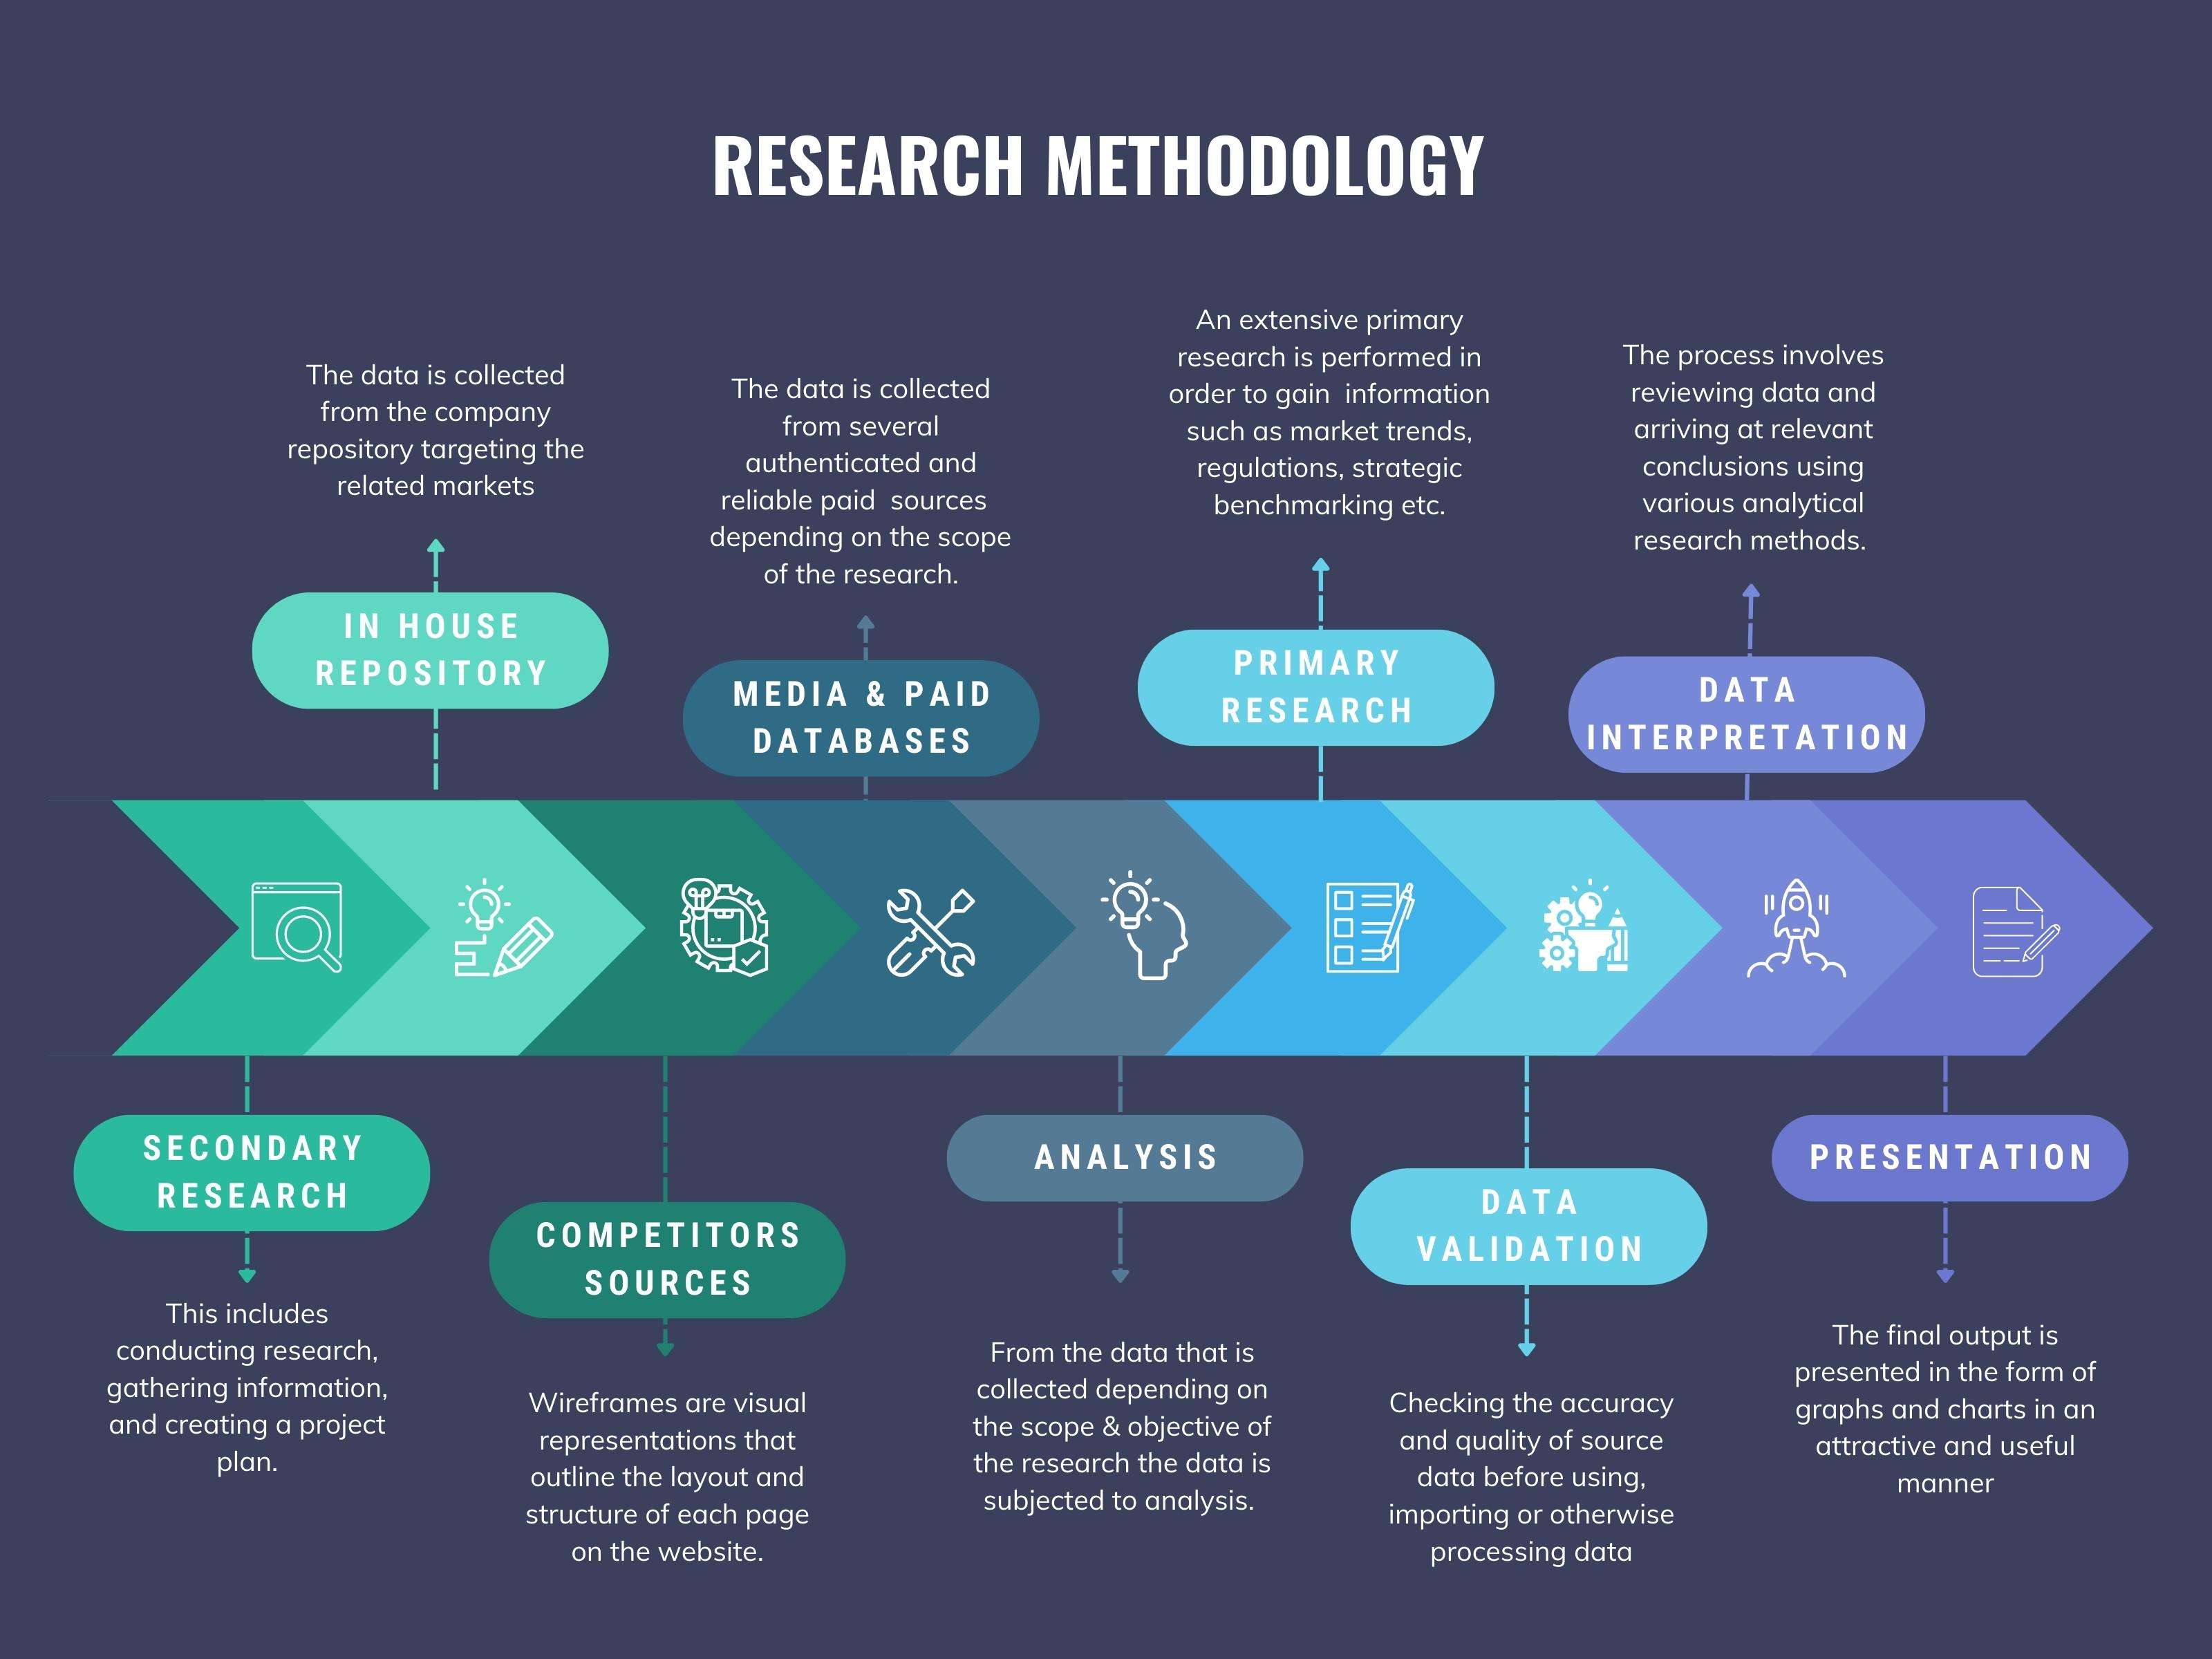
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.