Automotive Domain And Zonal Controller Market
Automotive Domain & Zonal Controller Market Forecasts To 2034 – Global Analysis By Architecture (Distributed ECU Architecture, Domain Controller Architecture, Hybrid Domain-Zonal Architecture, Zonal Architecture with Centralized Compute and Fully Zonal Architecture), Controller Type, Component, Domain, Network Architecture, Vehicle Type, Propulsion, Vehicle Segment, Communication Technology, Application, End User and By Geography
According to Stratistics MRC, the Global Automotive Domain & Zonal Controller Market is accounted for $10.4 billion in 2026 and is expected to reach $42.9 billion by 2034 growing at a CAGR of 19.4% during the forecast period. The Automotive Domain & Zonal Controller Market is witnessing strong growth as automakers adopt software-defined vehicle architectures and centralized electronic systems. Domain controllers integrate functions such as powertrain management, ADAS, infotainment, body control, and connectivity, whereas zonal controllers coordinate electronic devices within defined vehicle areas. The increasing deployment of electric vehicles, connected technologies, advanced driver assistance, and over-the-air updates is driving market demand. Manufacturers are shifting from numerous decentralized electronic control units toward centralized, high-performance computing platforms that can simplify wiring, reduce vehicle weight, and lower system complexity. Rising investments in autonomous driving, cybersecurity, vehicle networking, and flexible vehicle platforms are also contributing to market expansion.
Market Dynamics:
Driver:
Increasing Adoption of Software-Defined Vehicles
The transition toward software-defined vehicles is significantly supporting growth in the Automotive Domain & Zonal Controller Market. Vehicles are becoming increasingly software-centric, with software controlling infotainment, connectivity, advanced driver assistance, vehicle performance, and body-related functions. Domain and zonal controllers enable centralized processing, streamlined software management, continuous updates, and easier integration of new features. Automakers are replacing complex networks of individual electronic control units with centralized architectures that can reduce system complexity and improve computing performance. Rising consumer expectations for connected and customizable vehicle features, combined with the increasing use of over-the-air updates and software-based functionality, are driving automotive manufacturers to incorporate sophisticated domain and zonal controllers into next-generation vehicle platforms.
Restraint:
High Initial Development and Integration Costs
Significant upfront investment requirements can limit the adoption of Automotive Domain & Zonal Controllers. These architectures depend on advanced processors, high-speed communication networks, sophisticated software, cybersecurity solutions, and extensive validation processes, all of which require considerable capital. Automakers and suppliers may also need to redesign established electrical and electronic systems to support centralized computing architectures. Connecting new controllers with existing vehicle technologies can increase engineering complexity, development expenditure, and project timelines. Smaller manufacturers may experience greater financial pressure because they typically have fewer resources for research and development. Moreover, functional safety testing and system validation requirements can raise implementation expenses and delay adoption across price-sensitive automotive applications.
Opportunity:
Increasing Demand for Advanced Vehicle Networking
The increasing requirement for fast, reliable, and scalable vehicle communication networks is creating significant opportunities for domain and zonal controller suppliers. Modern automobiles produce large quantities of information through cameras, sensors, infotainment platforms, electronic systems, and connected applications. Conventional communication architectures may not adequately support the bandwidth, processing speed, and latency requirements of emerging automotive functions. Centralized and zonal architectures increasingly depend on automotive Ethernet and other high-speed networking technologies to connect vehicle components with central computing systems. This environment enables suppliers to develop controllers featuring integrated networking, intelligent gateway functions, and advanced communication interfaces, while the growth of connected and automated vehicles is further expanding the addressable market.
Threat:
Cyberattacks and Increasing Automotive Cybersecurity Risks
Greater vehicle connectivity and centralized electronic architectures are increasing exposure to cybersecurity risks, creating a potential threat to market development. Domain and zonal controllers may connect multiple vehicle functions, sensors, networks, and external digital services, increasing the importance of comprehensive security measures. Cyberattacks could potentially affect vehicle information, software, communications, or connected features. Consequently, manufacturers and suppliers need to invest continuously in encryption, authentication, intrusion detection, secure software practices, and monitoring technologies. Meeting these requirements can increase engineering, testing, and maintenance expenditures while also creating potential liability concerns. The continuous emergence of new cybersecurity techniques further requires regular software updates and security enhancements throughout the vehicle lifecycle.
Covid-19 Impact:
The COVID-19 outbreak disrupted the Automotive Domain & Zonal Controller Market through interruptions in vehicle manufacturing, component supply chains, and semiconductor production. Temporary factory shutdowns, labor limitations, logistics constraints, and weaker vehicle demand caused delays in automotive programs and investments in advanced electronic systems. Suppliers experienced difficulties sourcing processors, microcontrollers, communication chips, and other essential components. At the same time, the pandemic encouraged greater digital transformation within the automotive industry and strengthened interest in connected vehicles, software-defined architectures, and automation. With automotive production progressively recovering, manufacturers renewed investments in electric mobility, ADAS, connectivity, and centralized electronic systems, creating opportunities for renewed demand for domain and zonal controllers.
The Hardware segment is expected to be the largest during the forecast period
The Hardware segment is expected to account for the largest market share during the forecast period, supported by increasing integration of advanced processors, microcontrollers, networking devices, memory components, sensors, and electronic computing systems in vehicles. Domain and zonal controllers require capable hardware platforms to handle substantial data volumes and manage diverse vehicle functions efficiently. The expanding adoption of electric mobility, connected vehicle technologies, ADAS, and software-defined architectures is further increasing the need for high-performance and scalable computing hardware. In addition, advancements in automotive semiconductors and high-speed vehicle communication technologies are reinforcing the role of hardware as a fundamental component of modern domain and zonal controller systems.
The ADAS & Autonomous Driving segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the ADAS & Autonomous Driving segment is predicted to witness the highest growth rate, driven by the expanding deployment of advanced driver assistance and automated driving functions. Such systems require powerful computing architectures to rapidly process information from cameras, radar, LiDAR, and other sensing technologies. Domain controllers provide centralized computational capabilities for coordinating perception, decision-making, and vehicle control, while zonal controllers facilitate efficient connectivity with sensors and actuators positioned throughout the vehicle. Increasing development of automated driving capabilities, stronger emphasis on vehicle safety, and continued investment in autonomous mobility technologies are encouraging automakers to adopt sophisticated centralized electronic architectures, thereby creating substantial growth opportunities for ADAS and autonomous driving controller applications.
Region with largest share:
During the forecast period, the Asia Pacific region is expected to hold the largest market share, driven by its extensive automotive production ecosystem and growing implementation of advanced electronic technologies. Countries across the region are expanding investments in electric mobility, connected automobiles, ADAS, and software-defined vehicle platforms. A strong presence of automakers, automotive technology suppliers, semiconductor manufacturers, and electronics companies further supports regional controller development. Rising vehicle manufacturing volumes, growing demand for intelligent and digitally connected vehicles, and increasing investments in electrification and smart mobility solutions are encouraging the transition toward centralized electrical and electronic architectures, thereby supporting the wider adoption of domain and zonal controllers throughout Asia Pacific.
Region with highest CAGR:
Over the forecast period, the North America region is anticipated to exhibit the highest CAGR, driven by increasing development of software-defined vehicles, autonomous driving systems, ADAS, and connected automotive technologies. Automotive manufacturers and technology providers across the region are investing heavily in centralized electronic architectures that use high-performance domain and zonal controllers to manage diverse vehicle functions. Strong regional expertise in automotive software, artificial intelligence, semiconductors, and vehicle communication technologies further supports market development. In addition, expanding electric vehicle adoption, rising demand for sophisticated safety and connectivity functions, and sustained investments in autonomous mobility are encouraging broader implementation of centralized automotive electronic systems.
Key players in the market
Some of the key players in Automotive Domain & Zonal Controller Market include Robert Bosch GmbH, Continental AG, Aptiv PLC, ZF Friedrichshafen AG, Visteon Corporation, Valeo SE, DENSO Corporation, Marelli Holdings Co., Ltd., FORVIA SE, Magna International Inc., Lear Corporation, HARMAN International Industries, Inc., Hyundai Mobis Co., Ltd., NXP Semiconductors N.V., Infineon Technologies AG, STMicroelectronics N.V., Qualcomm Technologies, Inc. and Texas Instruments Incorporated.
Key Developments:
In May 2026, Aptiv joined SDVerse, an automotive B2B software marketplace, through a collaboration designed to expand OEM and supplier access to Aptiv’s AI, software, and edge-to-cloud solutions. The partnership supports development and deployment of software-defined vehicle technologies and intelligent edge systems.
In March 2026, Bosch Limited and Tata AutoComp Systems announced a 50:50 joint venture focused on engineering, manufacturing, and sales of eAxle systems and electric motors in India. The partnership is primarily focused on e-mobility rather than domain/zonal controllers, so it is an adjacent automotive-electronics development rather than a direct controller partnership.
In January 2026, Visteon announced an expanded technology partnership with Mahindra & Mahindra for its next-generation SmartCore Pro cockpit domain controller. The system integrates cockpit electronics, surround-view cameras, and telematics for Mahindra’s XUV7X0 lineup, strengthening the companies’ collaboration on centralized cockpit computing.
Architectures Covered:
• Distributed ECU Architecture
• Domain Controller Architecture
• Hybrid Domain-Zonal Architecture
• Zonal Architecture with Centralized Compute
• Fully Zonal Architecture
Controller Types Covered:
• Domain Controllers
• Zonal Controllers
• Integrated Domain-Zonal Controllers
• Central Vehicle Controllers
• Vehicle Gateway Controllers
Components Covered:
• Hardware
• Software
• Services
Domains Covered:
• ADAS & Autonomous Driving
• Cockpit & Infotainment
• Powertrain
• Body & Comfort
• Chassis & Motion
• Vehicle Connectivity & Gateway
Network Architectures Covered:
• Ethernet Backbone
• Zonal Ethernet Network
• CAN/CAN FD Edge Network
• LIN Edge Network
• Ethernet-to-CAN/LIN Gateway
• Centralized Network Topology
• Hierarchical Network Topology
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles
• Medium Commercial Vehicles
• Heavy Commercial Vehicles
• Buses
• Two-Wheelers
• Three-Wheelers
• Off-Highway Vehicles
Propulsions Covered:
• Internal Combustion Engine Vehicles
• Mild Hybrid Electric Vehicles
• Full Hybrid Electric Vehicles
• Plug-in Hybrid Electric Vehicles
• Battery Electric Vehicles
• Fuel Cell Electric Vehicles
Vehicle Segments Covered:
• Economy Vehicles
• Mid-Range Vehicles
• Premium Vehicles
• Luxury Vehicles
Communication Technologies Covered:
• Automotive Ethernet
• CAN
• CAN FD
• CAN XL
• LIN
• FlexRay
• Wireless Communication
Applications Covered:
• ADAS & Autonomous Driving
• Cockpit & Infotainment
• Connectivity & Telematics
• Body & Comfort
• Powertrain & Energy Management
• Chassis & Motion Control
• Vehicle Safety & Security
• Lighting Control
• Thermal Management
End Users Covered:
• Automotive OEMs
• Tier-1 Suppliers
• Autonomous Vehicle Developers
• Mobility & Fleet Operators
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Domain & Zonal Controller Market, By Architecture
5.1 Distributed ECU Architecture
5.2 Domain Controller Architecture
5.3 Hybrid Domain-Zonal Architecture
5.4 Zonal Architecture with Centralized Compute
5.5 Fully Zonal Architecture
6 Global Automotive Domain & Zonal Controller Market, By Controller Type
6.1 Domain Controllers
6.2 Zonal Controllers
6.3 Integrated Domain-Zonal Controllers
6.4 Central Vehicle Controllers
6.5 Vehicle Gateway Controllers
7 Global Automotive Domain & Zonal Controller Market, By Component
7.1 Hardware
7.2 Software
7.3 Services
8 Global Automotive Domain & Zonal Controller Market, By Domain
8.1 ADAS & Autonomous Driving
8.2 Cockpit & Infotainment
8.3 Powertrain
8.4 Body & Comfort
8.5 Chassis & Motion
8.6 Vehicle Connectivity & Gateway
9 Global Automotive Domain & Zonal Controller Market, By Network Architecture
9.1 Ethernet Backbone
9.2 Zonal Ethernet Network
9.3 CAN/CAN FD Edge Network
9.4 LIN Edge Network
9.5 Ethernet-to-CAN/LIN Gateway
9.6 Centralized Network Topology
9.7 Hierarchical Network Topology
10 Global Automotive Domain & Zonal Controller Market, By Vehicle Type
10.1 Passenger Cars
10.2 Light Commercial Vehicles
10.3 Medium Commercial Vehicles
10.4 Heavy Commercial Vehicles
10.5 Buses
10.6 Two-Wheelers
10.7 Three-Wheelers
10.8 Off-Highway Vehicles
11 Global Automotive Domain & Zonal Controller Market, By Propulsion
11.1 Internal Combustion Engine Vehicles
11.2 Mild Hybrid Electric Vehicles
11.3 Full Hybrid Electric Vehicles
11.4 Plug-in Hybrid Electric Vehicles
11.5 Battery Electric Vehicles
11.6 Fuel Cell Electric Vehicles
12 Global Automotive Domain & Zonal Controller Market, By Vehicle Segment
12.1 Economy Vehicles
12.2 Mid-Range Vehicles
12.3 Premium Vehicles
12.4 Luxury Vehicles
13 Global Automotive Domain & Zonal Controller Market, By Communication Technology
13.1 Automotive Ethernet
13.2 CAN
13.3 CAN FD
13.4 CAN XL
13.5 LIN
13.6 FlexRay
13.7 Wireless Communication
14 Global Automotive Domain & Zonal Controller Market, By Application
14.1 ADAS & Autonomous Driving
14.2 Cockpit & Infotainment
14.3 Connectivity & Telematics
14.4 Body & Comfort
14.5 Powertrain & Energy Management
14.6 Chassis & Motion Control
14.7 Vehicle Safety & Security
14.8 Lighting Control
14.9 Thermal Management
15 Global Automotive Domain & Zonal Controller Market, By End User
15.1 Automotive OEMs
15.2 Tier-1 Suppliers
15.3 Autonomous Vehicle Developers
15.4 Mobility & Fleet Operators
16 Global Automotive Domain & Zonal Controller Market, By Geography
16.1 North America
16.1.1 United States
16.1.2 Canada
16.1.3 Mexico
16.2 Europe
16.2.1 United Kingdom
16.2.2 Germany
16.2.3 France
16.2.4 Italy
16.2.5 Spain
16.2.6 Netherlands
16.2.7 Belgium
16.2.8 Sweden
16.2.9 Switzerland
16.2.10 Poland
16.2.11 Rest of Europe
16.3 Asia Pacific
16.3.1 China
16.3.2 Japan
16.3.3 India
16.3.4 South Korea
16.3.5 Australia
16.3.6 Indonesia
16.3.7 Thailand
16.3.8 Malaysia
16.3.9 Singapore
16.3.10 Vietnam
16.3.11 Rest of Asia Pacific
16.4 South America
16.4.1 Brazil
16.4.2 Argentina
16.4.3 Colombia
16.4.4 Chile
16.4.5 Peru
16.4.6 Rest of South America
16.5 Rest of the World (RoW)
16.5.1 Middle East
16.5.1.1 Saudi Arabia
16.5.1.2 United Arab Emirates
16.5.1.3 Qatar
16.5.1.4 Israel
16.5.1.5 Rest of Middle East
16.5.2 Africa
16.5.2.1 South Africa
16.5.2.2 Egypt
16.5.2.3 Morocco
16.5.2.4 Rest of Africa
17 Strategic Market Intelligence
17.1 Industry Value Network and Supply Chain Assessment
17.2 White-Space and Opportunity Mapping
17.3 Product Evolution and Market Life Cycle Analysis
17.4 Channel, Distributor, and Go-to-Market Assessment
18 Industry Developments and Strategic Initiatives
18.1 Mergers and Acquisitions
18.2 Partnerships, Alliances, and Joint Ventures
18.3 New Product Launches and Certifications
18.4 Capacity Expansion and Investments
18.5 Other Strategic Initiatives
19 Company Profiles
19.1 Robert Bosch GmbH
19.2 Continental AG
19.3 Aptiv PLC
19.4 ZF Friedrichshafen AG
19.5 Visteon Corporation
19.6 Valeo SE
19.7 DENSO Corporation
19.8 Marelli Holdings Co., Ltd.
19.9 FORVIA SE
19.10 Magna International Inc.
19.11 Lear Corporation
19.12 HARMAN International Industries, Inc.
19.13 Hyundai Mobis Co., Ltd.
19.14 NXP Semiconductors N.V.
19.15 Infineon Technologies AG
19.16 STMicroelectronics N.V.
19.17 Qualcomm Technologies, Inc.
19.18 Texas Instruments Incorporated
List of Tables
1 Global Automotive Domain & Zonal Controller Market Outlook, By Region (2023-2034) ($MN)
2 Global Automotive Domain & Zonal Controller Market Outlook, By Architecture (2023-2034) ($MN)
3 Global Automotive Domain & Zonal Controller Market Outlook, By Distributed ECU Architecture (2023-2034) ($MN)
4 Global Automotive Domain & Zonal Controller Market Outlook, By Domain Controller Architecture (2023-2034) ($MN)
5 Global Automotive Domain & Zonal Controller Market Outlook, By Hybrid Domain-Zonal Architecture (2023-2034) ($MN)
6 Global Automotive Domain & Zonal Controller Market Outlook, By Zonal Architecture with Centralized Compute (2023-2034) ($MN)
7 Global Automotive Domain & Zonal Controller Market Outlook, By Fully Zonal Architecture (2023-2034) ($MN)
8 Global Automotive Domain & Zonal Controller Market Outlook, By Controller Type (2023-2034) ($MN)
9 Global Automotive Domain & Zonal Controller Market Outlook, By Domain Controllers (2023-2034) ($MN)
10 Global Automotive Domain & Zonal Controller Market Outlook, By Zonal Controllers (2023-2034) ($MN)
11 Global Automotive Domain & Zonal Controller Market Outlook, By Integrated Domain-Zonal Controllers (2023-2034) ($MN)
12 Global Automotive Domain & Zonal Controller Market Outlook, By Central Vehicle Controllers (2023-2034) ($MN)
13 Global Automotive Domain & Zonal Controller Market Outlook, By Vehicle Gateway Controllers (2023-2034) ($MN)
14 Global Automotive Domain & Zonal Controller Market Outlook, By Component (2023-2034) ($MN)
15 Global Automotive Domain & Zonal Controller Market Outlook, By Hardware (2023-2034) ($MN)
16 Global Automotive Domain & Zonal Controller Market Outlook, By Software (2023-2034) ($MN)
17 Global Automotive Domain & Zonal Controller Market Outlook, By Services (2023-2034) ($MN)
18 Global Automotive Domain & Zonal Controller Market Outlook, By Domain (2023-2034) ($MN)
19 Global Automotive Domain & Zonal Controller Market Outlook, By ADAS & Autonomous Driving (2023-2034) ($MN)
20 Global Automotive Domain & Zonal Controller Market Outlook, By Cockpit & Infotainment (2023-2034) ($MN)
21 Global Automotive Domain & Zonal Controller Market Outlook, By Powertrain (2023-2034) ($MN)
22 Global Automotive Domain & Zonal Controller Market Outlook, By Body & Comfort (2023-2034) ($MN)
23 Global Automotive Domain & Zonal Controller Market Outlook, By Chassis & Motion (2023-2034) ($MN)
24 Global Automotive Domain & Zonal Controller Market Outlook, By Vehicle Connectivity & Gateway (2023-2034) ($MN)
25 Global Automotive Domain & Zonal Controller Market Outlook, By Network Architecture (2023-2034) ($MN)
26 Global Automotive Domain & Zonal Controller Market Outlook, By Ethernet Backbone (2023-2034) ($MN)
27 Global Automotive Domain & Zonal Controller Market Outlook, By Zonal Ethernet Network (2023-2034) ($MN)
28 Global Automotive Domain & Zonal Controller Market Outlook, By CAN/CAN FD Edge Network (2023-2034) ($MN)
29 Global Automotive Domain & Zonal Controller Market Outlook, By LIN Edge Network (2023-2034) ($MN)
30 Global Automotive Domain & Zonal Controller Market Outlook, By Ethernet-to-CAN/LIN Gateway (2023-2034) ($MN)
31 Global Automotive Domain & Zonal Controller Market Outlook, By Centralized Network Topology (2023-2034) ($MN)
32 Global Automotive Domain & Zonal Controller Market Outlook, By Hierarchical Network Topology (2023-2034) ($MN)
33 Global Automotive Domain & Zonal Controller Market Outlook, By Vehicle Type (2023-2034) ($MN)
34 Global Automotive Domain & Zonal Controller Market Outlook, By Passenger Cars (2023-2034) ($MN)
35 Global Automotive Domain & Zonal Controller Market Outlook, By Light Commercial Vehicles (2023-2034) ($MN)
36 Global Automotive Domain & Zonal Controller Market Outlook, By Medium Commercial Vehicles (2023-2034) ($MN)
37 Global Automotive Domain & Zonal Controller Market Outlook, By Heavy Commercial Vehicles (2023-2034) ($MN)
38 Global Automotive Domain & Zonal Controller Market Outlook, By Buses (2023-2034) ($MN)
39 Global Automotive Domain & Zonal Controller Market Outlook, By Two-Wheelers (2023-2034) ($MN)
40 Global Automotive Domain & Zonal Controller Market Outlook, By Three-Wheelers (2023-2034) ($MN)
41 Global Automotive Domain & Zonal Controller Market Outlook, By Off-Highway Vehicles (2023-2034) ($MN)
42 Global Automotive Domain & Zonal Controller Market Outlook, By Propulsion (2023-2034) ($MN)
43 Global Automotive Domain & Zonal Controller Market Outlook, By Internal Combustion Engine Vehicles (2023-2034) ($MN)
44 Global Automotive Domain & Zonal Controller Market Outlook, By Mild Hybrid Electric Vehicles (2023-2034) ($MN)
45 Global Automotive Domain & Zonal Controller Market Outlook, By Full Hybrid Electric Vehicles (2023-2034) ($MN)
46 Global Automotive Domain & Zonal Controller Market Outlook, By Plug-in Hybrid Electric Vehicles (2023-2034) ($MN)
47 Global Automotive Domain & Zonal Controller Market Outlook, By Battery Electric Vehicles (2023-2034) ($MN)
48 Global Automotive Domain & Zonal Controller Market Outlook, By Fuel Cell Electric Vehicles (2023-2034) ($MN)
49 Global Automotive Domain & Zonal Controller Market Outlook, By Vehicle Segment (2023-2034) ($MN)
50 Global Automotive Domain & Zonal Controller Market Outlook, By Economy Vehicles (2023-2034) ($MN)
51 Global Automotive Domain & Zonal Controller Market Outlook, By Mid-Range Vehicles (2023-2034) ($MN)
52 Global Automotive Domain & Zonal Controller Market Outlook, By Premium Vehicles (2023-2034) ($MN)
53 Global Automotive Domain & Zonal Controller Market Outlook, By Luxury Vehicles (2023-2034) ($MN)
54 Global Automotive Domain & Zonal Controller Market Outlook, By Communication Technology (2023-2034) ($MN)
55 Global Automotive Domain & Zonal Controller Market Outlook, By Automotive Ethernet (2023-2034) ($MN)
56 Global Automotive Domain & Zonal Controller Market Outlook, By CAN (2023-2034) ($MN)
57 Global Automotive Domain & Zonal Controller Market Outlook, By CAN FD (2023-2034) ($MN)
58 Global Automotive Domain & Zonal Controller Market Outlook, By CAN XL (2023-2034) ($MN)
59 Global Automotive Domain & Zonal Controller Market Outlook, By LIN (2023-2034) ($MN)
60 Global Automotive Domain & Zonal Controller Market Outlook, By FlexRay (2023-2034) ($MN)
61 Global Automotive Domain & Zonal Controller Market Outlook, By Wireless Communication (2023-2034) ($MN)
62 Global Automotive Domain & Zonal Controller Market Outlook, By Application (2023-2034) ($MN)
63 Global Automotive Domain & Zonal Controller Market Outlook, By ADAS & Autonomous Driving (2023-2034) ($MN)
64 Global Automotive Domain & Zonal Controller Market Outlook, By Cockpit & Infotainment (2023-2034) ($MN)
65 Global Automotive Domain & Zonal Controller Market Outlook, By Connectivity & Telematics (2023-2034) ($MN)
66 Global Automotive Domain & Zonal Controller Market Outlook, By Body & Comfort (2023-2034) ($MN)
67 Global Automotive Domain & Zonal Controller Market Outlook, By Powertrain & Energy Management (2023-2034) ($MN)
68 Global Automotive Domain & Zonal Controller Market Outlook, By Chassis & Motion Control (2023-2034) ($MN)
69 Global Automotive Domain & Zonal Controller Market Outlook, By Vehicle Safety & Security (2023-2034) ($MN)
70 Global Automotive Domain & Zonal Controller Market Outlook, By Lighting Control (2023-2034) ($MN)
71 Global Automotive Domain & Zonal Controller Market Outlook, By Thermal Management (2023-2034) ($MN)
72 Global Automotive Domain & Zonal Controller Market Outlook, By End User (2023-2034) ($MN)
73 Global Automotive Domain & Zonal Controller Market Outlook, By Automotive OEMs (2023-2034) ($MN)
74 Global Automotive Domain & Zonal Controller Market Outlook, By Tier-1 Suppliers (2023-2034) ($MN)
75 Global Automotive Domain & Zonal Controller Market Outlook, By Autonomous Vehicle Developers (2023-2034) ($MN)
76 Global Automotive Domain & Zonal Controller Market Outlook, By Mobility & Fleet Operators (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
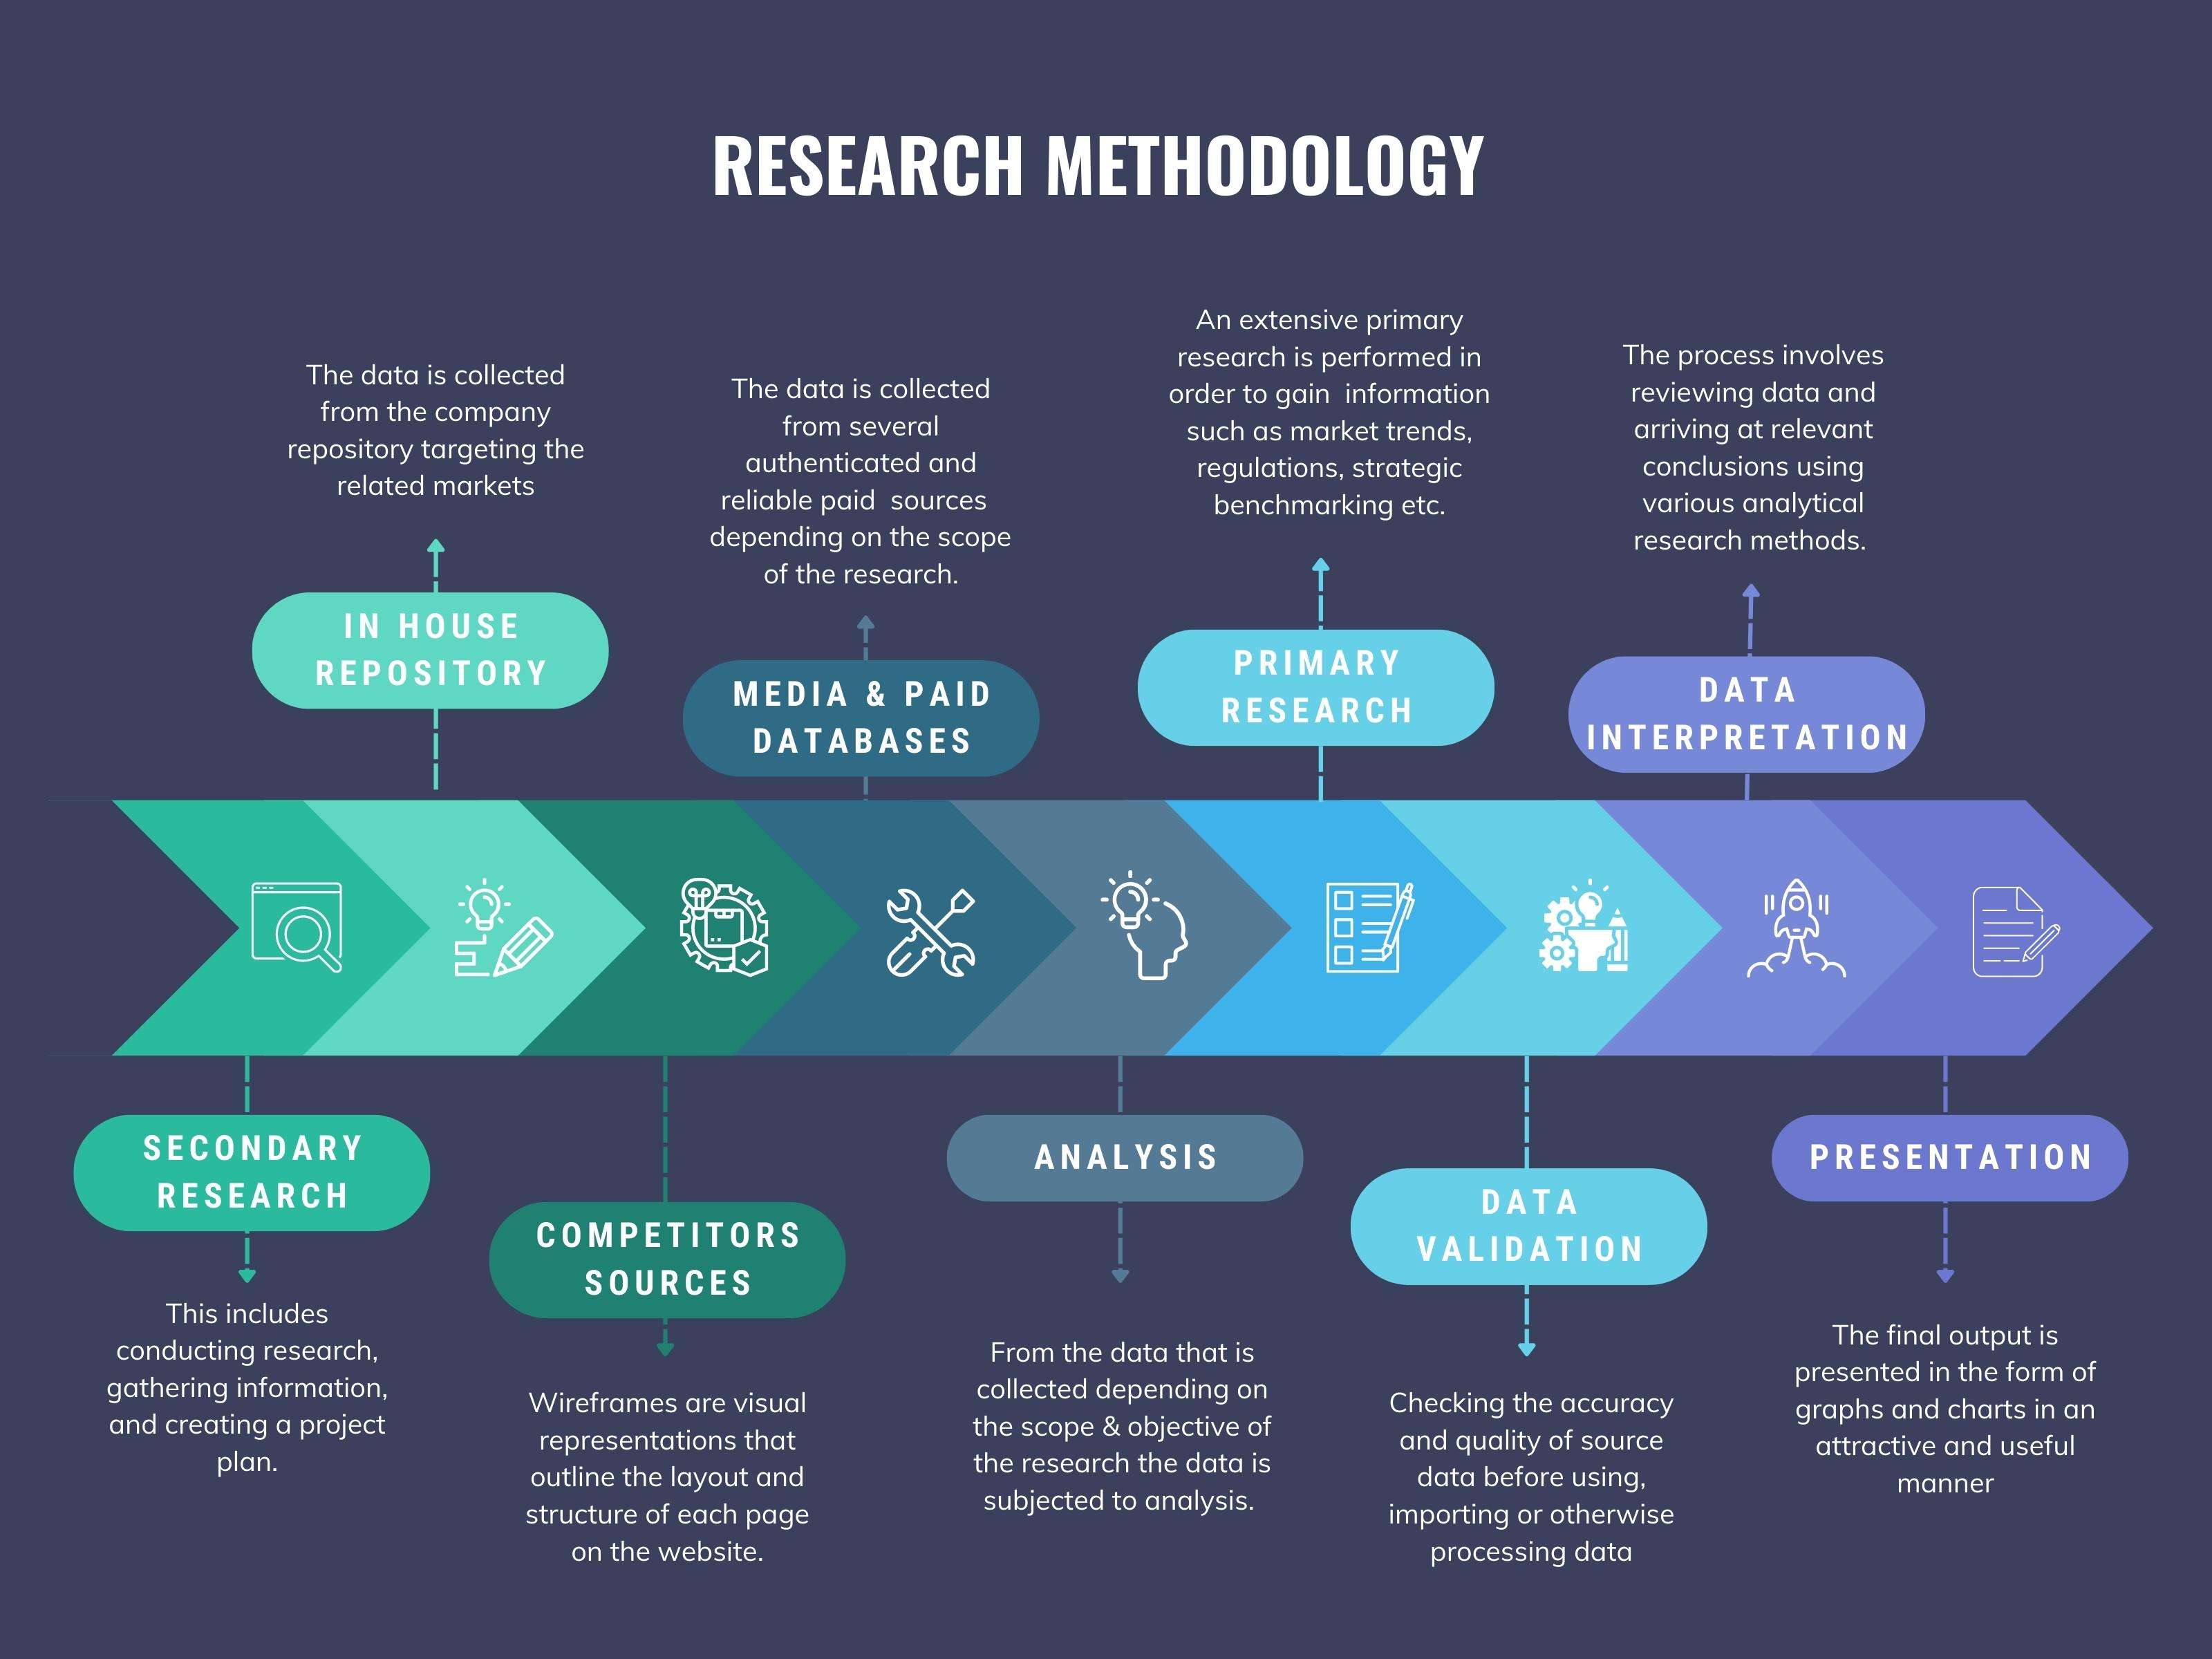
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.