Bio Based Flexible Packaging Market
Bio-Based Flexible Packaging Market Forecasts to 2034 – Global Analysis By Feedstock (Corn-Based Feedstocks, Sugarcane-Based Feedstocks, Cellulose Feedstocks, Starch Feedstocks and Vegetable Oil Feedstocks), Polymer Type, Packaging Format, Material Property, Application, End User and By Geography
According to Stratistics MRC, the Global Bio-Based Flexible Packaging Market is accounted for $3.6 billion in 2026 and is expected to reach $6.9 billion by 2034 growing at a CAGR of 8.4% during the forecast period. Bio-based flexible packaging refers to pliable packaging materials derived from renewable biological feedstocks including corn starch, sugarcane, vegetable oils, and cellulose that provide barrier protection, sealability, and product containment while reducing dependence on fossil fuel-derived polymers. These packaging solutions utilize biobased polyethylene, polylactic acid, polyhydroxyalkanoates, and cellulose derivatives manufactured through biological or biochemical conversion processes to create films, pouches, bags, and wraps. The technology enables carbon footprint reduction across packaging life cycles by incorporating atmospheric carbon captured during biomass cultivation while delivering functional performance comparable to conventional petroleum-based flexible packaging in food, beverage, and consumer goods applications.
Market Dynamics:
Driver:
Carbon Neutrality Goals
Corporate carbon neutrality goals are driving bio-based flexible packaging adoption as consumer brands and retailers establish science-based targets requiring Scope 3 emissions reductions throughout supply chains including packaging materials. Bio-based polymers derived from renewable feedstocks offer quantifiable carbon footprint advantages over conventional plastics by replacing fossil carbon with biogenic carbon captured during plant growth. Major food and beverage companies are integrating bio-based packaging specifications into procurement criteria as they pursue net-zero commitments and respond to investor pressure for climate action. Lifecycle assessment data demonstrating bio-based packaging emissions reductions is increasingly influencing purchasing decisions among environmentally committed brand owners.
Restraint:
Feedstock Competition
Agricultural feedstock competition constrains bio-based flexible packaging market expansion as corn, sugarcane, and vegetable oil resources face competing demands from food production, biofuel manufacturing, and other industrial bioprocessing applications. Crop price volatility driven by weather events, trade policies, and global food security concerns creates raw material cost uncertainty that complicates long-term bio-based polymer pricing strategies. The land use requirements for dedicated bio-based packaging feedstock cultivation raise sustainability concerns regarding deforestation, biodiversity impacts, and food crop displacement in sensitive ecological regions. Competition for agricultural resources from established biofuel mandates in major economies limits available feedstock volumes for packaging polymer production.
Opportunity:
Advanced Biopolymer Development
Next-generation biopolymer development presents substantial growth opportunities as research institutions and chemical companies engineer novel bio-based materials with enhanced barrier properties, thermal stability, and processing characteristics that rival petroleum-derived alternatives. Advanced fermentation and catalytic conversion technologies are enabling production of bio-based polymers with molecular structures optimized for flexible packaging applications including high-barrier films and heat-sealable laminates. Strategic partnerships between agricultural processors, biotechnology firms, and packaging manufacturers are accelerating commercial scale-up of second and third-generation bio-based materials utilizing non-food feedstocks and agricultural residues. These technological advances are expanding addressable markets to include demanding applications previously considered incompatible with bio-based materials.
Threat:
Fossil Plastic Price Volatility
Fossil fuel price volatility threatens bio-based flexible packaging competitiveness as periodic declines in petroleum and natural gas prices reduce conventional plastic production costs, widening the price premium for bio-based alternatives. Petrochemical producers benefit from massive existing infrastructure, established supply chains, and decades of process optimization that enable rapid cost adjustments in response to feedstock price fluctuations. Bio-based polymer manufacturing, which requires significant capital investment in fermentation and purification facilities, cannot match this production cost flexibility. Price competition from low-cost conventional plastics is particularly challenging during energy market downturns when brand owners face margin pressure and reduced willingness to pay sustainability premiums.
Covid-19 Impact:
COVID-19 initially disrupted bio-based flexible packaging supply chains through agricultural feedstock collection interruptions and biopolymer manufacturing facility shutdowns. Mid-pandemic single-use plastic consumption increases in hygiene and food delivery applications temporarily reduced bio-based packaging momentum. Post-pandemic renewed corporate sustainability commitments and consumer environmental awareness have structurally elevated bio-based packaging as a strategic priority for brand differentiation. The pandemic ultimately reinforced supply chain resilience considerations that favor diversified feedstock sources including regional agricultural resources supporting bio-based polymer production.
The corn-based feedstocks segment is expected to be the largest during the forecast period
The corn-based feedstocks segment is expected to account for the largest market share during the forecast period, due to the established global corn starch processing infrastructure that provides cost-competitive glucose feedstock for polylactic acid and bio-polyethylene production at commercial scale. The United States and Brazil maintain abundant corn supplies with mature agricultural processing industries that efficiently convert starch into fermentation-ready sugars for biopolymer manufacturing. Corn-derived feedstocks offer consistent quality, predictable pricing, and well-understood processing characteristics that reduce manufacturing variability and quality control complexity. Major bio-based polymer producers have optimized their production platforms specifically for corn starch feedstock, creating supply chain efficiencies that sustain competitive economics.
The polylactic acid segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the polylactic acid segment is predicted to witness the highest growth rate, driven by expanding production capacity, improving material properties, and broadening application scope across food packaging, agricultural films, and textile packaging sectors. Polylactic acid offers excellent clarity, printability, and grease resistance combined with industrial compostability that addresses end-of-life concerns for single-use flexible packaging applications. Major chemical companies are investing in next-generation PLA production facilities with enhanced heat resistance and barrier properties that enable substitution of conventional plastics in hot-fill and microwaveable packaging. Regulatory support for compostable packaging in European and Asian markets is accelerating PLA adoption across food service and fresh produce packaging segments.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, due to the United States possessing the world's most developed bio-based polymer industry with substantial corn feedstock availability and advanced biorefining infrastructure. Major North American chemical and packaging companies are leading global bio-based flexible packaging commercialization through integrated supply chains connecting agricultural processing to film manufacturing and brand owner partnerships. Strong consumer demand for sustainable packaging alternatives and willingness to pay modest premiums for bio-based products supports market development across food, beverage, and personal care categories. Favorable regulatory treatment of bio-based materials under federal procurement guidelines and state-level sustainability initiatives reinforces market growth.
Region with highest CAGR:
Over the forecast period, the Europe region is anticipated to exhibit the highest CAGR, due to aggressive regulatory frameworks including the European Green Deal and Packaging and Packaging Waste Regulation that mandate substantial reductions in fossil-based packaging materials. European Union member states are implementing extended producer responsibility schemes with specific bio-based and compostable packaging incentives that directly accelerate market adoption. Major European food retailers and quick-service restaurant chains are establishing bio-based packaging procurement targets that create predictable demand for flexible packaging converters. Strong consumer environmental consciousness combined with established industrial composting infrastructure provides favorable end-of-life conditions that support bio-based flexible packaging growth throughout the region.
Key players in the market
Some of the key players in Bio-Based Flexible Packaging Market include Amcor plc, Mondi plc, Berry Global Group, Inc., Sealed Air Corporation, BASF SE, Corbion N.V., Celanese Corporation, Braskem S.A., NatureWorks LLC, TotalEnergies SE, Stora Enso Oyj, Huhtamäki Oyj, UFlex Limited, Jindal Poly Films Limited, Mitsubishi Chemical Group Corporation, Toray Industries, Inc., and Kuraray Co., Ltd..
Key Developments:
In August 2026, NatureWorks LLC launched a next-generation Ingeo polylactic acid resin achieving enhanced heat resistance for hot-fill flexible food packaging applications at commercial production scale.
In July 2026, Braskem S.A. expanded its bio-based polyethylene production capacity in Brazil to serve growing Latin American demand for renewable flexible packaging films and bags with established regional distribution capabilities.
In June 2026, BASF SE partnered with a European flexible packaging converter to deploy certified compostable bio-based polymer blends for fresh produce packaging across German retail chains.
Feedstocks Covered:
• Corn-Based Feedstocks
• Sugarcane-Based Feedstocks
• Cellulose Feedstocks
• Starch Feedstocks
• Vegetable Oil Feedstocks
Polymer Types Covered:
• Biobased Polyethylene
• Biobased Polypropylene
• Polylactic Acid
• Polyhydroxyalkanoates
• Cellulose Derivatives
Packaging Formats Covered:
• Pouches
• Bags
• Sachets
• Films
• Wraps
Material Properties Covered:
• High Barrier
• Heat Sealable
• High Strength
• Moisture Resistant
• Compostable
Applications Covered:
• Food Packaging
• Beverage Packaging
• Personal Care Packaging
• Pharmaceutical Packaging
• Household Care Packaging
End Users Covered:
• Food Manufacturers
• Beverage Companies
• Pharmaceutical Companies
• Cosmetics Manufacturers
• Household Product Manufacturers
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Bio-Based Flexible Packaging Market, By Feedstock
5.1 Corn-Based Feedstocks
5.2 Sugarcane-Based Feedstocks
5.3 Cellulose Feedstocks
5.4 Starch Feedstocks
5.5 Vegetable Oil Feedstocks
6 Global Bio-Based Flexible Packaging Market, By Polymer Type
6.1 Biobased Polyethylene
6.2 Biobased Polypropylene
6.3 Polylactic Acid
6.4 Polyhydroxyalkanoates
6.5 Cellulose Derivatives
7 Global Bio-Based Flexible Packaging Market, By Packaging Format
7.1 Pouches
7.2 Bags
7.3 Sachets
7.4 Films
7.5 Wraps
8 Global Bio-Based Flexible Packaging Market, By Material Property
8.1 High Barrier
8.2 Heat Sealable
8.3 High Strength
8.4 Moisture Resistant
8.5 Compostable
9 Global Bio-Based Flexible Packaging Market, By Application
9.1 Food Packaging
9.2 Beverage Packaging
9.3 Personal Care Packaging
9.4 Pharmaceutical Packaging
9.5 Household Care Packaging
10 Global Bio-Based Flexible Packaging Market, By End User
10.1 Food Manufacturers
10.2 Beverage Companies
10.3 Pharmaceutical Companies
10.4 Cosmetics Manufacturers
10.5 Household Product Manufacturers
11 Global Bio-Based Flexible Packaging Market, By Geography
11.1 North America
11.1.1 United States
11.1.2 Canada
11.1.3 Mexico
11.2 Europe
11.2.1 United Kingdom
11.2.2 Germany
11.2.3 France
11.2.4 Italy
11.2.5 Spain
11.2.6 Netherlands
11.2.7 Belgium
11.2.8 Sweden
11.2.9 Switzerland
11.2.10 Poland
11.2.11 Rest of Europe
11.3 Asia Pacific
11.3.1 China
11.3.2 Japan
11.3.3 India
11.3.4 South Korea
11.3.5 Australia
11.3.6 Indonesia
11.3.7 Thailand
11.3.8 Malaysia
11.3.9 Singapore
11.3.10 Vietnam
11.3.11 Rest of Asia Pacific
11.4 South America
11.4.1 Brazil
11.4.2 Argentina
11.4.3 Colombia
11.4.4 Chile
11.4.5 Peru
11.4.6 Rest of South America
11.5 Rest of the World (RoW)
11.5.1 Middle East
11.5.1.1 Saudi Arabia
11.5.1.2 United Arab Emirates
11.5.1.3 Qatar
11.5.1.4 Israel
11.5.1.5 Rest of Middle East
11.5.2 Africa
11.5.2.1 South Africa
11.5.2.2 Egypt
11.5.2.3 Morocco
11.5.2.4 Rest of Africa
12 Strategic Market Intelligence
12.1 Industry Value Network and Supply Chain Assessment
12.2 White-Space and Opportunity Mapping
12.3 Product Evolution and Market Life Cycle Analysis
12.4 Channel, Distributor, and Go-to-Market Assessment
13 Industry Developments and Strategic Initiatives
13.1 Mergers and Acquisitions
13.2 Partnerships, Alliances, and Joint Ventures
13.3 New Product Launches and Certifications
13.4 Capacity Expansion and Investments
13.5 Other Strategic Initiatives
14 Company Profiles
14.1 Amcor plc
14.2 Mondi plc
14.3 Berry Global Group, Inc.
14.4 Sealed Air Corporation
14.5 BASF SE
14.6 Corbion N.V.
14.7 Celanese Corporation
14.8 Braskem S.A.
14.9 NatureWorks LLC
14.10 TotalEnergies SE
14.11 Stora Enso Oyj
14.12 Huhtamäki Oyj
14.13 UFlex Limited
14.14 Jindal Poly Films Limited
14.15 Mitsubishi Chemical Group Corporation
14.16 Toray Industries, Inc.
14.17 Kuraray Co., Ltd.
List of Tables
1 Global Bio-Based Flexible Packaging Market Outlook, By Region (2023-2034) ($MN)
2 Global Bio-Based Flexible Packaging Market Outlook, By Feedstock (2023-2034) ($MN)
3 Global Bio-Based Flexible Packaging Market Outlook, By Corn-Based Feedstocks (2023-2034) ($MN)
4 Global Bio-Based Flexible Packaging Market Outlook, By Sugarcane-Based Feedstocks (2023-2034) ($MN)
5 Global Bio-Based Flexible Packaging Market Outlook, By Cellulose Feedstocks (2023-2034) ($MN)
6 Global Bio-Based Flexible Packaging Market Outlook, By Starch Feedstocks (2023-2034) ($MN)
7 Global Bio-Based Flexible Packaging Market Outlook, By Vegetable Oil Feedstocks (2023-2034) ($MN)
8 Global Bio-Based Flexible Packaging Market Outlook, By Polymer Type (2023-2034) ($MN)
9 Global Bio-Based Flexible Packaging Market Outlook, By Biobased Polyethylene (2023-2034) ($MN)
10 Global Bio-Based Flexible Packaging Market Outlook, By Biobased Polypropylene (2023-2034) ($MN)
11 Global Bio-Based Flexible Packaging Market Outlook, By Polylactic Acid (2023-2034) ($MN)
12 Global Bio-Based Flexible Packaging Market Outlook, By Polyhydroxyalkanoates (2023-2034) ($MN)
13 Global Bio-Based Flexible Packaging Market Outlook, By Cellulose Derivatives (2023-2034) ($MN)
14 Global Bio-Based Flexible Packaging Market Outlook, By Packaging Format (2023-2034) ($MN)
15 Global Bio-Based Flexible Packaging Market Outlook, By Pouches (2023-2034) ($MN)
16 Global Bio-Based Flexible Packaging Market Outlook, By Bags (2023-2034) ($MN)
17 Global Bio-Based Flexible Packaging Market Outlook, By Sachets (2023-2034) ($MN)
18 Global Bio-Based Flexible Packaging Market Outlook, By Films (2023-2034) ($MN)
19 Global Bio-Based Flexible Packaging Market Outlook, By Wraps (2023-2034) ($MN)
20 Global Bio-Based Flexible Packaging Market Outlook, By Material Property (2023-2034) ($MN)
21 Global Bio-Based Flexible Packaging Market Outlook, By High Barrier (2023-2034) ($MN)
22 Global Bio-Based Flexible Packaging Market Outlook, By Heat Sealable (2023-2034) ($MN)
23 Global Bio-Based Flexible Packaging Market Outlook, By High Strength (2023-2034) ($MN)
24 Global Bio-Based Flexible Packaging Market Outlook, By Moisture Resistant (2023-2034) ($MN)
25 Global Bio-Based Flexible Packaging Market Outlook, By Compostable (2023-2034) ($MN)
26 Global Bio-Based Flexible Packaging Market Outlook, By Application (2023-2034) ($MN)
27 Global Bio-Based Flexible Packaging Market Outlook, By Food Packaging (2023-2034) ($MN)
28 Global Bio-Based Flexible Packaging Market Outlook, By Beverage Packaging (2023-2034) ($MN)
29 Global Bio-Based Flexible Packaging Market Outlook, By Personal Care Packaging (2023-2034) ($MN)
30 Global Bio-Based Flexible Packaging Market Outlook, By Pharmaceutical Packaging (2023-2034) ($MN)
31 Global Bio-Based Flexible Packaging Market Outlook, By Household Care Packaging (2023-2034) ($MN)
32 Global Bio-Based Flexible Packaging Market Outlook, By End User (2023-2034) ($MN)
33 Global Bio-Based Flexible Packaging Market Outlook, By Food Manufacturers (2023-2034) ($MN)
34 Global Bio-Based Flexible Packaging Market Outlook, By Beverage Companies (2023-2034) ($MN)
35 Global Bio-Based Flexible Packaging Market Outlook, By Pharmaceutical Companies (2023-2034) ($MN)
36 Global Bio-Based Flexible Packaging Market Outlook, By Cosmetics Manufacturers (2023-2034) ($MN)
37 Global Bio-Based Flexible Packaging Market Outlook, By Household Product Manufacturers (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
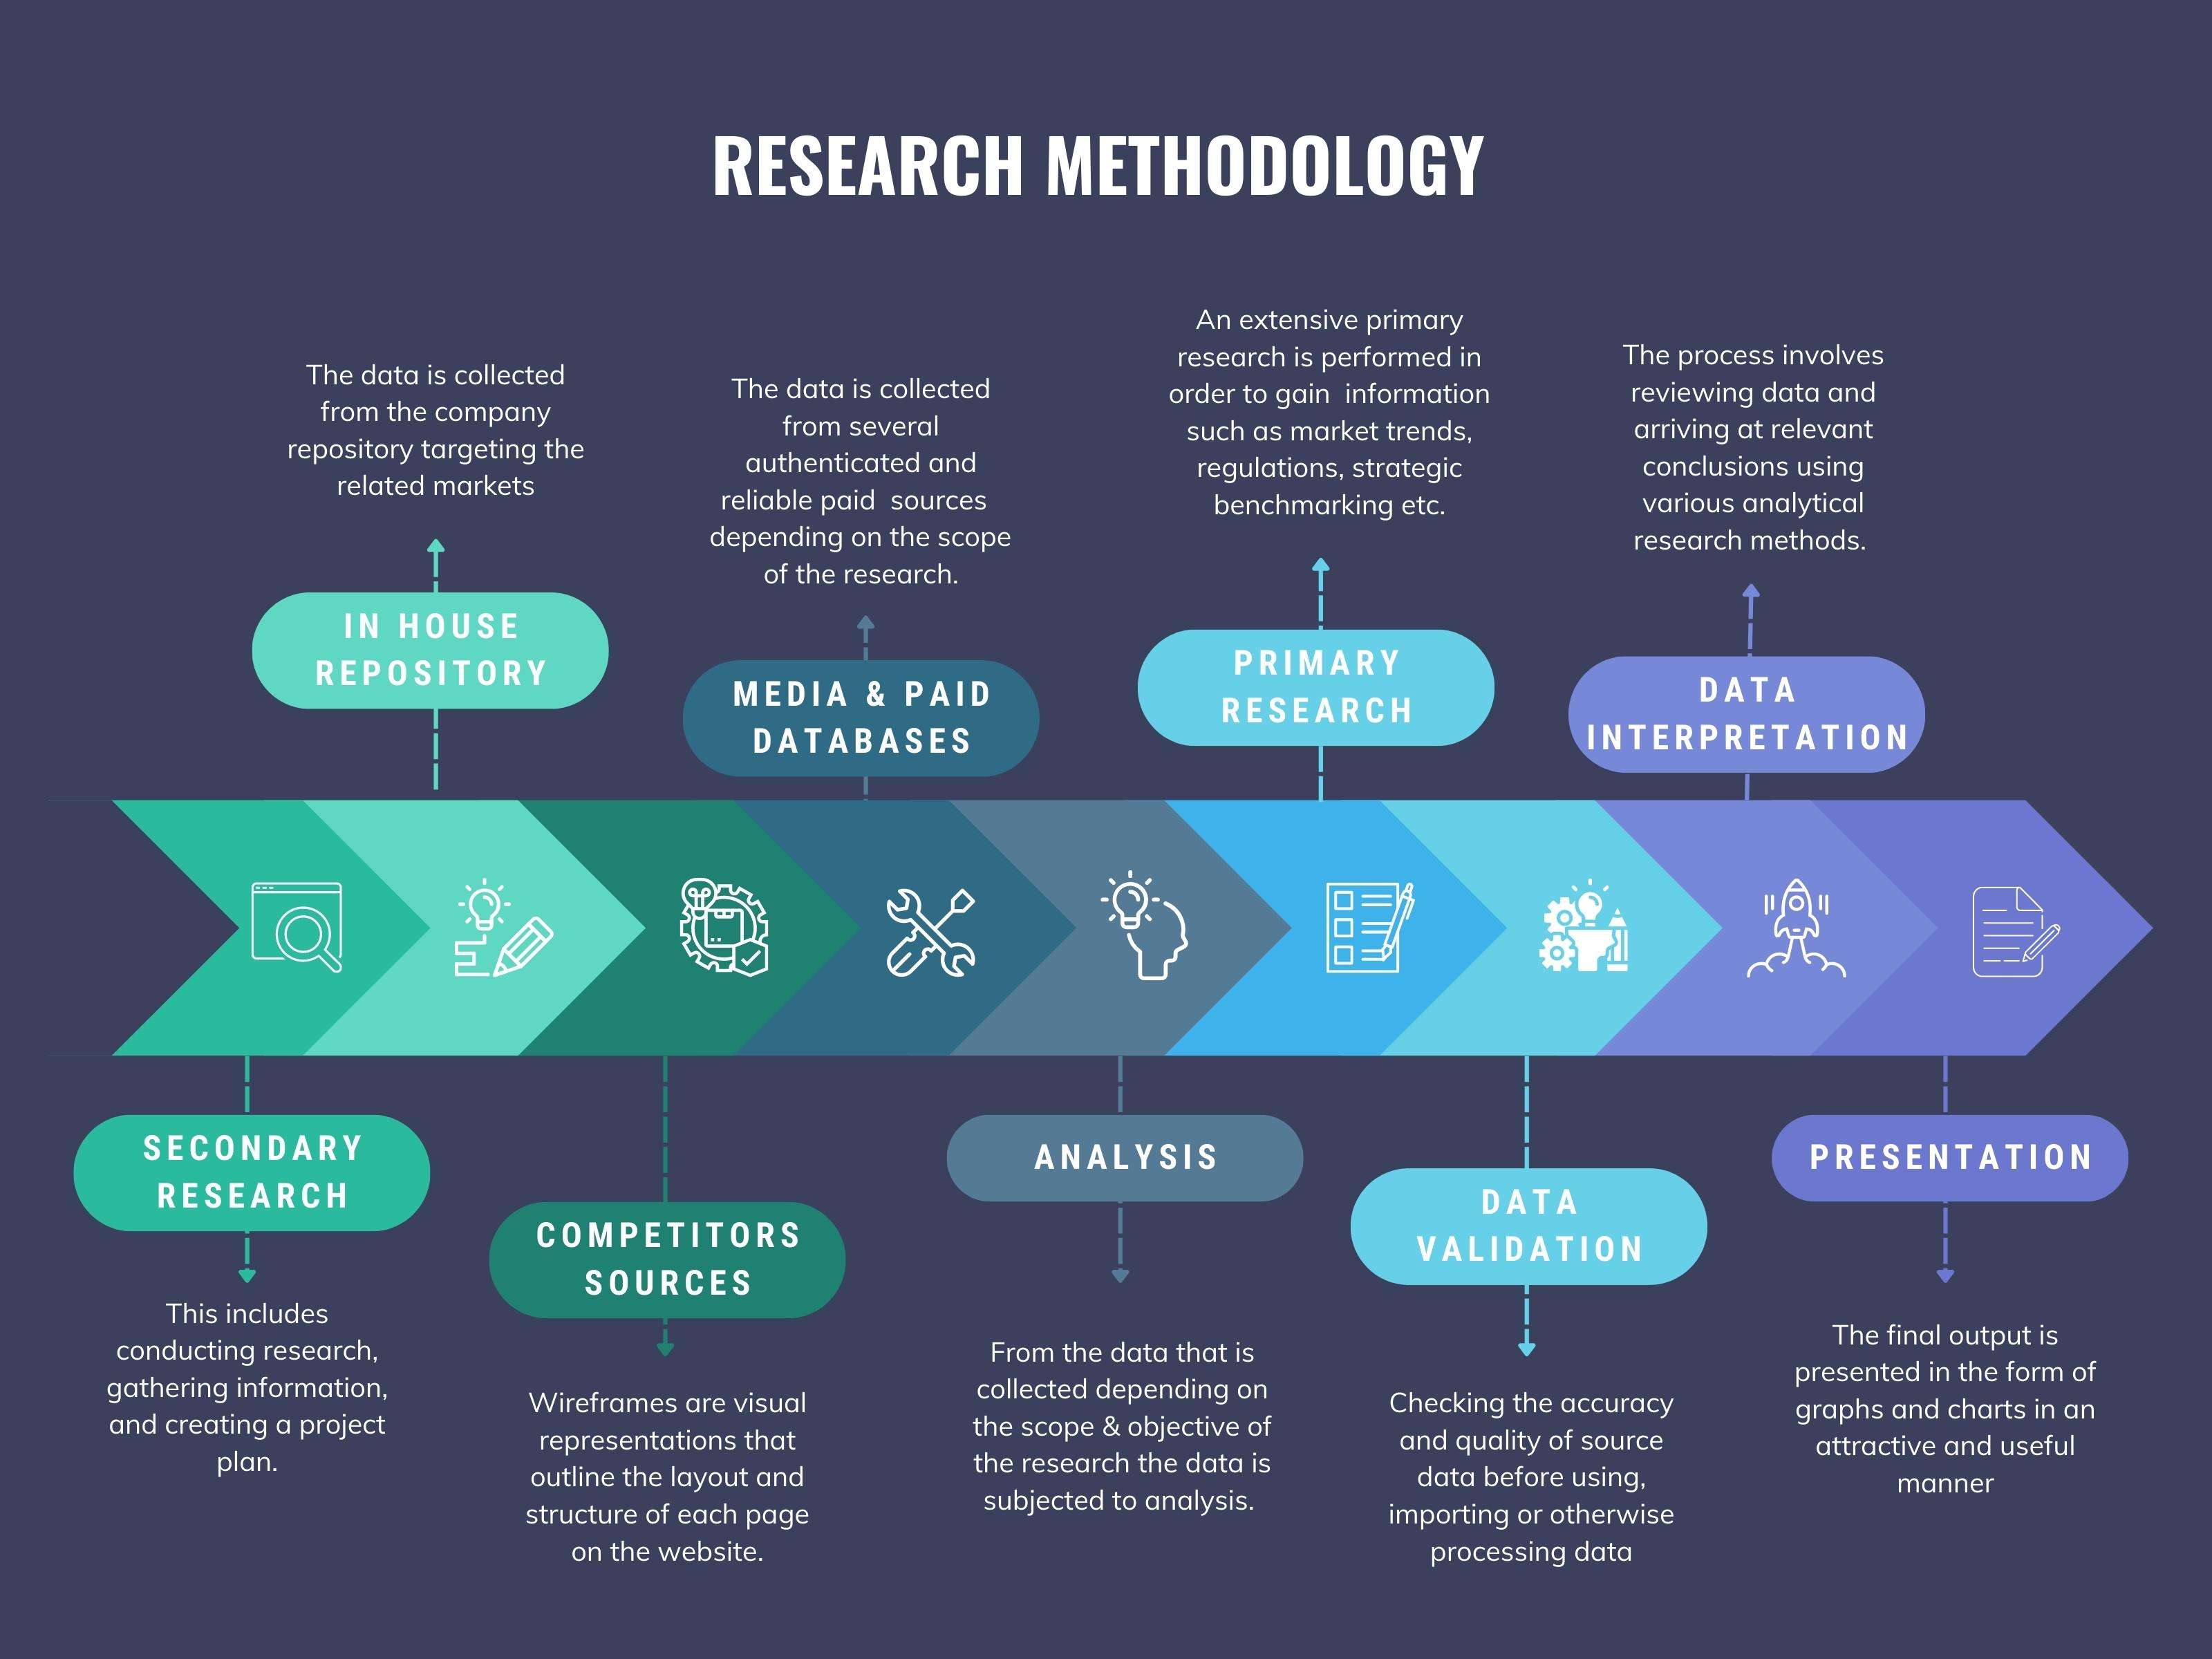
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.