Carbon Fiber Market
Carbon Fiber Market Forecasts to 2034 – Global Analysis By Precursor Type (Polyacrylonitrile (PAN), Pitch, Rayon, and Precursor Types), Product Form, Tow Size, Modulus, End-Use Industry, and By Geography
According to Stratistics MRC, the Global Carbon Fiber Market is accounted for $6.1 billion in 2026 and is expected to reach $12.5 billion by 2034 growing at a CAGR of 9.4% during the forecast period. Carbon fiber is a high-performance reinforcement material consisting of thin, strong crystalline filaments of carbon, offering exceptional strength-to-weight ratios, stiffness, and fatigue resistance. The market encompasses polyacrylonitrile (PAN), pitch, rayon, and other precursor types in product forms including continuous carbon fiber, carbon fiber tow, carbon fiber fabric, carbon fiber prepreg, chopped carbon fiber, and other forms. Carbon fiber is available in small tow and large tow configurations across standard modulus, intermediate modulus, high modulus, and ultra-high modulus grades. The market serves aerospace and defense, automotive and transportation, wind energy, sporting goods, construction and infrastructure, pressure vessels, electronics, marine, and other end-use industries.
Market Dynamics:
Driver:
Growing demand for lightweight, high-performance materials in aerospace and automotive
The increasing need for lightweight, high-strength materials in aerospace and automotive applications is a primary driver for the carbon fiber market. Aerospace manufacturers are adopting carbon fiber composites to reduce aircraft weight, improve fuel efficiency, and enhance performance. Automotive manufacturers are using carbon fiber for structural components and body panels. The expansion of electric vehicle production is creating new opportunities for carbon fiber in battery enclosures and structural components. As industries prioritize performance and efficiency, carbon fiber demand expands across all major applications.
Restraint:
High production costs and energy-intensive manufacturing
The significant cost of carbon fiber production and the energy-intensive manufacturing processes represent a major restraint for the market. Carbon fiber production requires substantial energy input, particularly for PAN precursor manufacturing and carbonization. High capital investment for production facilities limits capacity expansion. Cost competitiveness with conventional materials remains challenging. These cost and manufacturing barriers may constrain market growth, particularly in cost-sensitive automotive applications.
Opportunity:
Expansion of pressure vessel and hydrogen storage applications
The growing demand for pressure vessels and hydrogen storage applications presents significant opportunities for the carbon fiber market. Carbon fiber composites are essential for manufacturing lightweight, high-strength pressure vessels for hydrogen storage, CNG, and other industrial gases. The emerging hydrogen economy is creating substantial demand for carbon fiber pressure vessels. Growing investment in hydrogen infrastructure supports market growth. As clean energy transitions accelerate, carbon fiber applications in pressure vessels capture growing market share.
Threat:
Competition from alternative materials and recycling challenges
Intense competition from alternative materials including glass fiber composites, aluminum, and advanced high-strength steel poses significant threats to carbon fiber market growth. Glass fiber composites offer lower-cost alternatives for many applications. Aluminum and steel provide established solutions with well-developed recycling infrastructure. Carbon fiber recycling remains technically challenging and costly. This competition may limit market share, particularly in applications where cost is a primary consideration.
Covid-19 Impact:
The COVID-19 pandemic had a mixed impact on the carbon fiber market. Aerospace production slowdowns reduced demand for carbon fiber composites. However, wind energy investment continued as a strategic priority. Pressure vessel demand increased for medical oxygen and industrial gases. Post-pandemic, aerospace production recovery and continued renewable energy investment have supported market growth across multiple applications.
The Polyacrylonitrile (PAN) segment is expected to be the largest during the forecast period
The Polyacrylonitrile (PAN) segment is expected to account for the largest market share during the forecast period, driven by its dominance as the primary precursor for carbon fiber production, offering excellent mechanical properties and processability. PAN-based carbon fibers account for the vast majority of global carbon fiber production. The segment benefits from established manufacturing infrastructure and continuous process improvements. Growing demand for high-performance carbon fiber in aerospace, automotive, and wind energy supports PAN consumption. As the dominant precursor type, PAN maintains the largest precursor type segment share.
The Wind Energy segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Wind Energy segment is predicted to witness the highest growth rate, fueled by the rapid expansion of global wind power capacity and the increasing use of carbon fiber in large wind turbine blades. Carbon fiber is used in spar caps and structural components of large turbine blades to reduce weight and increase stiffness. The segment benefits from aggressive renewable energy targets and wind power capacity expansion. Increasing turbine size drives carbon fiber demand. As wind energy capacity continues growing, this end-use industry delivers the fastest segment growth.
Region with largest share:
During the forecast period, the Asia-Pacific region is expected to hold the largest market share, supported by concentrated carbon fiber production, expanding wind energy capacity, and growing aerospace and automotive manufacturing across China, Japan, and South Korea. China leads global carbon fiber production and consumption, driving substantial market volume. The region's large and growing wind energy industry creates significant demand. Growing aerospace and automotive production supports demand. With concentrated manufacturing and growing end-use markets, Asia Pacific maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by continued wind energy expansion, rising aerospace and automotive production, and growing investment in advanced materials across the region. The region's large and growing wind energy industry creates substantial demand for carbon fiber. Government renewable energy targets support wind energy expansion. Growing aerospace and automotive production drives carbon fiber adoption. As industrial activity and clean energy investment expand, Asia Pacific delivers the fastest carbon fiber market growth globally.
Key players in the market
Some of the key players in Carbon Fiber Market include Toray Industries, Inc., Teijin Limited, Mitsubishi Chemical Group Corporation, SGL Carbon SE, Hexcel Corporation, Solvay S.A., Nippon Carbon Co., Ltd., Formosa Plastics Corporation, Hyosung Advanced Materials Corporation, Zhongfu Shenying Carbon Fiber Co., Ltd., Jiangcheng Carbon Fiber Co., Ltd., DowAksa Advanced Composites Holdings B.V., Carbon Composites, Inc., Kureha Corporation, and Weihai Guangwei Composites Co., Ltd.
Key Developments:
In September 2026, Hexcel Corporation announced the commercial qualification and production expansion of its fast-curing HexPly® M901 prepreg at its Salt Lake City facility and introduced its HexWeb® Vented Flex-Core® honeycomb composites at CAMX 2026.
In July 2026, Nippon Carbon Co., Ltd. expanded global allocations of its high-purity carbon fiber soft felt and thermal insulation composite lines to satisfy rising demand from high-temperature semiconductor crystal-growing and energy storage systems.
In July 2026, Teijin Limited developed a circular thermosetting carbon fiber reinforced plastic (CFRP) featuring heat-activated self-healing capabilities and mild chemical recyclability, extending product lifecycles for aerospace and automotive structural components.
In July 2026, Mitsubishi Chemical Corporation expanded its Xlink Tech portfolio by launching two new carbon fiber prepreg series (HT and HS), engineered with proprietary resin chemistries to enhance impact resistance and damage tolerance in high-modulus CFRP.
Precursor Types Covered:
• Polyacrylonitrile (PAN)
• Pitch
• Rayon
• Other Precursor Types
Product Forms Covered:
• Continuous Carbon Fiber
• Carbon Fiber Tow
• Carbon Fiber Fabric
• Carbon Fiber Prepreg
• Chopped Carbon Fiber
• Other Product Forms
Tow Sizes Covered:
• Small Tow
• Large Tow
Modulus Covered:
• Standard Modulus
• Intermediate Modulus
• High Modulus
• Ultra-High Modulus
End-Use Industries Covered:
• Aerospace and Defense
• Automotive and Transportation
• Wind Energy
• Sporting Goods
• Construction and Infrastructure
• Pressure Vessels
• Electronics
• Marine
• Other End-Use Industries
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Carbon Fiber Market, By Precursor Type
5.1 Polyacrylonitrile (PAN)
5.2 Pitch
5.3 Rayon
5.4 Other Precursor Types
6 Global Carbon Fiber Market, By Product Form
6.1 Continuous Carbon Fiber
6.2 Carbon Fiber Tow
6.3 Carbon Fiber Fabric
6.4 Carbon Fiber Prepreg
6.5 Chopped Carbon Fiber
6.6 Other Product Forms
7 Global Carbon Fiber Market, By Tow Size
7.1 Small Tow
7.2 Large Tow
8 Global Carbon Fiber Market, By Modulus
8.1 Standard Modulus
8.2 Intermediate Modulus
8.3 High Modulus
8.4 Ultra-High Modulus
9 Global Carbon Fiber Market, By End-Use Industry
9.1 Aerospace and Defense
9.2 Automotive and Transportation
9.3 Wind Energy
9.4 Sporting Goods
9.5 Construction and Infrastructure
9.6 Pressure Vessels
9.7 Electronics
9.8 Marine
9.9 Other End-Use Industries
10 Global Carbon Fiber Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Toray Industries, Inc.
13.2 Teijin Limited
13.3 Mitsubishi Chemical Group Corporation
13.4 SGL Carbon SE
13.5 Hexcel Corporation
13.6 Solvay S.A.
13.7 Nippon Carbon Co., Ltd.
13.8 Formosa Plastics Corporation
13.9 Hyosung Advanced Materials Corporation
13.10 Zhongfu Shenying Carbon Fiber Co., Ltd.
13.11 Jiangcheng Carbon Fiber Co., Ltd.
13.12 DowAksa Advanced Composites Holdings B.V.
13.13 Carbon Composites, Inc.
13.14 Kureha Corporation
13.15 Weihai Guangwei Composites Co., Ltd.
List of Tables
1 Global Carbon Fiber Market Outlook, By Region (2023–2034) ($MN)
2 Global Carbon Fiber Market Outlook, By Precursor Type (2023–2034) ($MN)
3 Global Carbon Fiber Market Outlook, By Polyacrylonitrile (PAN) (2023–2034) ($MN)
4 Global Carbon Fiber Market Outlook, By Pitch (2023–2034) ($MN)
5 Global Carbon Fiber Market Outlook, By Rayon (2023–2034) ($MN)
6 Global Carbon Fiber Market Outlook, By Other Precursor Types (2023–2034) ($MN)
7 Global Carbon Fiber Market Outlook, By Product Form (2023–2034) ($MN)
8 Global Carbon Fiber Market Outlook, By Continuous Carbon Fiber (2023–2034) ($MN)
9 Global Carbon Fiber Market Outlook, By Carbon Fiber Tow (2023–2034) ($MN)
10 Global Carbon Fiber Market Outlook, By Carbon Fiber Fabric (2023–2034) ($MN)
11 Global Carbon Fiber Market Outlook, By Carbon Fiber Prepreg (2023–2034) ($MN)
12 Global Carbon Fiber Market Outlook, By Chopped Carbon Fiber (2023–2034) ($MN)
13 Global Carbon Fiber Market Outlook, By Other Product Forms (2023–2034) ($MN)
14 Global Carbon Fiber Market Outlook, By Tow Size (2023–2034) ($MN)
15 Global Carbon Fiber Market Outlook, By Small Tow (2023–2034) ($MN)
16 Global Carbon Fiber Market Outlook, By Large Tow (2023–2034) ($MN)
17 Global Carbon Fiber Market Outlook, By Modulus (2023–2034) ($MN)
18 Global Carbon Fiber Market Outlook, By Standard Modulus (2023–2034) ($MN)
19 Global Carbon Fiber Market Outlook, By Intermediate Modulus (2023–2034) ($MN)
20 Global Carbon Fiber Market Outlook, By High Modulus (2023–2034) ($MN)
21 Global Carbon Fiber Market Outlook, By Ultra-High Modulus (2023–2034) ($MN)
22 Global Carbon Fiber Market Outlook, By End-Use Industry (2023–2034) ($MN)
23 Global Carbon Fiber Market Outlook, By Aerospace and Defense (2023–2034) ($MN)
24 Global Carbon Fiber Market Outlook, By Automotive and Transportation (2023–2034) ($MN)
25 Global Carbon Fiber Market Outlook, By Wind Energy (2023–2034) ($MN)
26 Global Carbon Fiber Market Outlook, By Sporting Goods (2023–2034) ($MN)
27 Global Carbon Fiber Market Outlook, By Construction and Infrastructure (2023–2034) ($MN)
28 Global Carbon Fiber Market Outlook, By Pressure Vessels (2023–2034) ($MN)
29 Global Carbon Fiber Market Outlook, By Electronics (2023–2034) ($MN)
30 Global Carbon Fiber Market Outlook, By Marine (2023–2034) ($MN)
31 Global Carbon Fiber Market Outlook, By Other End-Use Industries (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
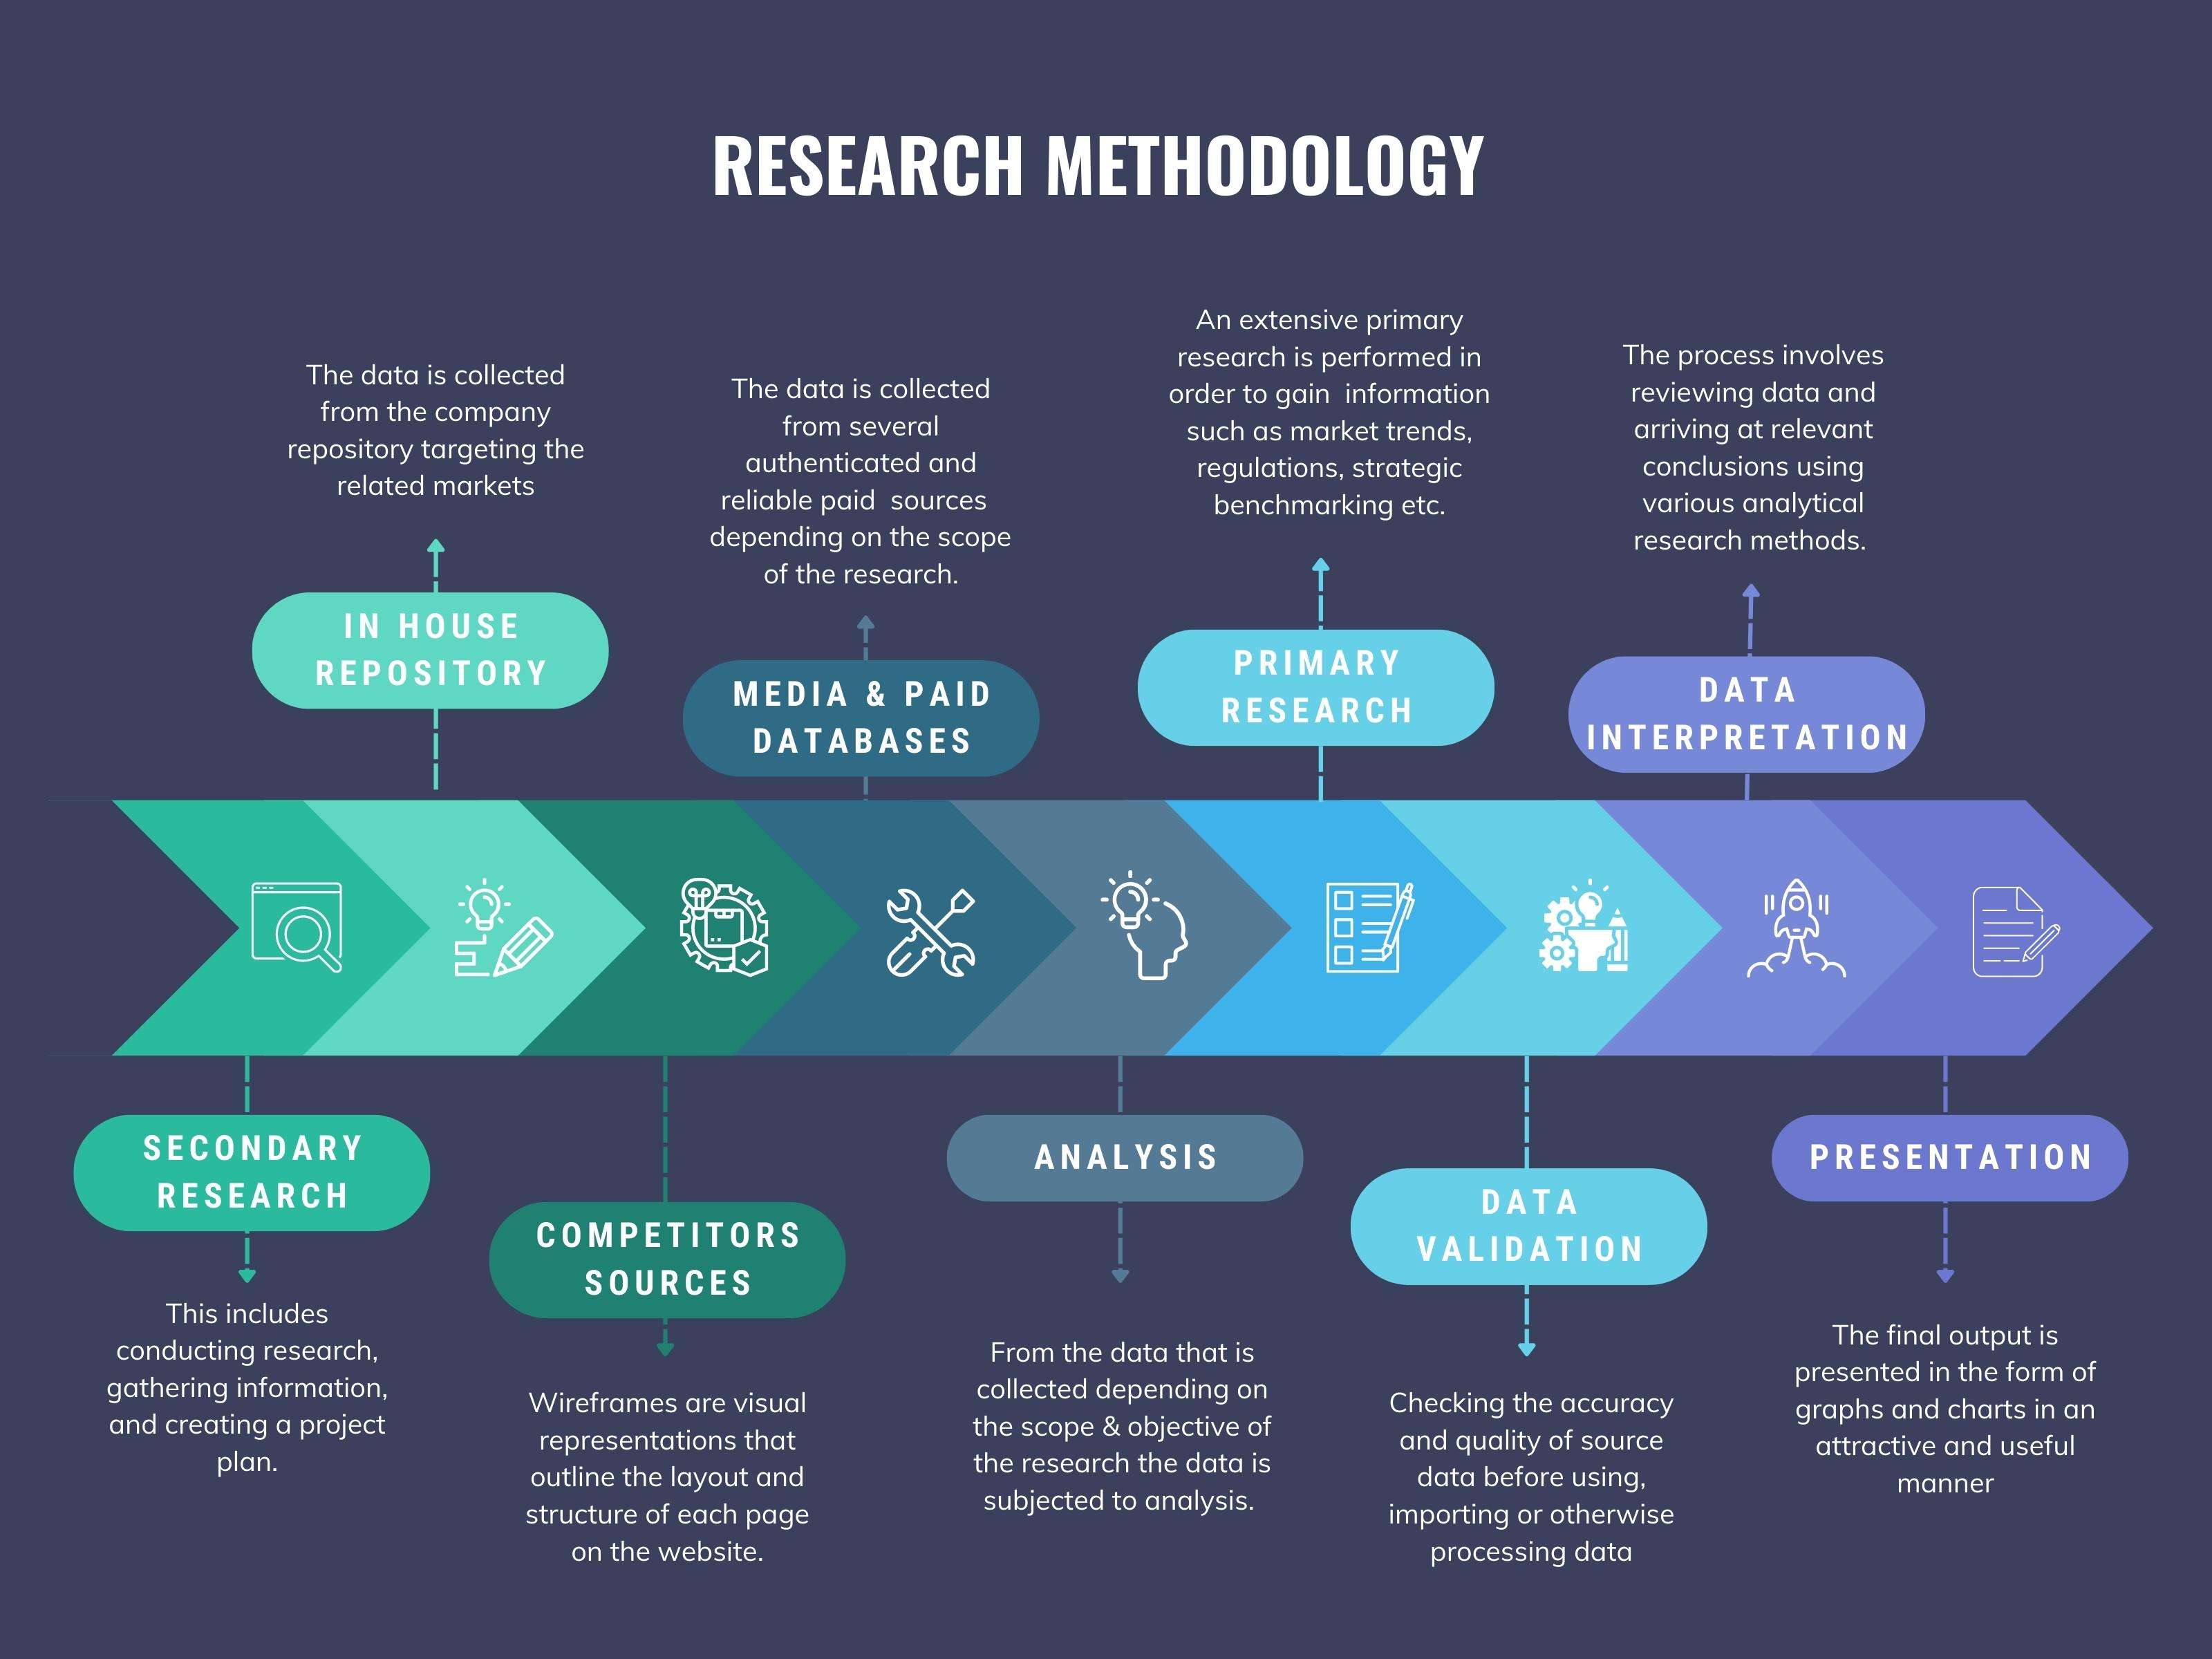
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.