Digital Banking And Neobanking Market
Digital Banking & Neobanking Market Forecasts to 2034 - Global Analysis By Service Type (Payments & Money Transfers, Savings & Checking Accounts, Lending & Credit Services, Wealth Management & Investment Services and Insurance & Protection Services), Deployment Model, User Type, Technology, Channel and By Geography
According to Stratistics MRC, the Global Digital Banking & Neobanking Market is accounted for $29.6 billion in 2026 and is expected to reach $199.1 billion by 2034 growing at a CAGR of 26.9% during the forecast period. Digital Banking & Neobanking encompasses modern financial services accessed mainly through online and mobile platforms rather than conventional branch networks. It includes digital payments, account management, mobile applications, automated services, virtual assistance, and remote banking support. Neobanks typically use digital-first operating models to streamline customer onboarding, deliver personalized services, and introduce technology-enabled financial solutions. The market integrates cloud infrastructure, artificial intelligence, APIs, automation, and data analytics to enhance banking accessibility, simplify customer interactions, strengthen service delivery, and improve operational efficiency across increasingly digital financial ecosystems.
According to the World Bank, 76% of adults worldwide had an account with a bank, other financial institution, or mobile money provider in 2021, compared with 68% in 2017 and 51% in 2011.
Market Dynamics:
Driver:
Rising smartphone and internet penetration
Increasing smartphone ownership and internet accessibility are significantly supporting the Digital Banking & Neobanking Market. Customers are progressively relying on mobile devices for payments, fund transfers, account monitoring, savings, and various banking functions. Affordable smartphones and expanding high-speed connectivity allow financial institutions to deliver banking services without depending heavily on physical branches. Improved digital access can also bring financial services to underserved communities while encouraging mobile-centric banking experiences. Greater familiarity with online financial platforms continues to strengthen consumer demand for convenient, accessible, and digitally delivered banking solutions.
Restraint:
Cybersecurity and data privacy concerns
Concerns surrounding cybersecurity and protection of customer data can limit the expansion of the Digital Banking & Neobanking Market. Digital banking systems manage confidential information such as identities, financial accounts, payment credentials, and transaction histories, increasing exposure to cyber threats. Incidents involving breaches, phishing, fraud, malware, or unauthorized access may cause financial damage and reduce consumer confidence. Banks and neobanks therefore require ongoing spending on encryption, security systems, fraud detection, and compliance measures. Such obligations raise operating complexity and expenses while potentially discouraging security-conscious customers from adopting digital banking.
Opportunity:
Expansion into underserved and unbanked markets
Reaching underserved and unbanked populations offers considerable growth opportunities for the Digital Banking & Neobanking Market. Digital banking platforms can serve customers in areas where traditional branches and financial infrastructure remain limited. Mobile banking applications, digital wallets, remote registration, and electronic payment solutions can broaden access to accounts, savings, transfers, and financial products. Neobanks can leverage technology to overcome geographical and service limitations while attracting previously excluded users. Expanding internet availability and smartphone adoption can further enable affordable digital financial services across emerging economies and communities.
Threat:
Intense competition from fintech and traditional banks
Competition from established banks and fintech providers can create significant pressure on the Digital Banking & Neobanking Market. Traditional financial institutions are strengthening their digital platforms, mobile applications, payment services, and online banking capabilities, while fintech firms introduce focused and innovative financial solutions. Such competition can raise customer acquisition expenses and increase pressure to improve pricing, products, technology, and service quality. Neobanks need continuous investment in digital infrastructure, security, customer experience, and product development. Maintaining customer loyalty can become more difficult as digital financial services evolve rapidly.
Covid-19 Impact:
COVID-19 significantly accelerated Digital Banking & Neobanking adoption by limiting physical branch visits and increasing reliance on remote financial services. During lockdowns and social distancing measures, customers increasingly used mobile applications, digital payments, online account services, and contactless transactions. Financial institutions responded by expanding remote onboarding, digital customer support, automated services, and electronic payment capabilities. The pandemic encouraged banks and neobanks to advance digital transformation more rapidly, increase technology investments, and establish banking models designed to provide continuous, accessible, flexible, and resilient financial services.
The payments & money transfers segment is expected to be the largest during the forecast period
The payments & money transfers segment is expected to account for the largest market share during the forecast period, supported by its central role in routine financial transactions. Individuals and businesses frequently use digital platforms for person-to-person transfers, bill settlement, merchant payments, remittances, and daily purchases. Mobile banking applications and digital wallets provide convenient channels for completing transactions quickly and efficiently. Growing consumer acceptance of cashless and contactless payment methods further reinforces the importance of payment and transfer capabilities, making them a fundamental component of modern digital banking services.
The mobile devices segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the mobile devices segment is predicted to witness the highest growth rate, supported by the expanding use of smartphones for financial activities. Users increasingly depend on mobile applications for payments, money transfers, account monitoring, credit services, investments, and other banking functions. Mobile platforms can provide personalized experiences, biometric security, real-time alerts, and digital assistance. Wider smartphone usage and stronger connectivity are extending access to digital financial services, while consumer demand for flexible, convenient, and anytime banking continues to accelerate adoption of mobile channels.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share due to its advanced financial ecosystem and widespread acceptance of digital financial services. The region benefits from established banks, fintech enterprises, payment platforms, and technology companies that support continuous innovation. Consumers increasingly rely on mobile banking, online transactions, digital wallets, and other electronic financial solutions. Robust technology infrastructure, extensive internet access, developed financial markets, and increasing preference for convenient digital interactions collectively strengthen North America’s significant role within the digital banking landscape.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR as digital transformation continues across the region. Rising smartphone usage, broader internet availability, and increasing acceptance of mobile payments are accelerating consumer adoption of digital financial services. Developing economies are also witnessing expanding fintech ecosystems and investment in digital banking infrastructure. Growing digital payment networks, technology advancement, and customer preference for accessible and convenient financial solutions are supporting strong opportunities for digital banks and neobanking providers throughout Asia Pacific.
Key players in the market
Some of the key players in Digital Banking & Neobanking Market include Nubank, WeBank, MYBank, KakaoBank, K-Bank, Revolut, TNEX, Cake, C6 Bank, Klarna Bank, Maya Bank, Tandem Bank, Toss Bank, SBI Sumishin Net Bank, bunq, BoursoBank, Sony Bank and Jupiter.
Key Developments:
In September 2026, Nubank will start offering financial products in the U.S. through bank partners, it announced in a securities filing. Nu is partnering with FDIC-insured Lead Bank to provide deposit accounts with a 3.50% yield, as well as free international money transfers and a no-fee credit card with 1.5% cashback.
In September 2024, MYbank has introduced its AI-enabled system (Cuckoo System) for small and micro-sized enterprise (SME) money management. The system forecasts the cash flow of SMEs across various industries, assisting bank-affiliated investment management companies in more effectively anticipating the timing of SMEs’ subscriptions and redemptions of investment products and helping SMEs generate reasonable returns from their idle cash.
Service Types Covered:
• Payments & Money Transfers
• Savings & Checking Accounts
• Lending & Credit Services
• Wealth Management & Investment Services
• Insurance & Protection Services
Deployment Models Covered:
• Cloud-Based Platforms
• On-Premise Solutions
User Types Covered:
• Retail Customers
• SMEs (Small & Medium Enterprises)
• Large Enterprises
Technologies Covered:
• Core Technologies
• Delivery Technologies
Channels Covered:
• Mobile Devices
• Desktop & Web Access
• Branchless Banking Interfaces
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Digital Banking & Neobanking Market, By Service Type
5.1 Payments & Money Transfers
5.2 Savings & Checking Accounts
5.3 Lending & Credit Services
5.4 Wealth Management & Investment Services
5.5 Insurance & Protection Services
6 Global Digital Banking & Neobanking Market, By Deployment Model
6.1 Cloud-Based Platforms
6.2 On-Premise Solutions
7 Global Digital Banking & Neobanking Market, By User Type
7.1 Retail Customers
7.2 SMEs (Small & Medium Enterprises)
7.3 Large Enterprises
8 Global Digital Banking & Neobanking Market, By Technology
8.1 Core Technologies
8.1.1 AI & Chatbot Integration
8.1.2 Blockchain & Distributed Ledger Solutions
8.1.3 API Banking & Open Banking Infrastructure
8.2 Delivery Technologies
8.2.1 Mobile Banking Applications
8.2.2 Web-Based Platforms
9 Global Digital Banking & Neobanking Market, By Channel
9.1 Mobile Devices
9.2 Desktop & Web Access
9.3 Branchless Banking Interfaces
10 Global Digital Banking & Neobanking Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Nubank
13.2 WeBank
13.3 MYBank
13.4 KakaoBank
13.5 K-Bank
13.6 Revolut
13.7 TNEX
13.8 Cake
13.9 C6 Bank
13.10 Klarna Bank
13.11 Maya Bank
13.12 Tandem Bank
13.13 Toss Bank
13.14 SBI Sumishin Net Bank
13.15 bunq
13.16 BoursoBank
13.17 Sony Bank
13.18 Jupiter
List of Tables
1 Global Digital Banking & Neobanking Market Outlook, By Region (2023-2034) ($MN)
2 Global Digital Banking & Neobanking Market Outlook, By Service Type (2023-2034) ($MN)
3 Global Digital Banking & Neobanking Market Outlook, By Payments & Money Transfers (2023-2034) ($MN)
4 Global Digital Banking & Neobanking Market Outlook, By Savings & Checking Accounts (2023-2034) ($MN)
5 Global Digital Banking & Neobanking Market Outlook, By Lending & Credit Services (2023-2034) ($MN)
6 Global Digital Banking & Neobanking Market Outlook, By Wealth Management & Investment Services (2023-2034) ($MN)
7 Global Digital Banking & Neobanking Market Outlook, By Insurance & Protection Services (2023-2034) ($MN)
8 Global Digital Banking & Neobanking Market Outlook, By Deployment Model (2023-2034) ($MN)
9 Global Digital Banking & Neobanking Market Outlook, By Cloud-Based Platforms (2023-2034) ($MN)
10 Global Digital Banking & Neobanking Market Outlook, By On-Premise Solutions (2023-2034) ($MN)
11 Global Digital Banking & Neobanking Market Outlook, By User Type (2023-2034) ($MN)
12 Global Digital Banking & Neobanking Market Outlook, By Retail Customers (2023-2034) ($MN)
13 Global Digital Banking & Neobanking Market Outlook, By SMEs (Small & Medium Enterprises) (2023-2034) ($MN)
14 Global Digital Banking & Neobanking Market Outlook, By Large Enterprises (2023-2034) ($MN)
15 Global Digital Banking & Neobanking Market Outlook, By Technology (2023-2034) ($MN)
16 Global Digital Banking & Neobanking Market Outlook, By Core Technologies (2023-2034) ($MN)
17 Global Digital Banking & Neobanking Market Outlook, By AI & Chatbot Integration (2023-2034) ($MN)
18 Global Digital Banking & Neobanking Market Outlook, By Blockchain & Distributed Ledger Solutions (2023-2034) ($MN)
19 Global Digital Banking & Neobanking Market Outlook, By API Banking & Open Banking Infrastructure (2023-2034) ($MN)
20 Global Digital Banking & Neobanking Market Outlook, By Delivery Technologies (2023-2034) ($MN)
21 Global Digital Banking & Neobanking Market Outlook, By Mobile Banking Applications (2023-2034) ($MN)
22 Global Digital Banking & Neobanking Market Outlook, By Web-Based Platforms (2023-2034) ($MN)
23 Global Digital Banking & Neobanking Market Outlook, By Channel (2023-2034) ($MN)
24 Global Digital Banking & Neobanking Market Outlook, By Mobile Devices (2023-2034) ($MN)
25 Global Digital Banking & Neobanking Market Outlook, By Desktop & Web Access (2023-2034) ($MN)
26 Global Digital Banking & Neobanking Market Outlook, By Branchless Banking Interfaces (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
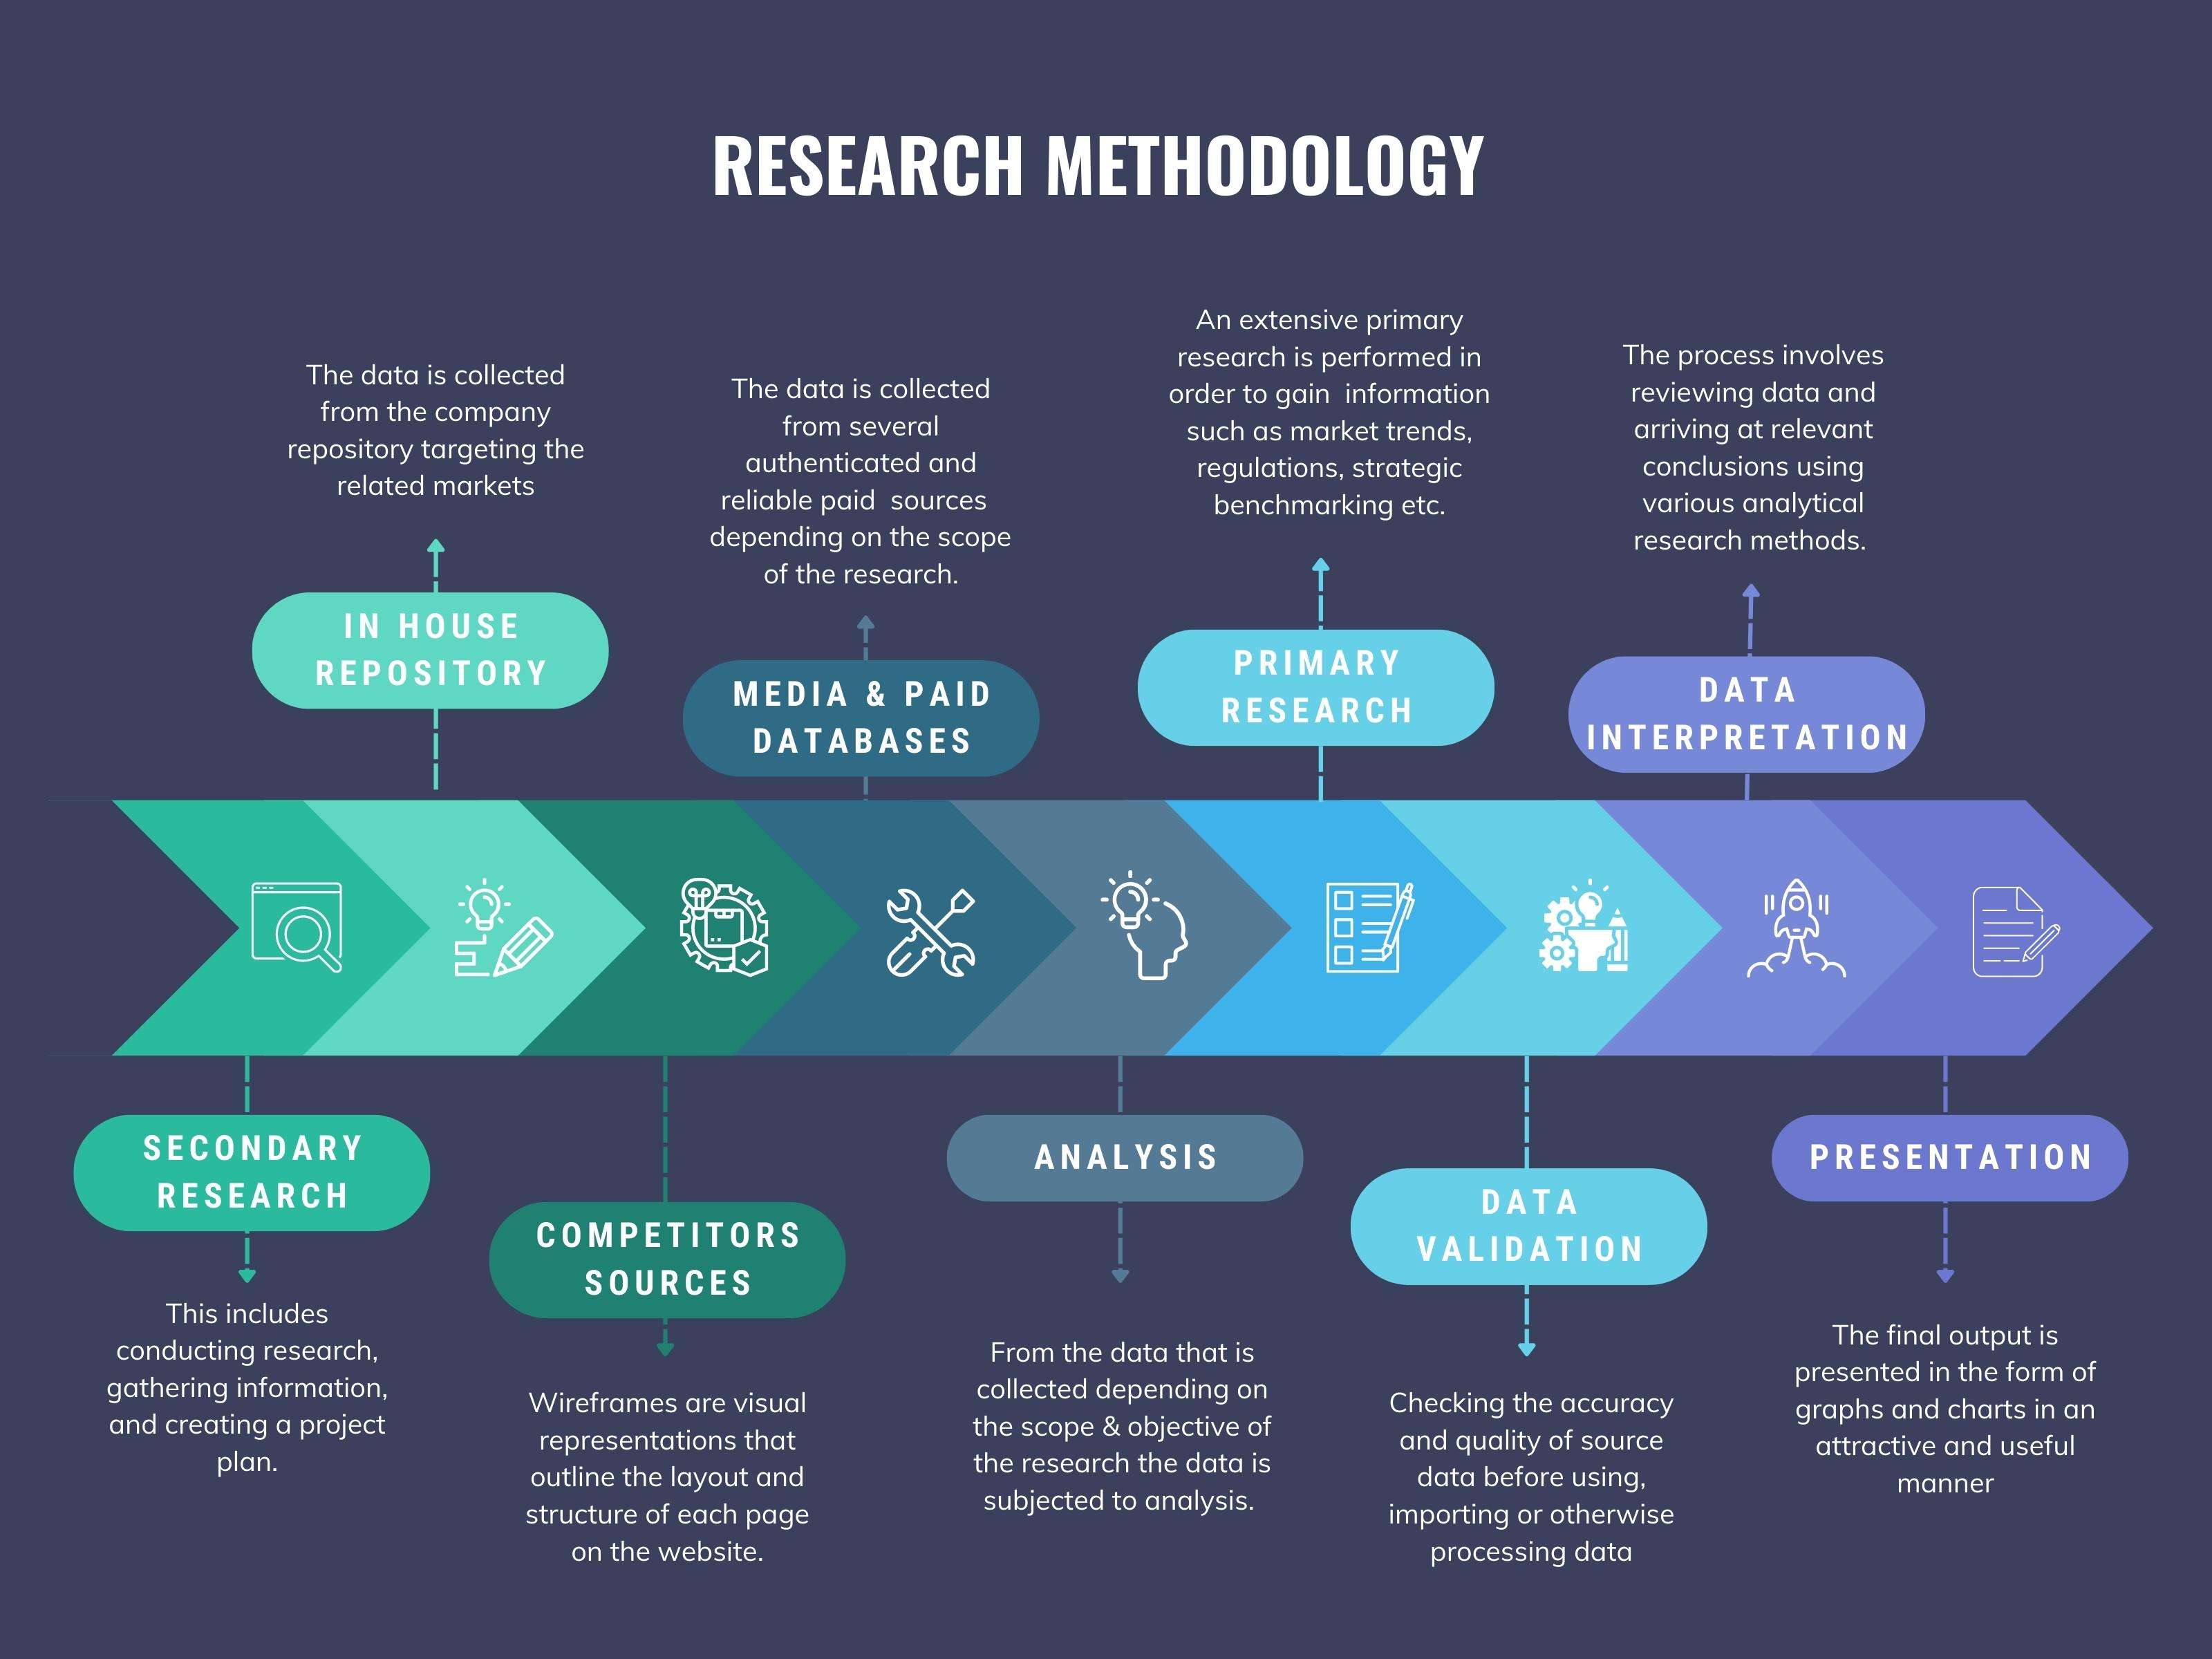
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.