Global Battery Competitive Intelligence
Global Battery Competitive Intelligence 2026 – Strategic Analysis of Leading Companies, Technology Trends, Manufacturing, Innovation, and Competitive Landscape
The Global Battery Competitive Intelligence study provides an in-depth assessment of the companies, technologies, intellectual property, manufacturing capabilities, supply chains, partnerships, investments, and emerging challengers shaping the global battery ecosystem.
Unlike conventional market studies centered primarily on market sizing and forecasts, this Competitive Intelligence study focuses on the competitive dynamics behind the industry: which companies possess differentiated battery technologies, how their capabilities compare, where they are investing, which research partnerships and intellectual property positions strengthen their competitive advantage, and which emerging companies could disrupt the existing landscape.
The study benchmarks established battery manufacturers, automotive companies, energy-storage companies, battery-material suppliers, component manufacturers, technology developers, startups, and university spin-offs across their technology portfolios, R&D capabilities, manufacturing readiness, patent strength, commercialization progress, geographic presence, partnerships, and strategic initiatives.
Particular attention is given to lithium-ion batteries, lithium iron phosphate (LFP), nickel manganese cobalt (NMC), nickel cobalt aluminum (NCA), sodium-ion batteries, solid-state batteries, lithium-metal batteries, lithium-sulfur batteries, silicon-anode batteries, lithium-titanate batteries, and other emerging battery platforms.
Competitive Intelligence Highlights
The study is designed to answer critical competitive questions including:
• Which companies currently possess the strongest battery technology and manufacturing capabilities?
• Which companies lead individual battery chemistry and technology platforms?
• How do established battery manufacturers compare with vertically integrated energy companies, automotive companies, technology specialists, and startups?
• Which battery technologies are closest to commercial-scale deployment?
• Which companies possess the strongest patent and intellectual property positions across battery chemistries, materials, components, and manufacturing technologies?
• Where are the major manufacturing, critical-material, component, and supply-chain dependencies?
• Which companies have the strongest capabilities across battery materials, cells, modules, packs, battery management systems, and recycling?
• Which automotive companies, energy-storage companies, universities, and research institutions are forming strategically important commercial partnerships?
• Where is venture capital and corporate investment flowing within the global battery ecosystem?
• Which startups and university spin-offs are emerging as potential competitive challengers?
• What battery technology, application, manufacturing, and supply-chain white spaces remain underserved?
• Which companies are developing differentiated approaches to energy density, charging speed, safety, cycle life, cost reduction, and sustainability?
• Where are the strongest opportunities for partnerships, licensing, investment, and acquisitions?
Key Competitive Intelligence Deliverables
• Company Benchmarking: Side-by-side assessment of leading companies across battery technologies, R&D, IP, manufacturing, commercialization, geographic reach, supply-chain capabilities, and strategic positioning.
• Technology Leadership Mapping: Identification of leading companies across lithium-ion, LFP, NMC, NCA, sodium-ion, solid-state, lithium-metal, lithium-sulfur, silicon-anode, lithium-titanate, and other emerging battery technology platforms.
• Patent & Innovation Intelligence: Assessment of patent activity, IP strength, technology development trajectories, and innovation leadership across battery chemistries, materials, components, manufacturing processes, and battery-management technologies.
• Manufacturing & Supply Chain Intelligence: Evaluation of cell and battery manufacturing capabilities, production readiness, critical material dependencies, battery-material suppliers, component ecosystems, manufacturing scale-up, recycling capabilities, and supply-chain constraints.
• Partnership Intelligence: Mapping of automotive OEM partnerships, material-supply agreements, technology collaborations, university collaborations, licensing relationships, joint ventures, government-supported programs, and strategic alliances.
• Investment Intelligence: Analysis of venture funding, corporate investments, gigafactory and manufacturing expansion initiatives, technology-development investments, strategic acquisitions, and other capital flows influencing the competitive environment.
• Startup & Disruption Tracking: Identification of emerging battery startups, university spin-offs, next-generation battery developers, advanced-material companies, recycling innovators, disruptive technologies, and companies to watch.
• Strategic White Space Analysis: Identification of underserved battery technologies, applications, materials, manufacturing processes, supply-chain opportunities, recycling opportunities, and commercialization gaps, including potential areas for investment, partnerships, licensing, or market entry.
How This Study Differs from a Market Forecast Report
A conventional Market Forecast report primarily addresses how large the battery market is, how fast it is growing, and which battery technologies, applications, and regions are driving that growth.
The Competitive Intelligence study addresses a different set of strategic questions: who is competing, what capabilities they possess, why certain companies are better positioned than others, where competitors are investing, which technologies and intellectual property could provide competitive advantages, and where future competitive opportunities and threats are emerging.
The study is therefore intended for organizations requiring deeper competitor, technology, partnership, investment, manufacturing, supply-chain, intellectual property, and strategic intelligence beyond conventional market sizing and forecasting.
Key Questions Answered In The Report
The Global Concentrated Solar Power Market is majorly driven by the rising environmentalconcerns and growing integration in hybrid power plants.
The > 100 MW segment is growing at the highest CAGR due to the increasing investmenttoward construction of large solar power plants along with decline in CSP associated capitalexpenditure.
The Europe dominated with a significant market share owing to the growing need to producecontinuous renewable power to support rising economic activities.
Asia Pacific market is growing at the highest CAGR owing to the growing in installations ofconcentrating solar power (CSP) plants.
Key players in Concentrated Solar Power Market include Aalborg CSP A/S, Abengoa Solar, S.A,ACWA Power, Archimede Solar Energy, Baysolar CSP, Chiyoda Corporation, Cobra Energia,Esolar, Inc, Frenell GmbH, General Electric, GlassPoint Solar, Hayward Tyler, Nexans, NovatecSolar, Shams Power, Shouhang, Siemens AG, Solarreserve, LLC, Soltigua, Torresol Energy,Brightsource Energy, Inc, and TSK Flagsol Engineering GmbH.
Table of Contents
1 Executive Summary
1.1 Battery Competitive Landscape Snapshot
1.2 Leading Companies & Emerging Challengers
1.3 Key Technology Leaders
1.4 Critical Competitive Developments
1.5 Investment & Partnership Highlights
1.6 Strategic Opportunities & White Spaces
2 Research Framework
2.1 Research Objectives
2.2 Competitive Intelligence Methodology
2.3 Primary & Secondary Data Sources
2.4 Scope of the Study
2.5 Company Selection & Benchmarking Criteria
2.6 Assumptions & Limitations
3 Battery Industry & Ecosystem Intelligence
3.1 Battery Industry Structure
3.2 Battery Value Chain & Ecosystem
3.3 Evolution from Research to Commercial Deployment
3.4 Commercialization Drivers
3.5 Commercialization Barriers & Industry Challenges
3.6 Critical Material & Supply Dependencies
3.7 Government Battery Programs & Funding Environment
3.8 University, National Laboratory & Corporate Research Ecosystem
3.9 Standards & Regulatory Considerations
4 Battery Competitive Landscape
4.1 Competitive Intensity & Market Concentration
4.2 Competitive Positioning by Battery Capability
4.3 Competitive Leadership by Battery Category
4.4 Competitive Leadership by Application
4.5 Pure-Play Battery Companies vs Diversified Technology & Automotive Leaders
4.6 Competitive Differentiation Strategies
4.7 Barriers to Entry & Competitive Moats
4.8 Competitive Positioning Matrix
5 Company & Technology Benchmarking
5.1 Battery Technology Portfolio Comparison
5.2 Electric Vehicle Battery Capabilities
5.3 Energy Storage Battery Capabilities
5.4 Consumer Electronics Battery Capabilities
5.5 Battery Cell, Module & Pack Manufacturing Capabilities
5.6 Intellectual Property Strength
5.7 R&D Intensity & Research Pipeline
5.8 University & Research Institution Partnerships
5.9 Technology Readiness by Company
5.10 Commercialization Stage by Company
5.11 Geographic & Operational Footprint
5.12 Customer & Application Focus
5.13 Competitive Strength/Weakness Benchmarking
6 Battery Manufacturing & Supply Chain Intelligence
6.1 Battery Cell, Module & Pack Manufacturing Ecosystem
6.2 Manufacturing Footprint of Leading Companies
6.3 Production Capacity & Scale-Up Readiness
6.4 Critical Raw Materials & Precursors
6.5 Cathodes, Anodes, Electrolytes & Separators
6.6 Battery Material Processing Requirements
6.7 Equipment & Instrumentation Ecosystem
6.8 Key Supplier Relationships
6.9 Vertical Integration Strategies
6.10 Supply Chain Bottlenecks & Vulnerabilities
6.11 Localization & Domestic Manufacturing Initiatives
7 Battery Technology & Innovation Intelligence
7.1 Battery Technology Roadmap
7.2 Lithium-Ion Batteries
7.3 Lithium Iron Phosphate Batteries
7.4 Nickel Manganese Cobalt Batteries
7.5 Nickel Cobalt Aluminum Batteries
7.6 Sodium-Ion Batteries
7.7 Solid-State Batteries
7.8 Lithium-Sulfur & Other Emerging Battery Technologies
7.9 Battery Recycling & Second-Life Technologies
7.10 Battery Performance Benchmarking
7.11 Patent Landscape & IP Leadership
7.12 Patent Filing Trends by Technology
7.13 Technology Readiness Assessment
7.14 Commercialization Readiness Assessment
8 Corporate Strategy, Investment & Partnership Intelligence
8.1 Mergers & Acquisitions
8.2 Strategic Partnerships & Alliances
8.3 University–Industry Collaborations
8.4 Joint Ventures
8.5 Licensing & Technology Transfer Agreements
8.6 Government-Funded Battery Programs
8.7 Venture Capital & Private Investment
8.8 Corporate R&D Investments
8.9 Manufacturing Expansion Plans
8.10 Geographic Expansion Strategies
8.11 Strategic Direction of Leading Companies
9 Regional Battery Innovation Hubs
9.1 North America
9.1.1 United States
9.1.2 Canada
9.2 Europe
9.2.1 Germany
9.2.2 United Kingdom
9.2.3 France
9.2.4 Netherlands
9.2.5 Sweden
9.3 Asia Pacific
9.3.1 China
9.3.2 Japan
9.3.3 South Korea
9.3.4 India
9.3.5 Australia
9.4 Emerging Battery Research & Commercialization Hubs
10 Startups, Spin-Offs & Emerging Challengers
10.1 High-Growth Battery Companies
10.2 University Spin-Off Landscape
10.3 Startups by Battery Technology
10.4 Startups by Application Area
10.5 Venture Funding Landscape
10.6 Most-Funded Emerging Companies
10.7 Recently Funded Companies
10.8 Disruptive Technology Developers
10.9 Emerging Companies to Watch
11 Competitive Outlook & Strategic White Spaces
11.1 Technology White Space Analysis
11.2 Application White Space Analysis
11.3 Unmet Battery Performance Requirements
11.4 Commercialization Gaps
11.5 Emerging Competitive Threats
11.6 High-Potential Commercial Opportunities
11.7 Potential Future Market Leaders
11.8 Partnership & Collaboration Opportunities
11.9 Potential Consolidation & Acquisition Opportunities
11.10 Strategic Recommendations
12 Company Profiles
12.1 CATL
12.2 BYD Company Limited
12.3 LG Energy Solution
12.4 Panasonic Energy Co., Ltd.
12.5 Samsung SDI Co., Ltd.
12.6 SK On Co., Ltd.
12.7 CALB Co., Ltd.
12.8 EVE Energy Co., Ltd.
12.9 Gotion High-Tech Co., Ltd.
12.10 Envision AESC
12.11 Northvolt
12.12 SVOLT Energy Technology Co., Ltd.
12.13 Sunwoda Electronic Co., Ltd.
12.14 Farasis Energy
12.15 Amara Raja Energy & Mobility Limited
12.16 Exide Industries Limited
12.17 QuantumScape Corporation
12.18 Solid Power, Inc.
12.19 Factorial Energy
12.20 ProLogium Technology Co., Ltd.
12.21 FREYR Battery
12.22 Eos Energy Enterprises, Inc.
12.23 EnerSys
12.24 Clarios International Inc.
12.25 SES AI Corporation
13 List of Tables
Table 1 Battery Competitive Landscape Overview
Table 2 Leading Companies by Battery Technology
Table 3 Company Technology Portfolio Benchmarking
Table 4 Electric Vehicle Battery Capability Comparison
Table 5 Energy Storage Battery Capability Comparison
Table 6 Consumer Electronics Battery Capability Comparison
Table 7 Battery Cell, Module & Pack Manufacturing Capability Comparison
Table 8 Technology Readiness by Company
Table 9 Commercialization Readiness by Company
Table 10 Geographic Presence of Leading Companies
Table 11 Manufacturing & Research Facilities
Table 12 Patent Portfolio Comparison
Table 13 Key University–Industry Collaborations
Table 14 Recent Strategic Partnerships
Table 15 Recent M&A & Investment Activity
Table 16 Leading Battery Startups
Table 17 Venture Funding Comparison
Table 18 Competitive Benchmarking Matrix
Table 19 Companies to Watch
Table 20 Strategic White Space & Opportunity Matrix
14 List of Figures
Fig 1 Battery Industry Ecosystem
Fig 2 Battery Value Chain
Fig 3 Competitive Positioning Map
Fig 4 Battery Technology Roadmap
Fig 5 Battery Technology vs Application Mapping
Fig 6 Global Battery R&D & Manufacturing Footprint
Fig 7 Technology Readiness Landscape
Fig 8 Patent Filing Trend by Battery Technology
Fig 9 Leading Patent Holders
Fig 10 University–Industry Collaboration Network
Fig 11 Strategic Partnership Network
Fig 12 Venture Investment Trend
Fig 13 Regional Battery Innovation Hubs
Fig 14 Recent M&A, Funding & Partnership Timeline
Fig 15 Competitive White Space Map
List of Figures
RESEARCH METHODOLOGY
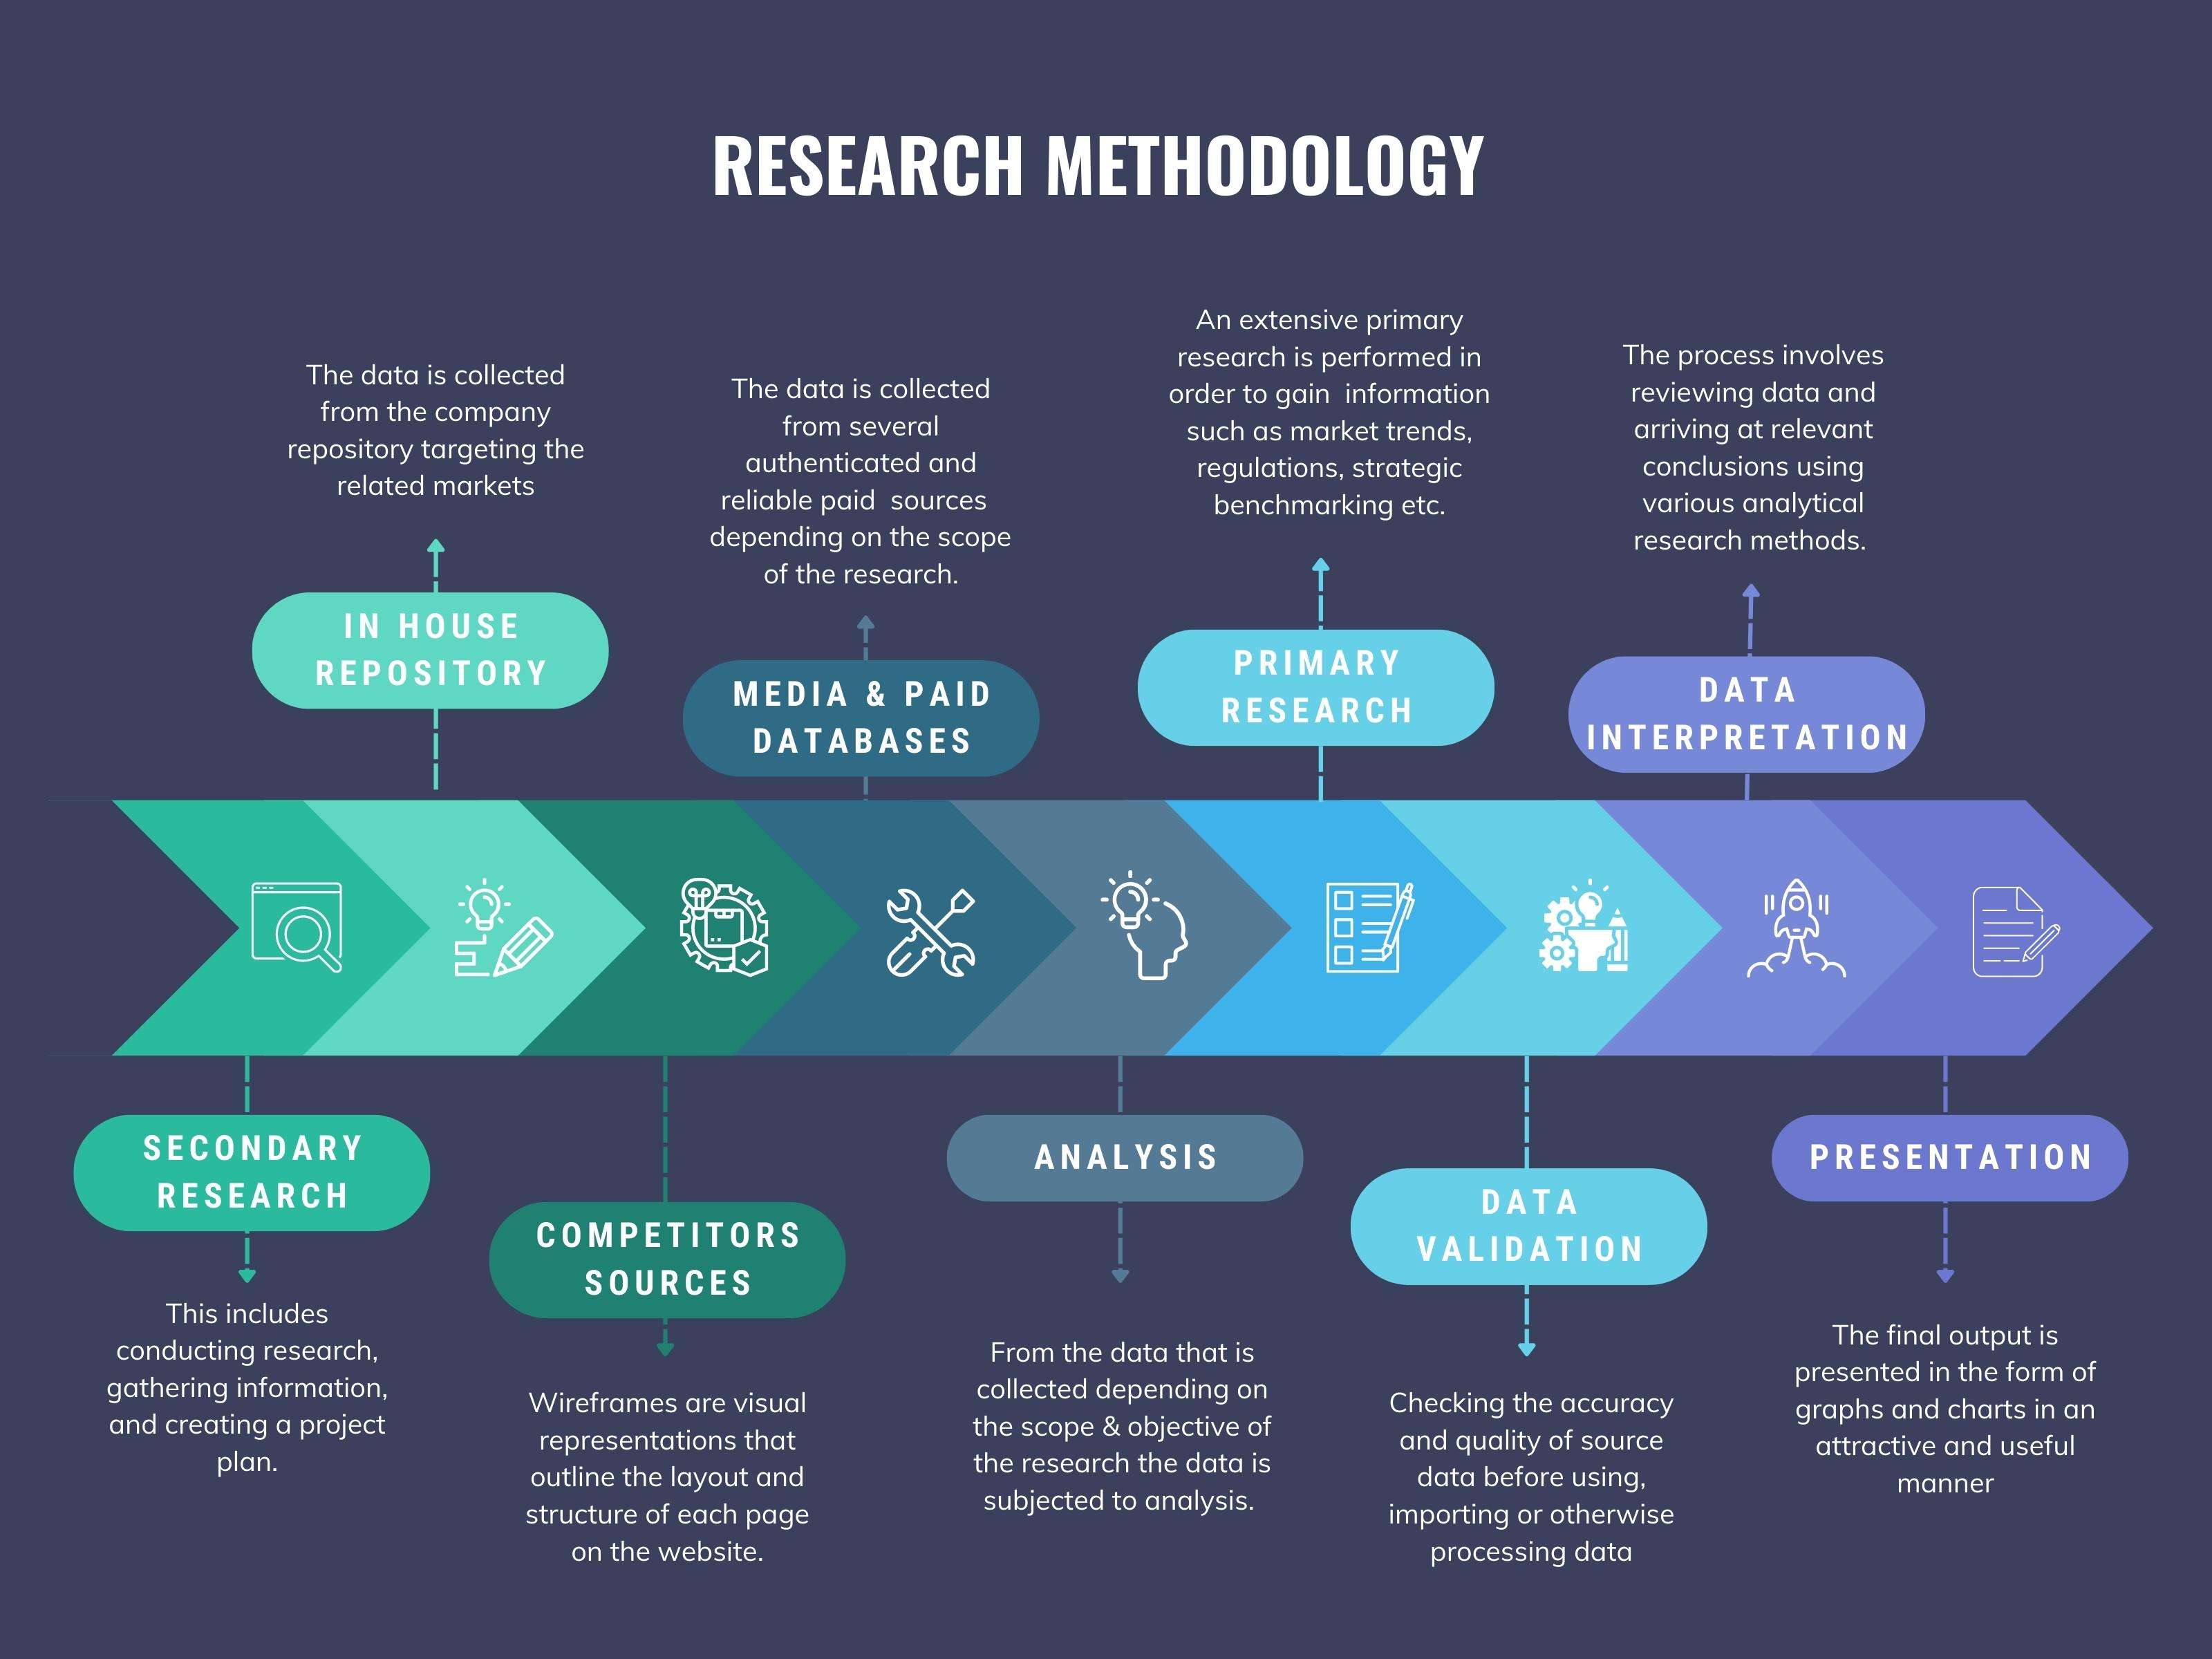
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.