Global Software Defined Vehicle Competitive Intelligence
Global Software-Defined Vehicle Competitive Intelligence 2026 – Strategic Analysis of Leading Companies, Technology Trends, Manufacturing, Innovation, and Competitive Landscape
The Global Software-Defined Vehicle Competitive Intelligence study provides an in-depth assessment of the companies, technologies, intellectual property, software capabilities, vehicle architectures, partnerships, investments, and emerging challengers shaping the software-defined vehicle ecosystem.
Unlike conventional market studies centered primarily on market sizing and forecasts, this Competitive Intelligence study focuses on the competitive dynamics behind the industry: which companies possess differentiated software-defined vehicle technologies, how their capabilities compare, where they are investing, which automotive and technology partnerships strengthen their competitive advantage, and which emerging companies could disrupt the existing landscape.
The study benchmarks automotive OEMs, Tier 1 suppliers, semiconductor companies, automotive software providers, cloud companies, AI companies, cybersecurity companies, connectivity providers, startups, and technology spin-offs across their software-defined vehicle portfolios, R&D capabilities, software platforms, vehicle architectures, patent strength, commercialization progress, geographic presence, partnerships, and strategic initiatives.
Particular attention is given to vehicle operating systems, centralized computing, zonal architectures, domain controllers, automotive middleware, vehicle-to-cloud platforms, OTA software updates, connected vehicle platforms, AI-enabled vehicle software, digital cockpits, autonomous driving software, cybersecurity, vehicle data platforms, and software-based vehicle functions.
Competitive Intelligence Highlights
The study is designed to answer critical competitive questions including:
• Which companies currently possess the strongest software-defined vehicle capabilities?
• Which companies lead individual software-defined vehicle technology platforms?
• How do automotive OEMs compare with Tier 1 suppliers, technology companies, and software startups?
• Which software-defined vehicle technologies are closest to commercial-scale deployment?
• Which companies possess the strongest patent and intellectual property positions?
• Where are the major software, semiconductor, cloud, connectivity, data, and cybersecurity dependencies?
• Which companies are leading in vehicle operating systems, centralized computing, zonal architectures, middleware, and OTA platforms?
• Which companies have the strongest capabilities across connected vehicles, autonomous driving, digital cockpits, vehicle personalization, and software-enabled services?
• Which automotive OEMs, technology companies, and research institutions are forming strategically important partnerships?
• Where is venture capital and corporate investment flowing within the software-defined vehicle ecosystem?
• Which startups and technology spin-offs are emerging as potential competitive challengers?
• What software-defined vehicle technologies and applications remain underserved?
• Where are the strongest opportunities for partnerships, licensing, investment, and acquisitions?
Key Competitive Intelligence Deliverables
• Company Benchmarking: Side-by-side assessment of leading companies across software-defined vehicle technologies, R&D, IP, software platforms, vehicle architectures, commercialization, geographic reach, partnerships, and strategic positioning.
• Technology Leadership Mapping: Identification of leading companies across vehicle operating systems, centralized computing, zonal architectures, domain controllers, middleware, OTA platforms, vehicle-to-cloud systems, AI software, digital cockpits, cybersecurity, and vehicle data platforms.
• Application Leadership Mapping: Assessment of leading companies across connected vehicles, autonomous driving, digital cockpits, personalization, predictive maintenance, vehicle energy management, fleet management, and software-enabled services.
• Patent & Innovation Intelligence: Assessment of patent activity, IP strength, software architectures, vehicle computing, AI systems, cybersecurity, connectivity, and innovation leadership.
• Software Platform Intelligence: Evaluation of operating systems, middleware, cloud integration, APIs, developer ecosystems, data platforms, AI integration, OTA capabilities, cybersecurity, and software deployment architectures.
• Vehicle Architecture & Manufacturing Intelligence: Evaluation of centralized computing, zonal architectures, electronic control systems, semiconductor requirements, vehicle integration, software-hardware co-design, manufacturing readiness, and scale-up constraints.
• Partnership Intelligence: Mapping of OEM-software partnerships, semiconductor alliances, cloud collaborations, Tier 1 relationships, university collaborations, joint ventures, licensing relationships, and government-supported programs.
• Investment Intelligence: Analysis of venture funding, corporate investments, software platform investments, acquisitions, technology expansions, and other capital flows influencing the competitive environment.
• Startup & Disruption Tracking: Identification of emerging software-defined vehicle challengers, automotive software startups, AI companies, university spin-offs, and disruptive vehicle technology platforms.
• Strategic White Space Analysis: Identification of underserved software-defined vehicle technologies, vehicle functions, applications, commercialization gaps, and potential areas for investment, partnerships, licensing, acquisitions, or market entry.
How This Study Differs from a Market Forecast Report
A conventional Market Forecast report primarily addresses how large the Software-Defined Vehicle market is, how fast it is growing, and which segments and regions are driving that growth.
The Competitive Intelligence study addresses a different set of strategic questions: who is competing, what software-defined vehicle capabilities they possess, how their software and electronic architectures differ, where competitors are investing, which technologies and intellectual property could provide competitive advantages, and where future competitive opportunities and threats are emerging.
The study is therefore intended for organizations requiring deeper competitor, technology, application, partnership, investment, intellectual property, commercialization, and strategic intelligence beyond conventional market sizing and forecasting.
Table of Contents
1 Executive Summary
1.1 Competitive Landscape Snapshot
1.2 Leading Companies & Emerging Challengers
1.3 Key Technology Leaders
1.4 Critical Competitive Developments
1.5 Investment & Partnership Highlights
1.6 Strategic Opportunities & White Spaces
2 Research Framework
2.1 Research Objectives
2.2 Competitive Intelligence Methodology
2.3 Primary & Secondary Data Sources
2.4 Scope of the Study
2.5 Company Selection & Benchmarking Criteria
2.6 Assumptions & Limitations
3 Software-Defined Vehicle Industry & Ecosystem Intelligence
3.1 Software-Defined Vehicle Industry Structure
3.2 Software-Defined Vehicle Value Chain & Ecosystem
3.3 Evolution from Hardware-Centric Vehicles to Software-Defined Architectures
3.4 Software-Defined Vehicle Adoption Drivers
3.5 Software-Defined Vehicle Adoption Barriers & Industry Challenges
3.6 Critical Software, Computing & Connectivity Dependencies
3.7 Government Software-Defined Vehicle Programs & Funding Environment
3.8 University, Research Laboratory & Corporate Software Ecosystem
3.9 Standards & Regulatory Considerations
4 Software-Defined Vehicle Competitive Landscape
4.1 Competitive Intensity & Market Concentration
4.2 Competitive Positioning by Software-Defined Vehicle Capability
4.3 Competitive Leadership by Software Technology
4.4 Competitive Leadership by Application
4.5 Pure-Play Software-Defined Vehicle Companies vs Diversified Automotive Technology Leaders
4.6 Competitive Differentiation Strategies
4.7 Barriers to Entry & Competitive Moats
4.8 Competitive Positioning Matrix
5 Company & Technology Benchmarking
5.1 Software-Defined Vehicle Portfolio Comparison
5.2 Vehicle Operating System Capabilities
5.3 Automotive Cloud & Data Platform Capabilities
5.4 Over-the-Air Update Capabilities
5.5 In-Vehicle Software & Application Capabilities
5.6 Centralized Compute & Software Architecture Capabilities
5.7 Intellectual Property Strength
5.8 R&D Intensity & Research Pipeline
5.9 University & Research Institution Partnerships
5.10 Technology Readiness by Company
5.11 Commercialization Stage by Company
5.12 Geographic & Operational Footprint
5.13 Customer & Application Focus
5.14 Competitive Strength/Weakness Benchmarking
6 Software-Defined Vehicle Manufacturing & Supply Chain Intelligence
6.1 Software-Defined Vehicle Development Ecosystem
6.2 Software & Computing Infrastructure Footprint of Leading Companies
6.3 Deployment Capacity & Scale-Up Readiness
6.4 Critical Automotive Computing Hardware & Semiconductors
6.5 Connectivity, Cloud & Data Infrastructure
6.6 Software Development, Integration & Deployment Requirements
6.7 Vehicle Electronics & Testing Infrastructure Ecosystem
6.8 Key Supplier Relationships
6.9 Vertical Integration Strategies
6.10 Software & Electronics Supply Chain Bottlenecks & Vulnerabilities
6.11 Localization & Domestic Software & Electronics Initiatives
7 Software-Defined Vehicle Technology & Innovation Intelligence
7.1 Software-Defined Vehicle Technology Roadmap
7.2 Vehicle Operating Systems
7.3 Automotive Cloud Platforms
7.4 Over-the-Air Software Updates
7.5 In-Vehicle Applications & Digital Cockpit Software
7.6 Centralized & Zonal Software Architectures
7.7 AI-Enabled Vehicle Software
7.8 Vehicle-to-Cloud & Connected Vehicle Platforms
7.9 Emerging Software-Defined Vehicle Platforms
7.10 Software Performance Benchmarking
7.11 Patent Landscape & IP Leadership
7.12 Patent Filing Trends by Technology
7.13 Technology Readiness Assessment
7.14 Commercialization Readiness Assessment
8 Corporate Strategy, Investment & Partnership Intelligence
8.1 Mergers & Acquisitions
8.2 Strategic Partnerships & Alliances
8.3 University–Industry Collaborations
8.4 Joint Ventures
8.5 Licensing & Technology Transfer Agreements
8.6 Government-Funded Software-Defined Vehicle Programs
8.7 Venture Capital & Private Investment
8.8 Corporate R&D Investments
8.9 Software Platform & Computing Infrastructure Expansion Plans
8.10 Geographic Expansion Strategies
8.11 Strategic Direction of Leading Companies
9 Regional Software-Defined Vehicle Innovation Hubs
9.1 North America
9.1.1 United States
9.1.2 Canada
9.2 Europe
9.2.1 Germany
9.2.2 United Kingdom
9.2.3 France
9.2.4 Netherlands
9.2.5 Switzerland
9.3 Asia Pacific
9.3.1 China
9.3.2 Japan
9.3.3 South Korea
9.3.4 India
9.3.5 Australia
9.4 Emerging Software-Defined Vehicle Research & Commercialization Hubs
10 Startups, Spin-Offs & Emerging Challengers
10.1 High-Growth Software-Defined Vehicle Companies
10.2 University Spin-Off Landscape
10.3 Startups by Software-Defined Vehicle Technology
10.4 Startups by Application Area
10.5 Venture Funding Landscape
10.6 Most-Funded Emerging Companies
10.7 Recently Funded Companies
10.8 Disruptive Software-Defined Vehicle Technology Developers
10.9 Emerging Companies to Watch
11 Competitive Outlook & Strategic White Spaces
11.1 Technology White Space Analysis
11.2 Application White Space Analysis
11.3 Unmet Software-Defined Vehicle Performance Requirements
11.4 Commercialization Gaps
11.5 Emerging Competitive Threats
11.6 High-Potential Commercial Opportunities
11.7 Potential Future Market Leaders
11.8 Partnership & Collaboration Opportunities
11.9 Potential Consolidation & Acquisition Opportunities
11.10 Strategic Recommendations
12 Company Profiles
12.1 Tesla, Inc.
12.2 Volkswagen AG
12.3 Mercedes-Benz Group AG
12.4 BMW AG
12.5 Toyota Motor Corporation
12.6 General Motors Company
12.7 Ford Motor Company
12.8 Hyundai Motor Company
12.9 Stellantis N.V.
12.10 Renault Group
12.11 Volvo Car AB
12.12 Aptiv PLC
12.13 Robert Bosch GmbH
12.14 Continental AG
12.15 ZF Friedrichshafen AG
12.16 NVIDIA Corporation
12.17 Qualcomm Incorporated
12.18 Elektrobit Automotive GmbH
12.19 Harman International Industries, Incorporated
12.20 BlackBerry Limited
12.21 Wind River Systems, Inc.
12.22 KPIT Technologies Limited
12.23 Tata Technologies Limited
12.24 Sonatus, Inc.
12.25 Elektrobit Automotive GmbH
13 List of Tables
Table 1 Software-Defined Vehicle Competitive Landscape Overview
Table 2 Leading Companies by Software-Defined Vehicle Technology
Table 3 Company Technology Portfolio Benchmarking
Table 4 Vehicle Operating System Capability Comparison
Table 5 Automotive Cloud & Data Platform Capability Comparison
Table 6 Over-the-Air Update Capability Comparison
Table 7 In-Vehicle Software & Application Capability Comparison
Table 8 Technology Readiness by Company
Table 9 Commercialization Readiness by Company
Table 10 Geographic Presence of Leading Companies
Table 11 Software & Computing Infrastructure Facilities
Table 12 Patent Portfolio Comparison
Table 13 Key University–Industry Collaborations
Table 14 Recent Strategic Partnerships
Table 15 Recent M&A & Investment Activity
Table 16 Leading Software-Defined Vehicle Startups
Table 17 Venture Funding Comparison
Table 18 Competitive Benchmarking Matrix
Table 19 Companies to Watch
Table 20 Strategic White Space & Opportunity Matrix
14 List of Figures
Fig 1 Software-Defined Vehicle Industry Ecosystem
Fig 2 Software-Defined Vehicle Value Chain
Fig 3 Competitive Positioning Map
Fig 4 Software-Defined Vehicle Technology Roadmap
Fig 5 Software-Defined Vehicle Technology vs Application Mapping
Fig 6 Global Software-Defined Vehicle R&D & Deployment Footprint
Fig 7 Technology Readiness Landscape
Fig 8 Patent Filing Trend by Software-Defined Vehicle Technology
Fig 9 Leading Patent Holders
Fig 10 University–Industry Collaboration Network
Fig 11 Strategic Partnership Network
Fig 12 Venture Investment Trend
Fig 13 Regional Software-Defined Vehicle Innovation Hubs
Fig 14 Recent M&A, Funding & Partnership Timeline
Fig 15 Competitive White Space Map
List of Figures
RESEARCH METHODOLOGY
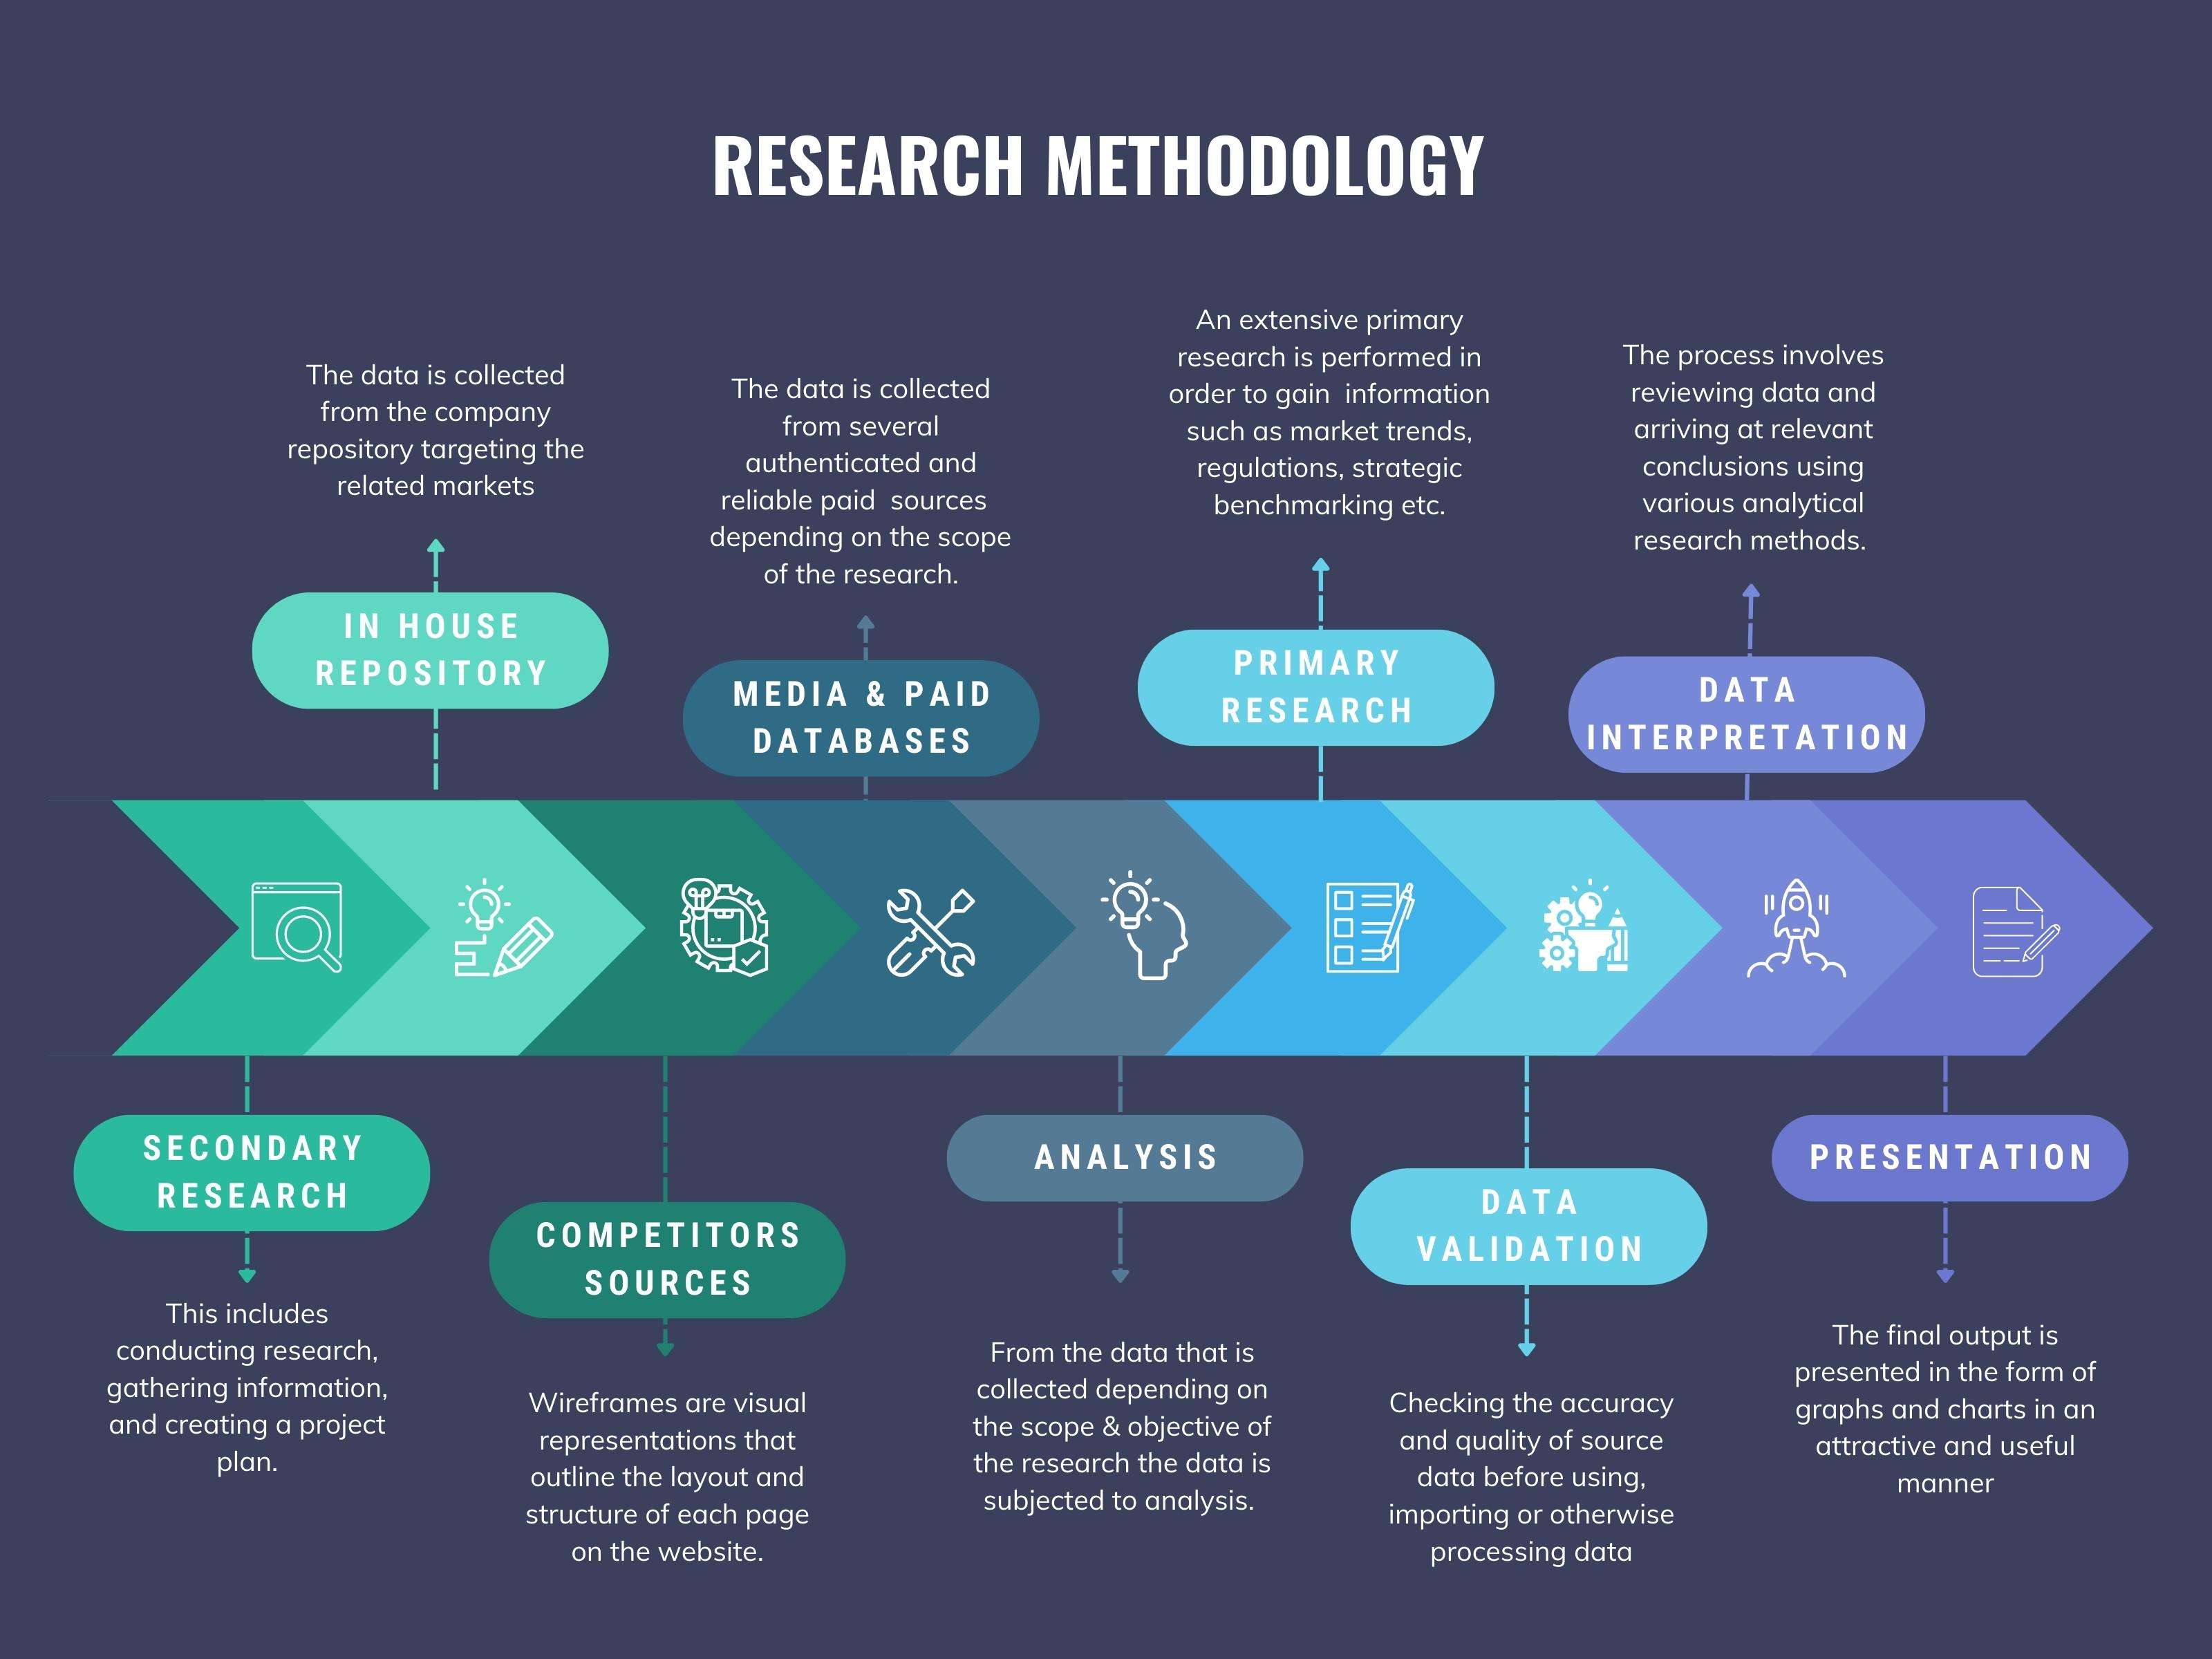
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.