Semiconductor Specialty Chemicals Market
Semiconductor Specialty Chemicals Market Forecasts to 2034 - Global Analysis By Product Type (Photoresists, Wet Chemicals, CMP Slurries, Specialty Gases, Adhesives & Sealants and Cleaning Agents), Semiconductor Device, Application, End User and By Geography
According to Stratistics MRC, the Global Semiconductor Specialty Chemicals Market is accounted for $12.1 billion in 2026 and is expected to reach $20.3 billion by 2034 growing at a CAGR of 6.7% during the forecast period. Semiconductor specialty chemicals play a critical role in semiconductor production by enabling wafer processing, cleaning, etching, deposition, lithography, doping, and packaging operations. The category covers photoresists, solvents, acids, specialty gases, wet-processing chemicals, and other ultra-high-purity materials engineered for demanding fabrication environments. Rising chip manufacturing capacity, sophisticated semiconductor architectures, smaller process geometries, and growing demand from artificial intelligence, automotive, telecommunications, and electronic products are supporting market expansion. Chemical suppliers are focusing on greater purity, consistent performance, sustainability, regulatory compliance, and advanced formulations to enhance production yields and semiconductor manufacturing efficiency.
According to the Semiconductor Industry Association (SIA), global semiconductor sales reached $791.7 billion in 2025, increasing 25.6% from $630.5 billion in 2024. The strong expansion indicates rising semiconductor manufacturing activity and supports demand for materials and specialty chemicals used throughout chip production.
Market Dynamics:
Driver:
Growing semiconductor manufacturing capacity
The expansion of semiconductor fabrication capacity is driving demand for specialty chemicals used throughout chip manufacturing. Newly established fabs and facility expansions consume high-purity materials for processes including wafer cleaning, etching, deposition, lithography, doping, and packaging. Advanced manufacturing technologies further require chemical formulations capable of supporting increasingly sophisticated chip designs and smaller geometries. Rising semiconductor requirements from artificial intelligence, automotive systems, data centers, communications equipment, and consumer electronics are encouraging greater chemical consumption.
Restraint:
High purity and quality control requirements
Stringent purity and quality specifications can restrict growth in the Semiconductor Specialty Chemicals Market. Semiconductor fabrication processes depend on chemicals containing exceptionally low levels of impurities and particles because contamination can negatively influence wafer quality and production yields. Suppliers must invest in advanced purification technologies, controlled manufacturing facilities, specialized packaging, transportation systems, and extensive quality testing to meet semiconductor industry requirements. Such investments increase operating expenses and technical complexity. Smaller chemical producers may struggle to satisfy these rigorous standards, creating barriers to entry and limiting expansion of manufacturing capabilities worldwide.
Opportunity:
Expansion of advanced semiconductor fabrication capacity
Growing investment in semiconductor fabrication facilities offers significant opportunities for specialty chemical suppliers. Newly constructed and modernized fabs require specialized, ultra-high-purity chemicals throughout cleaning, lithography, etching, deposition, and related wafer-processing operations. Efforts by governments and manufacturers to expand regional chipmaking capabilities are also encouraging localized supply chains. Chemical companies can benefit by establishing production facilities closer to semiconductor hubs, forming strategic relationships with manufacturers, and developing application-specific formulations. Rising fab capacity can consequently broaden demand for specialty chemicals used in advanced semiconductor manufacturing worldwide.
Threat:
Geopolitical disruptions and trade restrictions
Geopolitical uncertainty and evolving international trade regulations can challenge the growth of the Semiconductor Specialty Chemicals Market. Manufacturers frequently depend on global networks for obtaining chemical inputs, processing equipment, and finished specialty products. Tariffs, export controls, sanctions, logistics restrictions, and international disputes can disrupt these networks and raise sourcing expenses. Measures targeting semiconductor technologies or materials can further increase uncertainty. Chemical suppliers may respond by developing alternative sourcing arrangements, expanding regional manufacturing, and holding larger inventories, which can increase operating expenses and make supply management more complex.
Covid-19 Impact:
The COVID-19 pandemic created temporary challenges for the Semiconductor Specialty Chemicals Market through manufacturing interruptions, logistical constraints, labor shortages, and disrupted global supply networks. Restrictions on transportation and production affected the availability and delivery of specialized chemical materials. At the same time, increased reliance on remote working, digital communication, computing equipment, and healthcare technologies supported semiconductor demand. As manufacturing activities recovered, chip producers expanded capacity and investment, benefiting specialty chemical consumption. Suppliers also focused more strongly on inventory management, alternative sourcing, and resilient supply-chain strategies after the disruption.
The photoresists segment is expected to be the largest during the forecast period
The photoresists segment is expected to account for the largest market share during the forecast period due to their essential role in semiconductor photolithography. These photosensitive materials allow manufacturers to accurately transfer intricate circuit patterns onto wafers, enabling the production of sophisticated semiconductor architectures. They are widely utilized in manufacturing advanced logic chips, memory devices, and various integrated circuits. The continued evolution of semiconductor fabrication requires photoresists with exceptional purity, sensitivity, resolution, and processing consistency. Consequently, photoresists remain indispensable materials across modern semiconductor wafer fabrication and advanced chip manufacturing operations.
The automotive electronics segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the automotive electronics segment is predicted to witness the highest growth rate as semiconductor content in vehicles continues expanding. Electric vehicles, advanced driver-assistance technologies, connected systems, infotainment platforms, battery controls, and safety functions increasingly depend on sophisticated chips. Manufacturing these semiconductor components requires specialty chemicals for processes including lithography, wafer cleaning, etching, fabrication, and packaging. Increasing vehicle electronics complexity is consequently encouraging greater production of advanced semiconductor devices and creating stronger demand for specialized chemical materials across automotive chip manufacturing operations.
Region with largest share:
During the forecast period, the Asia Pacific region is expected to hold the largest market share, supported by its well-developed semiconductor production base and presence of leading industry manufacturers. Taiwan, South Korea, China, and Japan maintain significant capabilities in chip fabrication, wafer processing, packaging, and electronics manufacturing. Strong regional demand for smartphones, communication systems, automotive electronics, and industrial equipment further supports specialty chemical usage. Established supply chains, increasing fab investments, technical expertise, and continued adoption of advanced semiconductor manufacturing processes reinforce the region’s leading position in specialty chemical demand.
Region with highest CAGR:
Over the forecast period, the North America region is anticipated to exhibit the highest CAGR as regional semiconductor production expands. Investments in new fabs, advanced packaging facilities, and semiconductor technology are strengthening local manufacturing capabilities. Rising requirements for artificial intelligence systems, high-performance computing, automotive technologies, and sophisticated communication equipment are also supporting semiconductor demand. As chip production increases, manufacturers require larger quantities of high-purity specialty chemicals for processes such as wafer fabrication, lithography, cleaning, etching, deposition, and other critical semiconductor manufacturing activities across the region.
Key players in the market
Some of the key players in Semiconductor Specialty Chemicals Market include Entegris, Inc., Air Products and Chemicals, Inc, JSR Corporation, Shin-Etsu Chemical Co., Ltd., Sumitomo Chemical Co., Ltd., Fujifilm Holdings Corporation, Mitsubishi Gas Chemical Company, Inc., Linde plc, CMC Materials, Inc., Kanto Chemical Co., Inc., Soulbrain Co., Ltd., BASF SE, Merck KGaA, Dongjin Semichem Co., Ltd., Adeka Corporation, Honeywell International Inc., Resonac and Mitsubishi Chemical Group.
Key Developments:
In November 2025, Sumitomo Chemical is all set to expand its global footprint in the booming semiconductor market. The company has announced a definitive agreement to acquire 100% of Taiwan-based semiconductor process chemicals company Asia Union Electronic Chemical Corporation (AUECC). The deal, subject to standard regulatory approvals, will mark Sumitomo’s first manufacturing base in Taiwan and it’s second in the United States, alongside its Texas facility.
In November 2025, Merck KGaA has signed a 20-year power purchase agreement (PPA) with SK Innovation E&S to supply renewable electricity to its life science manufacturing sites in Daejeon and Songdo, South Korea. The agreement adds 16 megawatts (MW) of new renewable capacity and represents the company’s longest energy commitment in the Asia-Pacific region.
In October 2025, BASF SE and ANDRITZ Group have signed a license agreement for the use of BASF’s proprietary gas treatment technology, OASE® blue, in a carbon capture project planned to be implemented in the city of Aarhus, Denmark. The project aims to capture approximately 435,000 tons of CO2 annually from the flue gases of a waste-to-energy plant for sequestration; the city of Aarhus has set itself the goal of becoming CO2-neutral by 2030.
Product Types Covered:
• Photoresists
• Wet Chemicals
• CMP Slurries
• Specialty Gases
• Adhesives & Sealants
• Cleaning Agents
Semiconductor Devices Covered:
• Integrated Circuits
• Discrete Devices
• Optoelectronics
• Sensors
Applications Covered:
• Wafer Fabrication
• Photolithography
• Etching
• Chemical Mechanical Planarization (CMP)
• Packaging & Assembly
End Users Covered:
• Consumer Electronics
• Automotive Electronics
• Industrial Equipment
• Telecommunications
• Healthcare Devices
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Semiconductor Specialty Chemicals Market, By Product Type
5.1 Photoresists
5.2 Wet Chemicals
5.3 CMP Slurries
5.4 Specialty Gases
5.5 Adhesives & Sealants
5.6 Cleaning Agents
6 Global Semiconductor Specialty Chemicals Market, By Semiconductor Device
6.1 Integrated Circuits
6.2 Discrete Devices
6.3 Optoelectronics
6.4 Sensors
7 Global Semiconductor Specialty Chemicals Market, By Application
7.1 Wafer Fabrication
7.2 Photolithography
7.3 Etching
7.4 Chemical Mechanical Planarization (CMP)
7.5 Packaging & Assembly
8 Global Semiconductor Specialty Chemicals Market, By End User
8.1 Consumer Electronics
8.2 Automotive Electronics
8.3 Industrial Equipment
8.4 Telecommunications
8.5 Healthcare Devices
9 Global Semiconductor Specialty Chemicals Market, By Geography
9.1 North America
9.1.1 United States
9.1.2 Canada
9.1.3 Mexico
9.2 Europe
9.2.1 United Kingdom
9.2.2 Germany
9.2.3 France
9.2.4 Italy
9.2.5 Spain
9.2.6 Netherlands
9.2.7 Belgium
9.2.8 Sweden
9.2.9 Switzerland
9.2.10 Poland
9.2.11 Rest of Europe
9.3 Asia Pacific
9.3.1 China
9.3.2 Japan
9.3.3 India
9.3.4 South Korea
9.3.5 Australia
9.3.6 Indonesia
9.3.7 Thailand
9.3.8 Malaysia
9.3.9 Singapore
9.3.10 Vietnam
9.3.11 Rest of Asia Pacific
9.4 South America
9.4.1 Brazil
9.4.2 Argentina
9.4.3 Colombia
9.4.4 Chile
9.4.5 Peru
9.4.6 Rest of South America
9.5 Rest of the World (RoW)
9.5.1 Middle East
9.5.1.1 Saudi Arabia
9.5.1.2 United Arab Emirates
9.5.1.3 Qatar
9.5.1.4 Israel
9.5.1.5 Rest of Middle East
9.5.2 Africa
9.5.2.1 South Africa
9.5.2.2 Egypt
9.5.2.3 Morocco
9.5.2.4 Rest of Africa
10 Strategic Market Intelligence
10.1 Industry Value Network and Supply Chain Assessment
10.2 White-Space and Opportunity Mapping
10.3 Product Evolution and Market Life Cycle Analysis
10.4 Channel, Distributor, and Go-to-Market Assessment
11 Industry Developments and Strategic Initiatives
11.1 Mergers and Acquisitions
11.2 Partnerships, Alliances, and Joint Ventures
11.3 New Product Launches and Certifications
11.4 Capacity Expansion and Investments
11.5 Other Strategic Initiatives
12 Company Profiles
12.1 Entegris, Inc.
12.2 Air Products and Chemicals, Inc
12.3 JSR Corporation
12.4 Shin-Etsu Chemical Co., Ltd.
12.5 Sumitomo Chemical Co., Ltd.
12.6 Fujifilm Holdings Corporation
12.7 Mitsubishi Gas Chemical Company, Inc.
12.8 Linde plc
12.9 CMC Materials, Inc.
12.10 Kanto Chemical Co., Inc.
12.11 Soulbrain Co., Ltd.
12.12 BASF SE
12.13 Merck KGaA
12.14 Dongjin Semichem Co., Ltd.
12.15 Adeka Corporation
12.16 Honeywell International Inc.
12.17 Resonac
12.18 Mitsubishi Chemical Group
List of Tables
1 Global Semiconductor Specialty Chemicals Market Outlook, By Region (2023-2034) ($MN)
2 Global Semiconductor Specialty Chemicals Market Outlook, By Product Type (2023-2034) ($MN)
3 Global Semiconductor Specialty Chemicals Market Outlook, By Photoresists (2023-2034) ($MN)
4 Global Semiconductor Specialty Chemicals Market Outlook, By Wet Chemicals (2023-2034) ($MN)
5 Global Semiconductor Specialty Chemicals Market Outlook, By CMP Slurries (2023-2034) ($MN)
6 Global Semiconductor Specialty Chemicals Market Outlook, By Specialty Gases (2023-2034) ($MN)
7 Global Semiconductor Specialty Chemicals Market Outlook, By Adhesives & Sealants (2023-2034) ($MN)
8 Global Semiconductor Specialty Chemicals Market Outlook, By Cleaning Agents (2023-2034) ($MN)
9 Global Semiconductor Specialty Chemicals Market Outlook, By Semiconductor Device (2023-2034) ($MN)
10 Global Semiconductor Specialty Chemicals Market Outlook, By Integrated Circuits (2023-2034) ($MN)
11 Global Semiconductor Specialty Chemicals Market Outlook, By Discrete Devices (2023-2034) ($MN)
12 Global Semiconductor Specialty Chemicals Market Outlook, By Optoelectronics (2023-2034) ($MN)
13 Global Semiconductor Specialty Chemicals Market Outlook, By Sensors (2023-2034) ($MN)
14 Global Semiconductor Specialty Chemicals Market Outlook, By Application (2023-2034) ($MN)
15 Global Semiconductor Specialty Chemicals Market Outlook, By Wafer Fabrication (2023-2034) ($MN)
16 Global Semiconductor Specialty Chemicals Market Outlook, By Photolithography (2023-2034) ($MN)
17 Global Semiconductor Specialty Chemicals Market Outlook, By Etching (2023-2034) ($MN)
18 Global Semiconductor Specialty Chemicals Market Outlook, By Chemical Mechanical Planarization (CMP) (2023-2034) ($MN)
19 Global Semiconductor Specialty Chemicals Market Outlook, By Packaging & Assembly (2023-2034) ($MN)
20 Global Semiconductor Specialty Chemicals Market Outlook, By End User (2023-2034) ($MN)
21 Global Semiconductor Specialty Chemicals Market Outlook, By Consumer Electronics (2023-2034) ($MN)
22 Global Semiconductor Specialty Chemicals Market Outlook, By Automotive Electronics (2023-2034) ($MN)
23 Global Semiconductor Specialty Chemicals Market Outlook, By Industrial Equipment (2023-2034) ($MN)
24 Global Semiconductor Specialty Chemicals Market Outlook, By Telecommunications (2023-2034) ($MN)
25 Global Semiconductor Specialty Chemicals Market Outlook, By Healthcare Devices (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
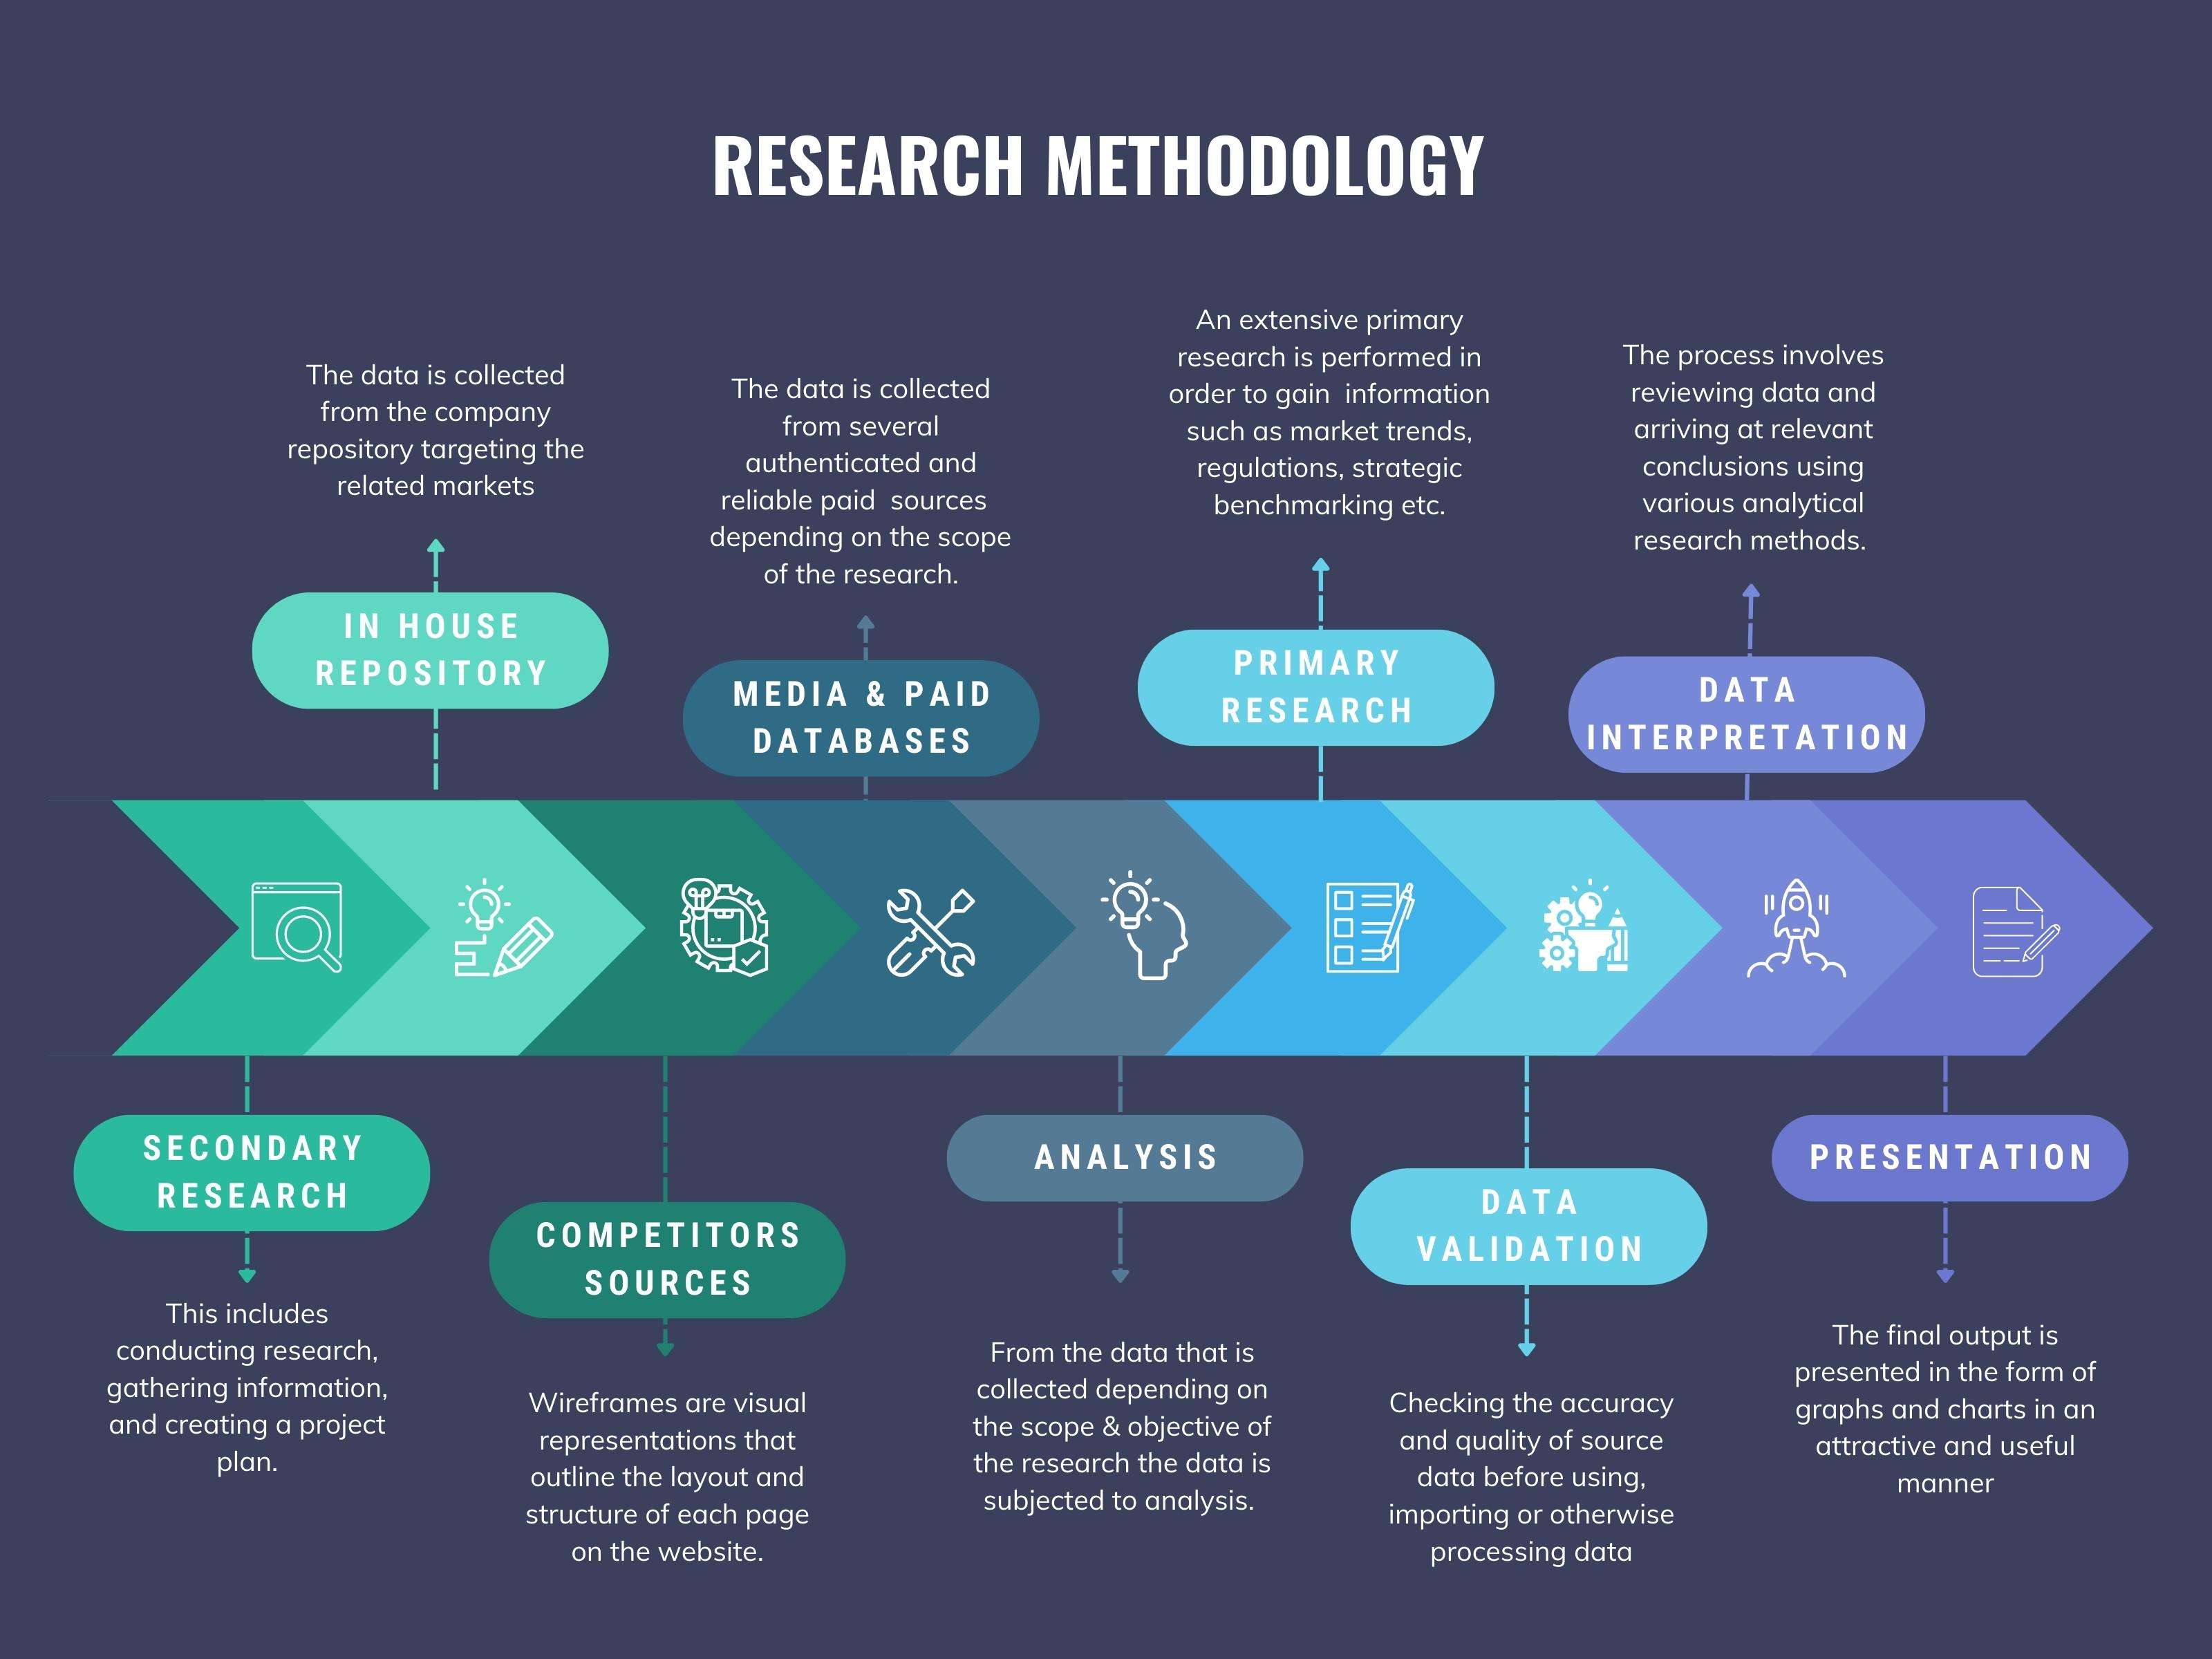
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.