Wireless Connectivity Market
Wireless Connectivity Market Forecasts to 2034 – Global Analysis By Component (Hardware, Software and Services), Deployment, Frequency Band, Technology, Application and By Geography
According to Stratistics MRC, the Global Wireless Connectivity Market is accounted for $121.09 billion in 2026 and is expected to reach $291.34 billion by 2034 growing at a CAGR of 11.6% during the forecast period. Wireless connectivity refers to technologies that enable devices, systems, and networks to exchange data without physical cables, using radio frequency, microwave, infrared, or other wireless signals. It includes Wi-Fi, Bluetooth, cellular networks, near-field communication, satellite communication, and wireless sensor networks. Wireless connectivity is widely used in smartphones, laptops, smart homes, industrial automation, healthcare devices, connected vehicles, and internet of things applications. It supports mobility, remote access, real-time communication, device interoperability, and flexible network deployment across residential, commercial, and industrial environments.
Market Dynamics:
Driver:
Rising adoption of connected devices
Rising adoption of smartphones, wearable devices, smart appliances, connected vehicles, and industrial internet of things systems is driving demand for wireless connectivity solutions. Businesses increasingly deploy wireless networks to connect distributed devices, monitor operations, and support real-time data exchange. Advances in wi-fi, bluetooth, 5g, and low-power wireless technologies are improving speed, coverage, reliability, and energy efficiency. Growing digitalization across manufacturing, healthcare, retail, logistics, and smart infrastructure is further increasing the requirement for seamless wireless communication and connected device interoperability.
Restraint:
Network security and privacy concerns
Network security and privacy concerns remain significant restraints for the wireless connectivity market, particularly as organizations connect more devices and transmit sensitive information across wireless networks. Vulnerabilities in connected devices, unauthorized access, data interception, and weak authentication can increase cybersecurity risks. The growing number of internet of things endpoints also expands potential attack surfaces and creates additional requirements for security management. Organizations may therefore face higher costs for encryption, authentication, monitoring, software updates, and network protection, particularly across large and distributed wireless environments.
Opportunity:
Expansion of smart infrastructure
Expansion of smart infrastructure creates significant opportunities for wireless connectivity providers across cities, buildings, transportation systems, utilities, and industrial facilities. Smart lighting, connected surveillance, intelligent traffic systems, environmental monitoring, and automated building management require reliable wireless communication between sensors, devices, and centralized platforms. Technologies such as 5g, wi-fi 7, low-power wide-area networks, and private wireless networks can support higher device densities, lower latency, and improved coverage. Increasing investment in digital infrastructure is therefore creating new deployment opportunities for wireless connectivity solutions.
Threat:
Interoperability and technology fragmentation
Interoperability and technology fragmentation represent potential threats to wireless connectivity market development as organizations adopt multiple communication standards, platforms, devices, and network architectures. Differences between protocols can complicate integration, device management, and network expansion, particularly in large internet of things deployments. Rapid technological changes may also shorten equipment lifecycles and increase upgrade requirements for businesses. In addition, compatibility limitations between legacy infrastructure and newer wireless technologies can raise deployment costs and create operational complexity, potentially slowing adoption among cost-sensitive organizations.
Covid-19 Impact:
The covid-19 pandemic increased reliance on wireless connectivity as businesses, educational institutions, healthcare providers, and consumers rapidly adopted remote working, online learning, telehealth, and digital services. Demand for wi-fi equipment, broadband connectivity, video conferencing, and connected devices increased during periods of movement restrictions. However, supply chain disruptions, manufacturing shutdowns, component shortages, and delayed infrastructure investments affected equipment availability and deployment schedules. As organizations continued hybrid work and digital operations after the pandemic, demand for reliable wireless connectivity remained structurally elevated.
The hardware segment is expected to be the largest during the forecast period
The hardware segment is expected to account for the largest market share during the forecast period, owing to the widespread requirement for wireless routers, network controllers, antennas, connectivity chipsets, and radio frequency components across enterprise, consumer, and industrial networks. Growing deployment of high-speed wireless infrastructure, increasing connected device volumes, and upgrades toward advanced Wi-Fi and cellular technologies are supporting hardware demand. Additionally, rising investments in network modernization, edge connectivity, and internet of things infrastructure are encouraging organizations to expand and upgrade physical wireless networking equipment.
The cellular connectivity segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the cellular connectivity segment is predicted to witness the highest growth rate, driven by the increasing demand for high-speed data transmission, wider network coverage, and reliable communication across connected devices. The expansion of fifth-generation (5G) networks, growing adoption of Internet of Things applications, and rising investments in smart cities, connected vehicles, and industrial automation are expected to accelerate market growth. Furthermore, continuous improvements in network capacity, reduced latency, and energy-efficient connectivity solutions are likely to support the adoption of cellular connectivity across diverse industries.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, due to widespread adoption of advanced wireless technologies across enterprises, telecommunications, smart infrastructure, and consumer applications. Strong investments in 5G networks, Wi-Fi 6 and Wi-Fi 7 infrastructure, connected devices, and internet of things deployments are supporting regional demand. The presence of major technology companies, developed digital infrastructure, and increasing adoption of cloud, edge computing, and connected enterprise solutions further strengthens the region’s wireless connectivity market.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR fuelled by rapid digitalization, expanding telecommunications infrastructure, and increasing adoption of connected devices across emerging economies. Countries such as China, India, Japan, South Korea, and Southeast Asian markets are investing heavily in 5G, advanced Wi-Fi, smart manufacturing, connected vehicles, and internet of things ecosystems. Growing smartphone penetration, smart city initiatives, industrial automation, and expanding enterprise connectivity requirements are further creating significant opportunities for wireless connectivity technology providers across the region.,
Key players in the market
Some of the key players in Wireless Connectivity Market include Cisco Systems, Inc., Qualcomm Incorporated, Broadcom Inc., Huawei Technologies Co., Ltd., Nokia Corporation, Ericsson, Samsung Electronics Co., Ltd., Intel Corporation, MediaTek Inc., Texas Instruments Incorporated, NXP Semiconductors N.V., STMicroelectronics N.V., Infineon Technologies AG, Microchip Technology Inc., Synaptics Incorporated, Silicon Laboratories Inc., and Nordic Semiconductor ASA.
Key Developments:
In Sep 2026, Ericsson and VodafoneThree launched the rollout of a next-generation cloud-native 5G Core network under their SEK 12.5 billion partnership. The deployment supports differentiated connectivity services, network slicing, and higher-capacity wireless services for enterprise and consumer applications.
In Sep 2026, Nokia and Microsoft expanded collaboration on network automation through an agentic, unified data foundation. The initiative is designed to support AI-driven network operations and accelerate automation across telecommunications infrastructure, strengthening intelligent connectivity capabilities.
In Jul 2026, Qualcomm completed its acquisition of Modular, combining Qualcomm Technologies’ energy-efficient computing capabilities with Modular’s AI-native software platform. The transaction strengthens Qualcomm’s ability to deliver integrated AI computing solutions across edge infrastructure, data centers, and industrial applications.
Components Covered:
• Hardware
• Software
• Services
Deployments Covered:
• On-Premises
• Cloud-Based
• Hybrid
Frequency Bands Covered:
• Sub-1 GHz
• 1 GHz–6 GHz
• 6 GHz–24 GHz
• Above 24 GHz
Technologies Covered:
• Wi-Fi
• Bluetooth
• Cellular
• Zigbee
• Thread
• Satellite Connectivity
Applications Covered
• Consumer Electronics
• Smart Home
• Healthcare
• Automotive and Transportation
• Industrial
• Enterprise
• Government
• Agriculture
• Other Applications
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Wireless Connectivity Market, By Component
5.1 Hardware
5.2 Software
5.3 Services
6 Global Wireless Connectivity Market, By Deployment
6.1 On-Premises
6.2 Cloud-Based
6.3 Hybrid
7 Global Wireless Connectivity Market, By Frequency Band
7.1 Sub-1 GHz
7.2 1 GHz–6 GHz
7.3 6 GHz–24 GHz
7.4 Above 24 GHz
8 Global Wireless Connectivity Market, By Technology
8.1 Wi-Fi
8.2 Bluetooth
8.3 Zigbee
8.4 Near Field Communication (NFC)
8.5 Cellular Connectivity
8.6 LPWAN
8.7 Satellite Connectivity
9 Global Wireless Connectivity Market, By Application
9.1 Consumer Electronics
9.2 Smart Home
9.3 Healthcare
9.4 Automotive and Transportation
9.5 Industrial
9.6 Enterprise
9.7 Government
9.8 Agriculture
9.9 Other Applications
10 Global Wireless Connectivity Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Cisco Systems, Inc.
13.2 Qualcomm Incorporated
13.3 Broadcom Inc.
13.4 Huawei Technologies Co., Ltd.
13.5 Nokia Corporation
13.6 Ericsson
13.7 Samsung Electronics Co., Ltd.
13.8 Intel Corporation
13.9 MediaTek Inc.
13.10 Texas Instruments Incorporated
13.11 NXP Semiconductors N.V.
13.12 STMicroelectronics N.V.
13.13 Infineon Technologies AG
13.13 Microchip Technology Inc.
13.15 Synaptics Incorporated
13.16 Silicon Laboratories Inc.
13.17 Nordic Semiconductor ASA
List of Tables
1 Global Wireless Connectivity Market Outlook, By Region (2023-2034) ($MN)
2 Global Wireless Connectivity Market Outlook, By Component (2023-2034) ($MN)
3 Global Wireless Connectivity Market Outlook, By Hardware (2023-2034) ($MN)
4 Global Wireless Connectivity Market Outlook, By Software (2023-2034) ($MN)
5 Global Wireless Connectivity Market Outlook, By Services (2023-2034) ($MN)
6 Global Wireless Connectivity Market Outlook, By Deployment (2023-2034) ($MN)
7 Global Wireless Connectivity Market Outlook, By On-Premises (2023-2034) ($MN)
8 Global Wireless Connectivity Market Outlook, By Cloud-Based (2023-2034) ($MN)
9 Global Wireless Connectivity Market Outlook, By Hybrid (2023-2034) ($MN)
10 Global Wireless Connectivity Market Outlook, By Frequency Band (2023-2034) ($MN)
11 Global Wireless Connectivity Market Outlook, By Sub-1 GHz (2023-2034) ($MN)
12 Global Wireless Connectivity Market Outlook, By 1 GHz–6 GHz (2023-2034) ($MN)
13 Global Wireless Connectivity Market Outlook, By 6 GHz–24 GHz (2023-2034) ($MN)
14 Global Wireless Connectivity Market Outlook, By Above 24 GHz (2023-2034) ($MN)
15 Global Wireless Connectivity Market Outlook, By Technology (2023-2034) ($MN)
16 Global Wireless Connectivity Market Outlook, By Wi-Fi (2023-2034) ($MN)
17 Global Wireless Connectivity Market Outlook, By Bluetooth (2023-2034) ($MN)
18 Global Wireless Connectivity Market Outlook, By Zigbee (2023-2034) ($MN)
19 Global Wireless Connectivity Market Outlook, By Near Field Communication (NFC) (2023-2034) ($MN)
20 Global Wireless Connectivity Market Outlook, By Cellular Connectivity (2023-2034) ($MN)
21 Global Wireless Connectivity Market Outlook, By LPWAN (2023-2034) ($MN)
22 Global Wireless Connectivity Market Outlook, By Satellite Connectivity (2023-2034) ($MN)
23 Global Wireless Connectivity Market Outlook, By Application (2023-2034) ($MN)
24 Global Wireless Connectivity Market Outlook, By Consumer Electronics (2023-2034) ($MN)
25 Global Wireless Connectivity Market Outlook, By Smart Home (2023-2034) ($MN)
26 Global Wireless Connectivity Market Outlook, By Healthcare (2023-2034) ($MN)
27 Global Wireless Connectivity Market Outlook, By Automotive and Transportation (2023-2034) ($MN)
28 Global Wireless Connectivity Market Outlook, By Industrial (2023-2034) ($MN)
29 Global Wireless Connectivity Market Outlook, By Enterprise (2023-2034) ($MN)
30 Global Wireless Connectivity Market Outlook, By Government (2023-2034) ($MN)
31 Global Wireless Connectivity Market Outlook, By Agriculture (2023-2034) ($MN)
32 Global Wireless Connectivity Market Outlook, By Other Applications (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
According to Stratistics MRC, the Global Cloud Infrastructure Market is accounted for $335.70 billion in 2026 and is expected to reach $944.25 billion by 2034 growing at a CAGR of 13.8% during the forecast period. Cloud infrastructure refers to the combination of computing resources, including servers, storage, networking, virtualization, and software, delivered through cloud environments. It enables organizations to access scalable information technology resources without maintaining extensive physical infrastructure. Cloud infrastructure is used for data storage, application hosting, backup and disaster recovery, artificial intelligence workloads, enterprise applications, analytics, and digital services. It supports flexible resource allocation, remote access, faster deployment, operational scalability, and improved infrastructure utilization across businesses, government organizations, and technology-driven industries.
Market Dynamics:
Driver:
Rising demand for scalable computing
Rising demand for scalable computing resources is driving adoption of cloud infrastructure across businesses and industries. Organizations increasingly require flexible computing, storage, and networking capabilities to manage growing data volumes, digital applications, and variable workloads. Cloud infrastructure allows enterprises to increase or decrease resources according to operational requirements, reducing dependence on fixed physical infrastructure. The expansion of artificial intelligence, machine learning, big data analytics, internet of things applications, and enterprise software is further increasing demand for scalable and easily accessible cloud resources.
Restraint:
Data security and privacy concerns
Data security and privacy concerns remain a major restraint for the cloud infrastructure market, particularly among organizations handling sensitive financial, healthcare, government, and customer information. Cloud environments can face risks related to unauthorized access, data breaches, misconfiguration, identity theft, and cyberattacks. Organizations must implement advanced encryption, access controls, monitoring systems, and compliance measures to protect cloud workloads. These additional requirements can increase implementation and management costs, while regulatory differences across countries may further complicate cloud infrastructure adoption for multinational enterprises.
Opportunity:
Expansion of hybrid cloud environments
Expansion of hybrid cloud environments creates significant opportunities for cloud infrastructure providers as organizations seek greater flexibility between public and private computing environments. Hybrid infrastructure allows enterprises to maintain sensitive workloads on private systems while using public cloud resources for scalable applications and variable workloads. Increasing adoption of artificial intelligence, edge computing, data analytics, and distributed applications is encouraging businesses to modernize their infrastructure. Demand for cloud migration, workload optimization, automation, and integrated management platforms are expected to create additional opportunities across multiple industries.
Threat:
Growing cybersecurity risks
Growing cybersecurity risks represent a significant threat to cloud infrastructure providers as cybercriminals increasingly target cloud environments, applications, identities, and interconnected systems. Sophisticated ransomware, credential theft, supply chain attacks, and cloud misconfiguration can disrupt operations and expose sensitive information. The increasing complexity of multi-cloud and hybrid environments can make security monitoring and threat detection more difficult. Organizations may therefore face higher cybersecurity expenditures and stricter compliance requirements. Persistent security incidents could also affect customer confidence and slow cloud adoption among highly regulated and security-sensitive industries.
Covid-19 Impact:
The covid-19 pandemic accelerated cloud infrastructure adoption as organizations rapidly shifted toward remote work, virtual collaboration, online services, and distributed business operations. Enterprises increased their use of cloud computing, storage, networking, and software platforms to maintain operational continuity during lockdowns and workplace restrictions. Demand also increased for video conferencing, digital commerce, remote learning, and online healthcare applications. However, supply chain disruptions and uncertainty delayed some infrastructure investments. The pandemic ultimately strengthened long-term reliance on scalable, remotely accessible, and flexible cloud infrastructure.
The cloud-based segment is expected to be the largest during the forecast period
The cloud-based segment is expected to account for the largest market share during the forecast period, due to the increasing adoption of scalable computing resources, flexible storage solutions, and cost-effective IT infrastructure. Organizations are shifting workloads to cloud environments to reduce capital expenditure, improve operational efficiency, and support remote access to business applications. Furthermore, the growing demand for artificial intelligence, big data analytics, and digital transformation is encouraging enterprises to invest in cloud-based infrastructure, strengthening its adoption across various industries.
The small and medium-sized enterprises segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the small and medium-sized enterprises segment is predicted to witness the highest growth rate, owing to the increasing adoption of affordable cloud infrastructure solutions. Cloud platforms enable smaller businesses to access advanced computing, storage, networking, and security capabilities without significant upfront investment in physical infrastructure. Additionally, the growing availability of subscription-based services, managed cloud solutions, and scalable deployment models is helping SMEs improve productivity, modernize operations, and compete effectively in digital markets.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by the presence of leading cloud service providers, advanced digital infrastructure, and widespread enterprise adoption of cloud computing. High investments in artificial intelligence, data analytics, cybersecurity, and high-performance computing are increasing demand for scalable cloud infrastructure. The region also benefits from extensive data center capacity, strong technology ecosystems, and early adoption of hybrid and multi-cloud environments. Growing enterprise digital transformation further supports cloud infrastructure deployment across major industries.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, propelled by rapid digital transformation, expanding data center infrastructure, and increasing cloud adoption across emerging economies. Countries including China, India, Japan, South Korea, and Southeast Asian markets are investing substantially in cloud computing, artificial intelligence, big data, and digital services. Growing internet penetration, expanding enterprise workloads, government-led digitalization initiatives, and increasing adoption of public, hybrid, and multi-cloud environments are further accelerating demand for cloud infrastructure throughout the region.
Key players in the market
Some of the key players in Cloud Infrastructure Market include Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Oracle Corporation, Alibaba Cloud, Huawei Technologies Co., Ltd., Tencent Cloud, Dell Technologies Inc., Hewlett Packard Enterprise, Cisco Systems, Inc., Equinix, Inc., Digital Realty Trust, Inc., OVHcloud, Rackspace Technology, Inc., Akamai Technologies, Inc., and Broadcom Inc.
Key Developments:
In Sep 2026, Cisco and AWS formalized a multi-year agreement to co-develop security solutions through Splunk, focusing on protecting enterprise cloud environments against AI-driven attacks. The collaboration combines Cisco and Splunk security capabilities with AWS cloud technologies to strengthen cloud infrastructure protection.
List of Figures
RESEARCH METHODOLOGY
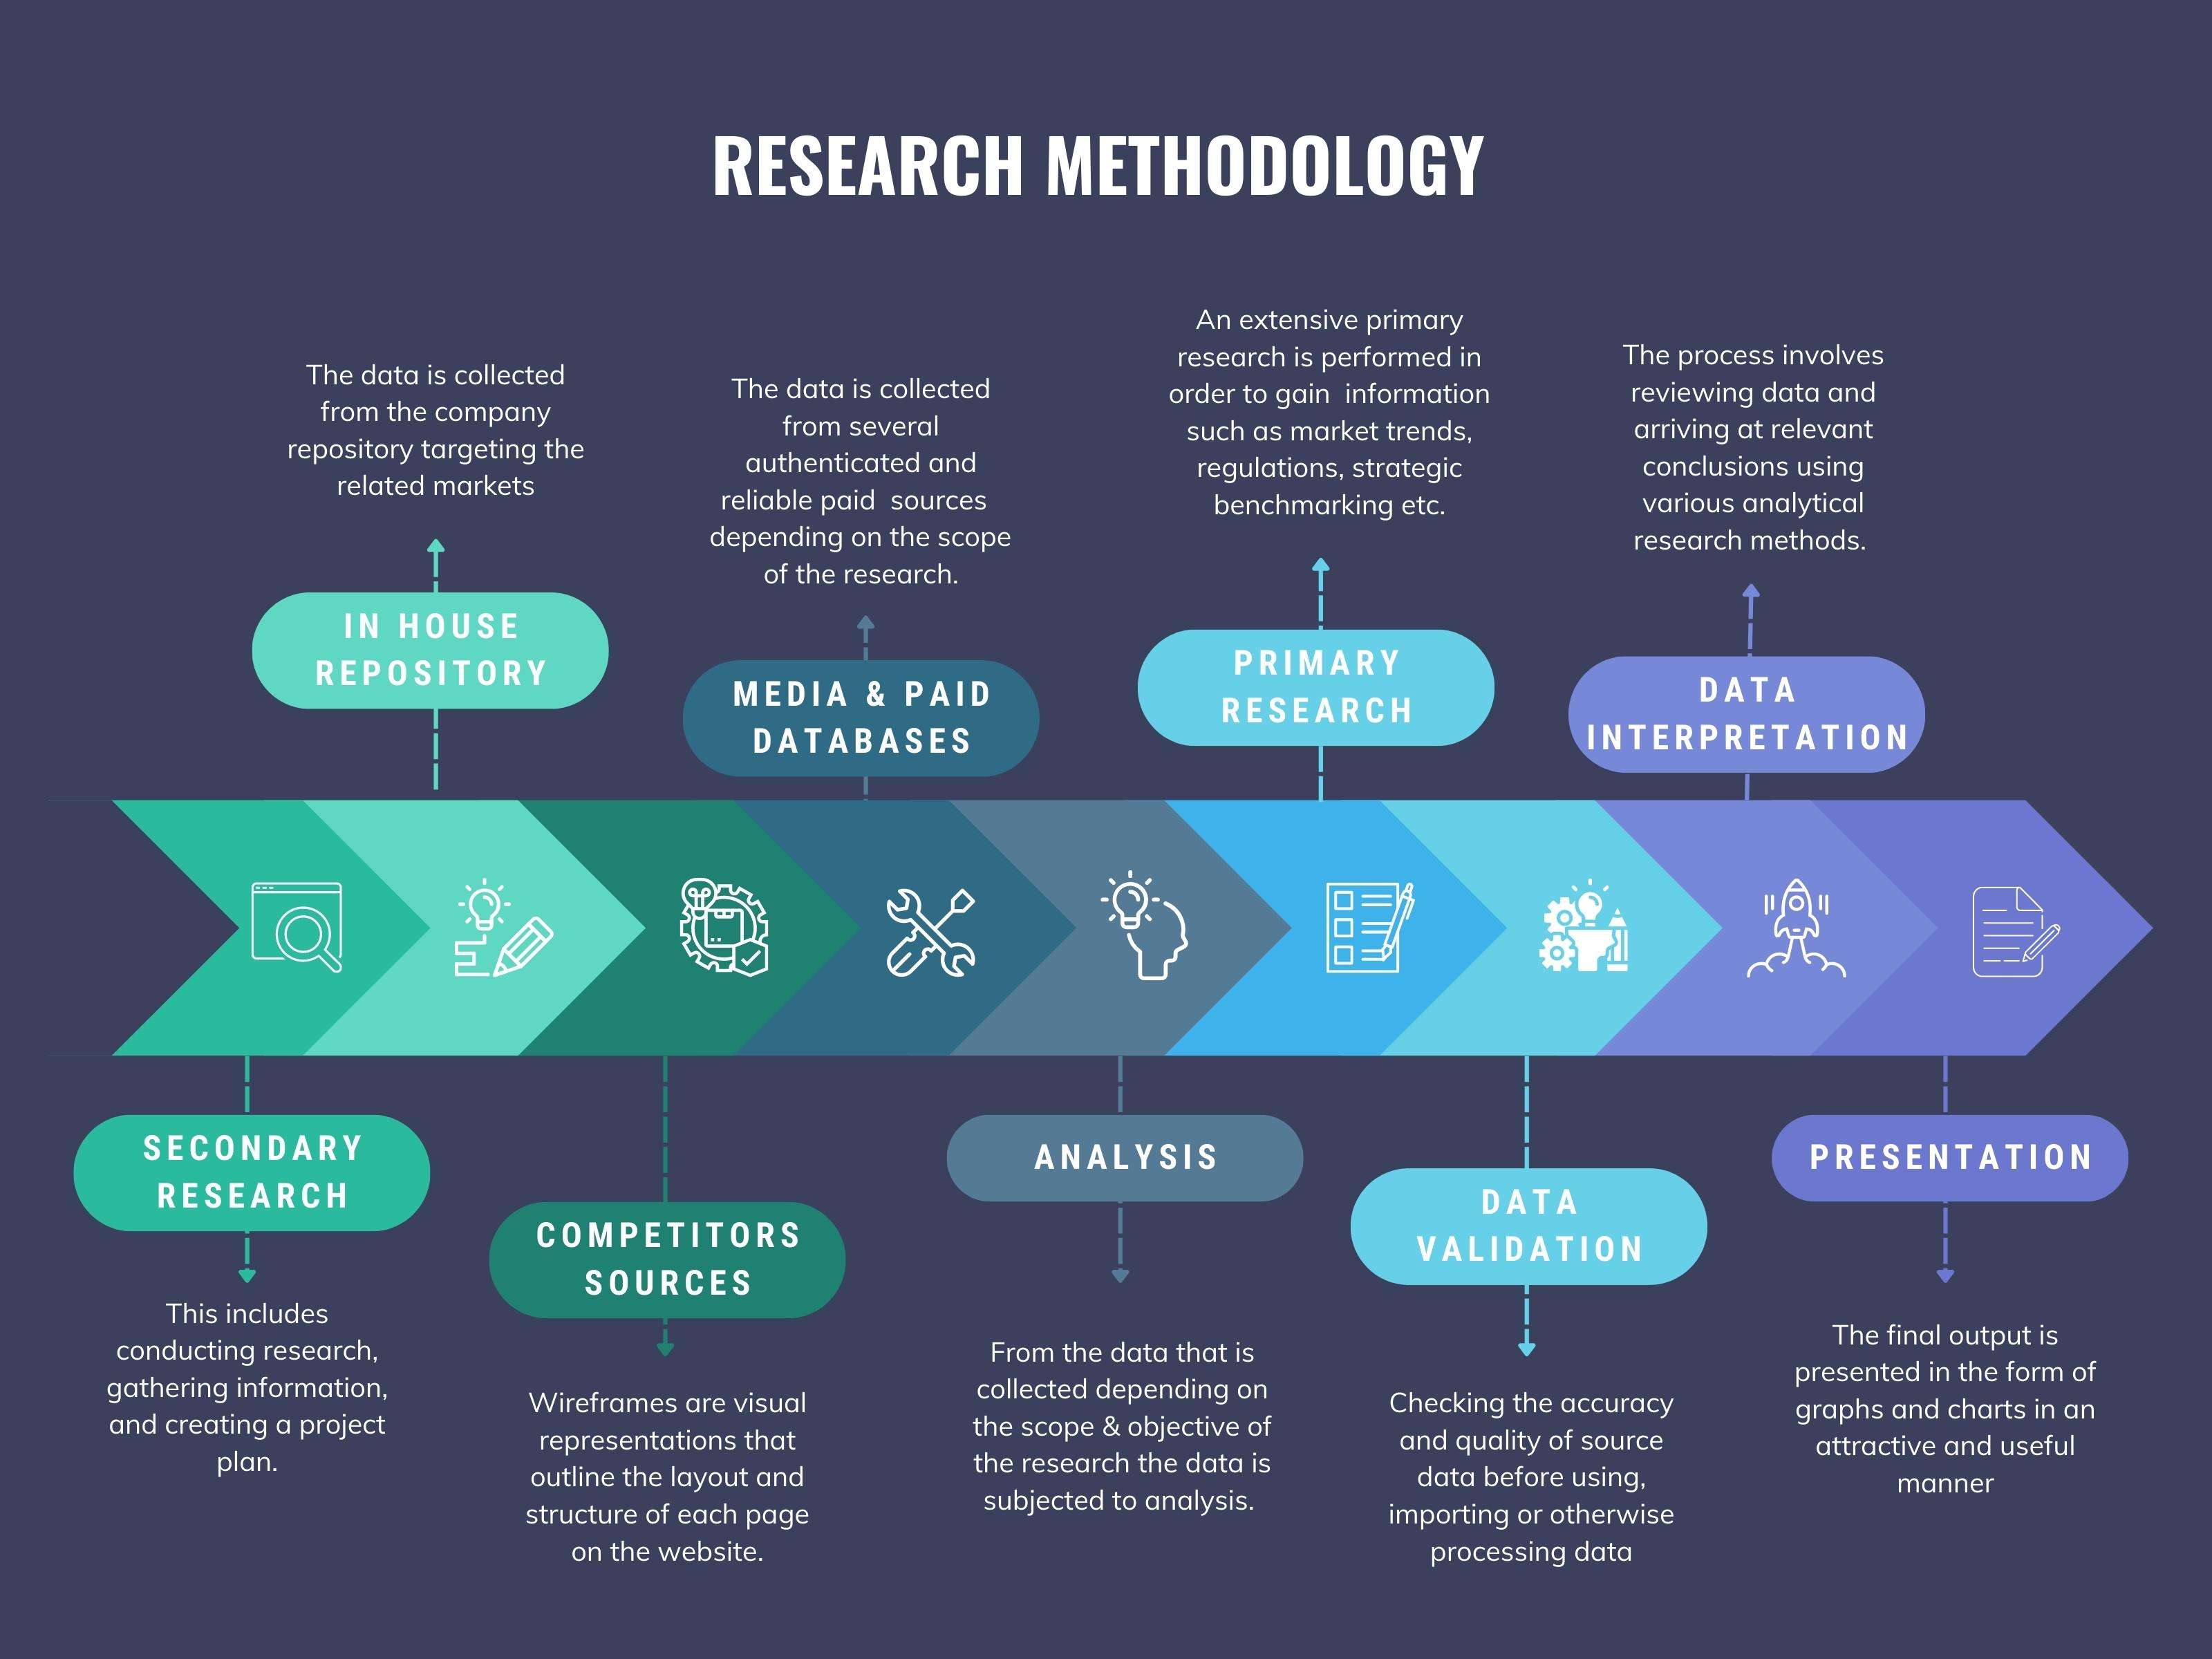
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.