Aerospace Materials Market
Aerospace Materials Market Forecasts To 2034 - Global Analysis By Material Type (Aluminum Alloys, Titanium Alloys, Steel Alloys, Superalloys, Magnesium Alloys, Polymer Materials, Ceramic Materials and Composite Materials), Composite Type, Aerospace Vehicle Type, Manufacturing Process, Application, End User and By Geography
According to Stratistics MRC, the Global Aerospace Materials Market is accounted for $60.4 billion in 2026 and is expected to reach $113.5 billion by 2034 growing at a CAGR of 8.2% during the forecast period. The Aerospace Materials Market covers specialized materials required for producing and improving aircraft, spacecraft, and defense systems. Major material categories include aluminum alloys, titanium, nickel alloys, composites, specialty steels, ceramics, and advanced polymers. Market growth is supported by expanding aircraft manufacturing, fleet replacement programs, lightweight aircraft designs, fuel-efficiency initiatives, and increased use of composite structures. Innovations in material technologies, additive manufacturing, and heat-resistant materials are also contributing to industry expansion. Furthermore, increasing expenditure on commercial aviation, military aerospace, space missions, and unmanned platforms is generating new opportunities for manufacturers to supply lightweight, high-strength, heat-resistant, and durable materials for next-generation aerospace applications.
Market Dynamics:
Driver:
Increasing Demand for Lightweight Materials
The aerospace industry's focus on reducing aircraft weight is creating strong demand for advanced lightweight materials. Lower structural weight helps improve fuel economy, operational efficiency, aircraft range, and environmental performance. As a result, aerospace manufacturers are increasingly adopting composites, titanium alloys, aluminum-lithium alloys, and other lightweight alternatives instead of traditional materials. Composites are gaining particular attention because they combine high strength with low weight, corrosion resistance, and flexible design possibilities. Their increasing use in fuselages, wings, propulsion components, and aircraft interiors is creating significant opportunities for material producers. Continued efforts to develop fuel-efficient and lower-emission aircraft will further strengthen this market driver.
Restraint:
High Costs and Lengthy Qualification Cycles
Aerospace-grade carbon fiber remains expensive and energy-intensive to produce, pressuring supplier margins and limiting the adoption of lower-cost alternatives. More fundamentally, introducing any new material into an aircraft requires exhaustive certification and qualification processes that can span years. This lengthy timeline stifles rapid innovation and short-term supply flexibility, locking the industry into established, qualified supply chains that are themselves fragile. Consequently, even with strong demand signals from commercial aviation and defense, the market's growth is effectively capped by the industry's inability to quickly and reliably source certified materials at scale.
Opportunity:
Expansion of Advanced Composite Materials
Greater adoption of advanced composites creates substantial growth potential for aerospace material manufacturers. Materials such as carbon fiber-reinforced polymers and ceramic matrix composites offer low weight, high strength, durability, and resistance to demanding operating environments. The industry's focus on fuel efficiency is encouraging greater integration of composites into aircraft wings, fuselages, propulsion components, and cabin structures. Technological developments in carbon fibers, resin systems, automated placement technologies, and composite manufacturing are improving performance while reducing production challenges. Companies can benefit from this opportunity by developing innovative, lightweight, durable, and economical composite solutions for commercial aviation, defense aircraft, spacecraft, and unmanned aerospace platforms.
Threat:
Stringent Aerospace Certification and Regulatory Requirements
Demanding aerospace certification and regulatory standards can restrict the rapid introduction of new materials. Aerospace materials must satisfy rigorous requirements covering safety, durability, fatigue resistance, fire performance, chemical stability, and operation under extreme environmental conditions. Extensive testing, qualification, documentation, and approval procedures can increase development expenses and lengthen commercialization timelines. Smaller material companies may face greater financial and technical difficulties in meeting these requirements. In addition, revisions to aviation regulations and material standards may force manufacturers to redesign products or alter manufacturing processes. Such compliance demands can increase operating complexity and costs while slowing the adoption of innovative aerospace materials across aircraft and spacecraft applications.
Covid-19 Impact:
The COVID-19 outbreak substantially affected the aerospace materials market, primarily through reduced aviation activity, delayed aircraft deliveries, and disruptions across global manufacturing networks. Declining passenger demand caused airlines to postpone aircraft purchases, fleet expansion, and related investments, prompting manufacturers to reduce production levels. Consequently, demand for titanium, aluminum alloys, composites, superalloys, and other specialized aerospace materials declined. Manufacturing shutdowns, logistics restrictions, labor shortages, and interrupted supply chains created additional challenges for material suppliers. Recovery began as air travel gradually returned, aircraft manufacturing restarted, and airlines resumed fleet renewal plans. Increased defense spending, space activities, and government assistance further contributed to market stabilization and recovery.
The Aluminum Alloys segment is expected to be the largest during the forecast period
The Aluminum Alloys segment is expected to account for the largest market share during the forecast period, driven by its extensive application in aircraft fuselages, wings, structural frames, and other components requiring lightweight and reliable construction. Aluminum alloys offer a strong balance of low weight, mechanical strength, corrosion resistance, ease of processing, and economic advantages, supporting their adoption across commercial and defense aircraft. Their established supply chains, mature processing technologies, recyclability, and compatibility with conventional aerospace manufacturing methods further reinforce demand. Moreover, increasing aircraft production and fleet replacement activities are supporting continued utilization of aluminum alloys in aerospace structures requiring dependable performance and efficient manufacturing.
The Airframes & Structural Components segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Airframes & Structural Components segment is predicted to witness the highest growth rate, supported by increasing requirements for lightweight, durable, and high-performance aircraft structures. Manufacturers are expanding their use of advanced aluminum alloys, titanium alloys, and composite materials to achieve weight reduction while maintaining structural integrity and operational safety. Expanding commercial aircraft manufacturing, replacement of aging fleets, and increasing military aviation investments are strengthening demand for advanced structural materials. Furthermore, the development of fuel-efficient and lower-emission aircraft is accelerating the adoption of innovative materials in wings, fuselages, frames, and other structural components. This evolving aircraft design landscape is creating substantial growth opportunities for aerospace material manufacturers.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, supported by its well-developed aerospace industry, substantial commercial and defense aircraft manufacturing, and concentration of leading industry participants. The region has a mature ecosystem of aircraft producers, defense organizations, material manufacturers, and research institutions that promotes technological advancement. Demand for composites, lightweight alloys, titanium, superalloys, and other specialized materials is increasing through aircraft replacement, modernization, and new aircraft development programs. Furthermore, strong defense expenditure, expanding space exploration initiatives, and investments in advanced aerospace technologies are contributing to regional market growth and sustaining demand for high-performance aerospace materials across diverse applications.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, supported by rising commercial aviation activity, expanding aircraft manufacturing, and increasing investments in regional aerospace capabilities. Governments and industry participants are developing stronger aircraft production, maintenance, and supply networks to accommodate increasing air passenger demand and fleet modernization. Growing defense expenditures are further supporting the development and procurement of advanced aircraft, stimulating demand for composites, titanium alloys, lightweight metals, and other specialized materials. Moreover, expanding space programs, satellite deployment, launch vehicle development, and space infrastructure investments are generating additional opportunities. Together, these trends are strengthening the adoption of advanced aerospace materials across Asia-Pacific.
Key players in the market
Some of the key players in Aerospace Materials Market include Syensqo, Toray Industries, Hexcel Corporation, Teijin Limited, Mitsubishi Chemical Group, ATI, Alcoa Corporation, Constellium, Howmet Aerospace, VSMPO-AVISMA Corporation, SGL Carbon, Carpenter Technology Corporation, Precision Castparts Corp., TIMET, Kobe Steel, Materion Corporation, Huntsman International and Victrex.
Key Developments:
In June 2026, Hexcel and Deutsche Aircraft signed a long-term industrial partnership and supply agreement for advanced composite solutions for the D328eco regional aircraft program. The materials will support primary and secondary structures, with emphasis on weight reduction, durability, fatigue resistance, and sustainability.
In April 2026, Toray Composite Materials America entered an MOU with Convergent Manufacturing Technologies to deploy digital engineering and cure-simulation tools using Toray resin-system datasets for aerospace and industrial applications. The collaboration aims to accelerate material evaluation, design optimization, and adoption of advanced composites.
In March 2026, Syensqo secured a new multi-year agreement with Boeing to continue supplying advanced composite and adhesive materials for Boeing’s commercial and defense programs, covering primary and secondary structures, interiors, and surfacing.
Material Types Covered:
• Aluminum Alloys
• Titanium Alloys
• Steel Alloys
• Superalloys
• Magnesium Alloys
• Polymer Materials
• Ceramic Materials
• Composite Materials
Composite Types Covered:
• Carbon Fiber Reinforced Polymer
• Glass Fiber Reinforced Polymer
• Aramid Fiber Reinforced Polymer
• Ceramic Matrix Composites
• Other Composite Materials
Aerospace Vehicle Types Covered:
• Commercial Aircraft
• Military Aircraft
• Business Jets
• General Aviation Aircraft
• Helicopters
• Unmanned Aerial Vehicles
• Spacecraft & Launch Vehicles
Manufacturing Processes Covered:
• Casting
• Forging
• Rolling
• Extrusion
• Machining
• Additive Manufacturing
• Composite Layup & Curing
• Powder Metallurgy
Applications Covered:
• Airframes & Structural Components
• Engine & Propulsion Components
• Aircraft Interiors
• Landing Gear Components
• Flight Control Components
• Electrical & Electronic Components
• Windows & Windshields
• Spacecraft Structures
End Users Covered:
• Aerospace Original Equipment Manufacturers
• Maintenance, Repair & Overhaul Providers
• Defense Aerospace OEMs & Contractors
• Space Agencies & Commercial Space Companies
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Aerospace Materials Market, By Material Type
5.1 Aluminum Alloys
5.2 Titanium Alloys
5.3 Steel Alloys
5.4 Superalloys
5.5 Magnesium Alloys
5.6 Polymer Materials
5.7 Ceramic Materials
5.8 Composite Materials
6 Global Aerospace Materials Market, By Composite Type
6.1 Carbon Fiber Reinforced Polymer
6.2 Glass Fiber Reinforced Polymer
6.3 Aramid Fiber Reinforced Polymer
6.4 Ceramic Matrix Composites
6.5 Other Composite Materials
7 Global Aerospace Materials Market, By Aerospace Vehicle Type
7.1 Commercial Aircraft
7.2 Military Aircraft
7.3 Business Jets
7.4 General Aviation Aircraft
7.5 Helicopters
7.6 Unmanned Aerial Vehicles
7.7 Spacecraft & Launch Vehicles
8 Global Aerospace Materials Market, By Manufacturing Process
8.1 Casting
8.2 Forging
8.3 Rolling
8.4 Extrusion
8.5 Machining
8.6 Additive Manufacturing
8.7 Composite Layup & Curing
8.8 Powder Metallurgy
9 Global Aerospace Materials Market, By Application
9.1 Airframes & Structural Components
9.2 Engine & Propulsion Components
9.3 Aircraft Interiors
9.4 Landing Gear Components
9.5 Flight Control Components
9.6 Electrical & Electronic Components
9.7 Windows & Windshields
9.8 Spacecraft Structures
10 Global Aerospace Materials Market, By End User
10.1 Aerospace Original Equipment Manufacturers
10.2 Maintenance, Repair & Overhaul Providers
10.3 Defense Aerospace OEMs & Contractors
10.4 Space Agencies & Commercial Space Companies
11 Global Aerospace Materials Market, By Geography
11.1 North America
11.1.1 United States
11.1.2 Canada
11.1.3 Mexico
11.2 Europe
11.2.1 United Kingdom
11.2.2 Germany
11.2.3 France
11.2.4 Italy
11.2.5 Spain
11.2.6 Netherlands
11.2.7 Belgium
11.2.8 Sweden
11.2.9 Switzerland
11.2.10 Poland
11.2.11 Rest of Europe
11.3 Asia Pacific
11.3.1 China
11.3.2 Japan
11.3.3 India
11.3.4 South Korea
11.3.5 Australia
11.3.6 Indonesia
11.3.7 Thailand
11.3.8 Malaysia
11.3.9 Singapore
11.3.10 Vietnam
11.3.11 Rest of Asia Pacific
11.4 South America
11.4.1 Brazil
11.4.2 Argentina
11.4.3 Colombia
11.4.4 Chile
11.4.5 Peru
11.4.6 Rest of South America
11.5 Rest of the World (RoW)
11.5.1 Middle East
11.5.1.1 Saudi Arabia
11.5.1.2 United Arab Emirates
11.5.1.3 Qatar
11.5.1.4 Israel
11.5.1.5 Rest of Middle East
11.5.2 Africa
11.5.2.1 South Africa
11.5.2.2 Egypt
11.5.2.3 Morocco
11.5.2.4 Rest of Africa
12 Strategic Market Intelligence
12.1 Industry Value Network and Supply Chain Assessment
12.2 White-Space and Opportunity Mapping
12.3 Product Evolution and Market Life Cycle Analysis
12.4 Channel, Distributor, and Go-to-Market Assessment
13 Industry Developments and Strategic Initiatives
13.1 Mergers and Acquisitions
13.2 Partnerships, Alliances, and Joint Ventures
13.3 New Product Launches and Certifications
13.4 Capacity Expansion and Investments
13.5 Other Strategic Initiatives
14 Company Profiles
14.1 Syensqo
14.2 Toray Industries
14.3 Hexcel Corporation
14.4 Teijin Limited
14.5 Mitsubishi Chemical Group
14.6 ATI
14.7 Alcoa Corporation
14.8 Constellium
14.9 Howmet Aerospace
14.10 VSMPO-AVISMA Corporation
14.11 SGL Carbon
14.12 Carpenter Technology Corporation
14.13 Precision Castparts Corp.
14.14 TIMET
14.15 Kobe Steel
14.16 Materion Corporation
14.17 Huntsman International
14.18 Victrex
List of Tables
1 Global Aerospace Materials Market Outlook, By Region (2023-2034) ($MN)
2 Global Aerospace Materials Market Outlook, By Material Type (2023-2034) ($MN)
3 Global Aerospace Materials Market Outlook, By Aluminum Alloys (2023-2034) ($MN)
4 Global Aerospace Materials Market Outlook, By Titanium Alloys (2023-2034) ($MN)
5 Global Aerospace Materials Market Outlook, By Steel Alloys (2023-2034) ($MN)
6 Global Aerospace Materials Market Outlook, By Superalloys (2023-2034) ($MN)
7 Global Aerospace Materials Market Outlook, By Magnesium Alloys (2023-2034) ($MN)
8 Global Aerospace Materials Market Outlook, By Polymer Materials (2023-2034) ($MN)
9 Global Aerospace Materials Market Outlook, By Ceramic Materials (2023-2034) ($MN)
10 Global Aerospace Materials Market Outlook, By Composite Materials (2023-2034) ($MN)
11 Global Aerospace Materials Market Outlook, By Composite Type (2023-2034) ($MN)
12 Global Aerospace Materials Market Outlook, By Carbon Fiber Reinforced Polymer (2023-2034) ($MN)
13 Global Aerospace Materials Market Outlook, By Glass Fiber Reinforced Polymer (2023-2034) ($MN)
14 Global Aerospace Materials Market Outlook, By Aramid Fiber Reinforced Polymer (2023-2034) ($MN)
15 Global Aerospace Materials Market Outlook, By Ceramic Matrix Composites (2023-2034) ($MN)
16 Global Aerospace Materials Market Outlook, By Other Composite Materials (2023-2034) ($MN)
17 Global Aerospace Materials Market Outlook, By Aerospace Vehicle Type (2023-2034) ($MN)
18 Global Aerospace Materials Market Outlook, By Commercial Aircraft (2023-2034) ($MN)
19 Global Aerospace Materials Market Outlook, By Military Aircraft (2023-2034) ($MN)
20 Global Aerospace Materials Market Outlook, By Business Jets (2023-2034) ($MN)
21 Global Aerospace Materials Market Outlook, By General Aviation Aircraft (2023-2034) ($MN)
22 Global Aerospace Materials Market Outlook, By Helicopters (2023-2034) ($MN)
23 Global Aerospace Materials Market Outlook, By Unmanned Aerial Vehicles (UAVs) (2023-2034) ($MN)
24 Global Aerospace Materials Market Outlook, By Spacecraft & Launch Vehicles (2023-2034) ($MN)
25 Global Aerospace Materials Market Outlook, By Manufacturing Process (2023-2034) ($MN)
26 Global Aerospace Materials Market Outlook, By Casting (2023-2034) ($MN)
27 Global Aerospace Materials Market Outlook, By Forging (2023-2034) ($MN)
28 Global Aerospace Materials Market Outlook, By Rolling (2023-2034) ($MN)
29 Global Aerospace Materials Market Outlook, By Extrusion (2023-2034) ($MN)
30 Global Aerospace Materials Market Outlook, By Machining (2023-2034) ($MN)
31 Global Aerospace Materials Market Outlook, By Additive Manufacturing (2023-2034) ($MN)
32 Global Aerospace Materials Market Outlook, By Composite Layup & Curing (2023-2034) ($MN)
33 Global Aerospace Materials Market Outlook, By Powder Metallurgy (2023-2034) ($MN)
34 Global Aerospace Materials Market Outlook, By Application (2023-2034) ($MN)
35 Global Aerospace Materials Market Outlook, By Airframes & Structural Components (2023-2034) ($MN)
36 Global Aerospace Materials Market Outlook, By Engine & Propulsion Components (2023-2034) ($MN)
37 Global Aerospace Materials Market Outlook, By Aircraft Interiors (2023-2034) ($MN)
38 Global Aerospace Materials Market Outlook, By Landing Gear Components (2023-2034) ($MN)
39 Global Aerospace Materials Market Outlook, By Flight Control Components (2023-2034) ($MN)
40 Global Aerospace Materials Market Outlook, By Electrical & Electronic Components (2023-2034) ($MN)
41 Global Aerospace Materials Market Outlook, By Windows & Windshields (2023-2034) ($MN)
42 Global Aerospace Materials Market Outlook, By Spacecraft Structures (2023-2034) ($MN)
43 Global Aerospace Materials Market Outlook, By End User (2023-2034) ($MN)
44 Global Aerospace Materials Market Outlook, By Aerospace Original Equipment Manufacturers (2023-2034) ($MN)
45 Global Aerospace Materials Market Outlook, By Maintenance, Repair & Overhaul Providers (2023-2034) ($MN)
46 Global Aerospace Materials Market Outlook, By Defense Aerospace OEMs & Contractors (2023-2034) ($MN)
47 Global Aerospace Materials Market Outlook, By Space Agencies & Commercial Space Companies (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
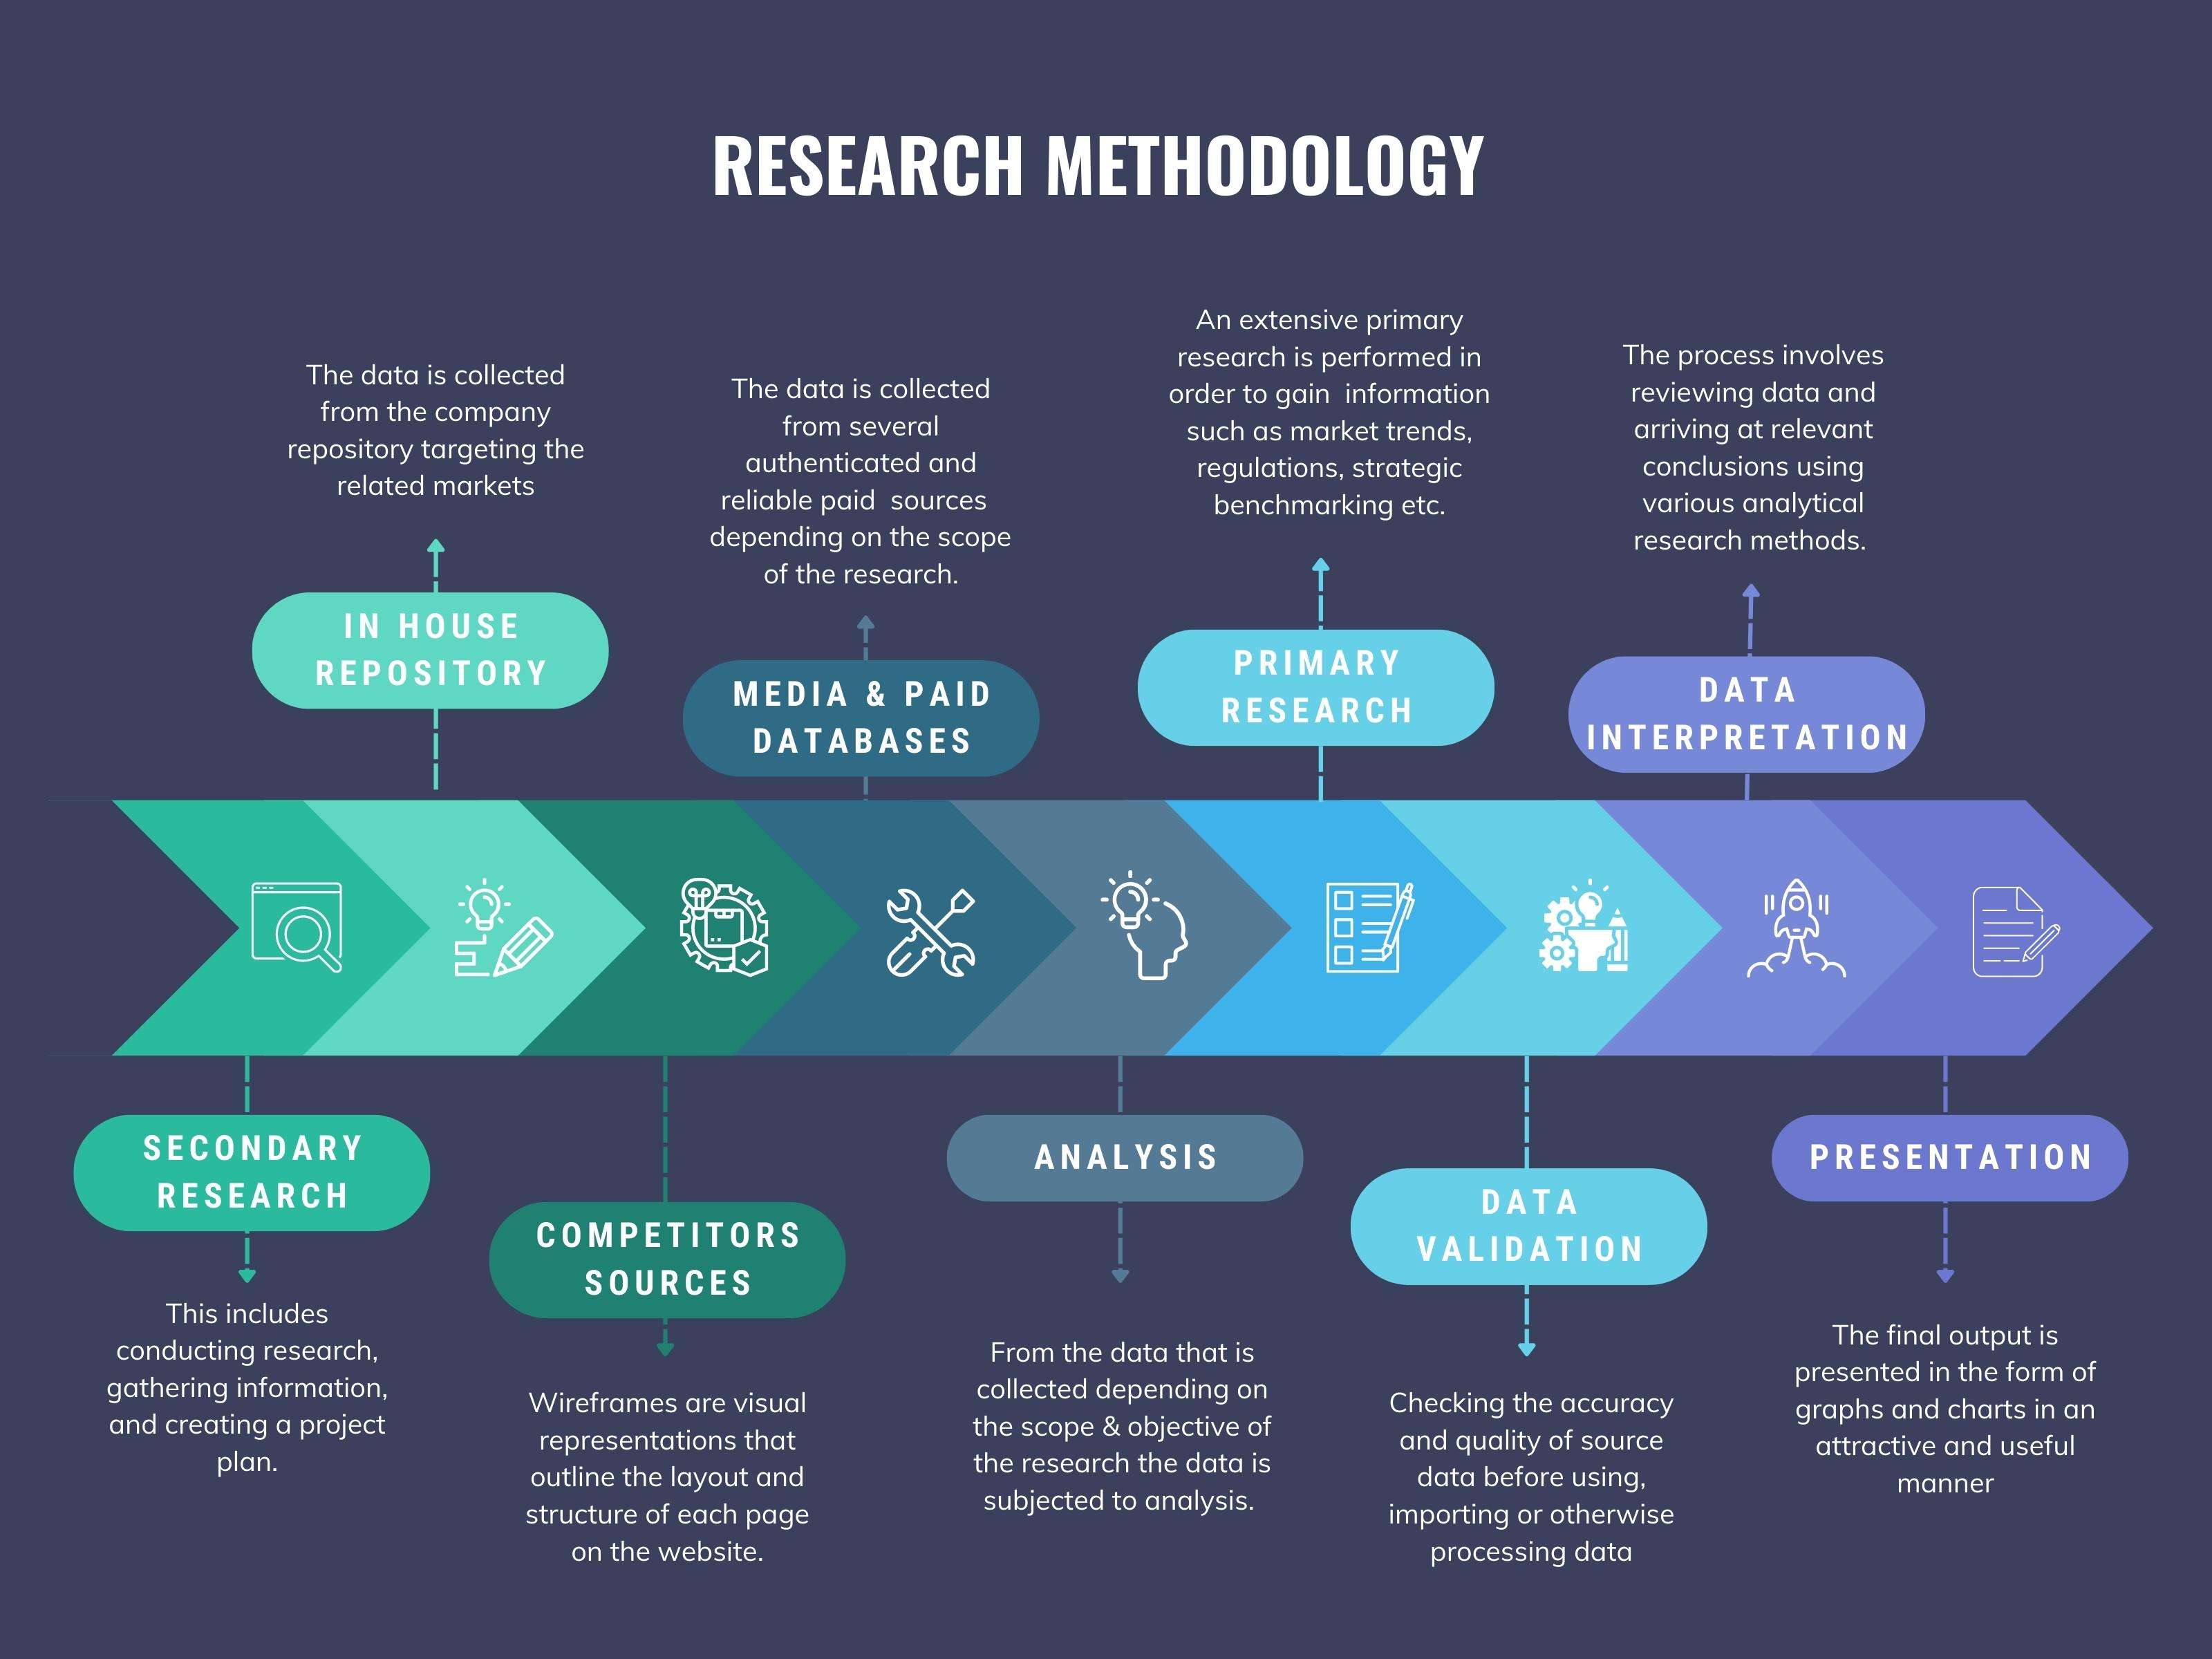
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.