Aerospace Structures Market
Aerospace Structures Market Forecasts To 2034 - Global Analysis By Material Type (Aluminum Alloys, Titanium Alloys, Steel Alloys, Superalloys, Magnesium Alloys, Polymer Materials, Ceramic Materials and Composite Materials), Composite Type, Aerospace Vehicle Type, Manufacturing Process, Application, End User and By Geography
Market Dynamics:
Driver:
Increasing demand for lightweight and fuel-efficient aerospace structures, Growing demand for lightweight, durable, and fuel-efficient aircraft is driving the Aerospace Structures Market. Commercial aircraft manufacturers are increasingly adopting advanced structural designs and materials to reduce aircraft weight, improve aerodynamic performance, and lower operating costs. Military aircraft require high-strength structures capable of withstanding demanding flight conditions and mission requirements. Expanding aircraft production and fleet modernization programs are encouraging investment in advanced fuselage, wing, and structural assembly technologies. Additionally, increasing use of carbon fiber reinforced composites and precision manufacturing techniques is improving structural performance, fatigue resistance, and operational efficiency across aerospace platforms.
Restraint:
High manufacturing costs and stringent aerospace certification requirements
High manufacturing costs and complex certification requirements represent significant restraints on the Aerospace Structures Market. Aerospace structural components must satisfy demanding safety, fatigue resistance, durability, and material performance standards. Manufacturing advanced composite structures, precision-machined metallic components, and large integrated assemblies requires substantial investment in specialized equipment, tooling, and skilled personnel. Extensive testing and certification processes further increase development costs and production timelines. Additionally, challenges associated with composite repairability, material traceability, and compatibility with existing aircraft designs can limit adoption. Long qualification cycles and high capital requirements also create barriers for smaller aerospace suppliers.
Opportunity:
Expansion of advanced composites and next-generation aircraft manufacturing
The increasing development of next-generation aircraft and advanced aerospace materials is creating substantial opportunities for aerospace structure manufacturers. Aircraft producers are investing in lightweight composite structures, thermoplastic materials, and innovative manufacturing processes to improve efficiency and reduce lifecycle costs. Advancements in automated fiber placement, additive manufacturing, resin transfer molding, and adhesive bonding are supporting more efficient production of complex structural components. Growing demand for advanced air mobility vehicles and unmanned aircraft is encouraging development of specialized lightweight structures. Furthermore, increasing aircraft production rates and supply chain localization initiatives are creating opportunities for structural component suppliers and manufacturing technology providers.
Threat:
Raw material shortages and aerospace supply chain disruptions
Raw material shortages, supply chain disruptions, and increasing production complexity present significant threats to the Aerospace Structures Market. Manufacturers depend on specialized aluminum, titanium, carbon fiber, resins, and precision-engineered components that may have limited qualified supply sources. Disruptions in material availability can delay structural manufacturing and aircraft assembly schedules. Aerospace suppliers must also address fluctuating material costs, geopolitical restrictions, and stringent quality requirements. Additionally, shortages of skilled manufacturing personnel and challenges in scaling composite production may constrain output. Changing aircraft production schedules and evolving certification standards can further increase operational uncertainty and financial pressure.
Covid-19 Impact:
The COVID-19 pandemic affected the Aerospace Structures Market through reduced commercial aircraft production, delayed aircraft deliveries, and disruptions in aerospace manufacturing supply chains. Aircraft manufacturers postponed selected production and expansion programs as passenger demand declined and airline financial pressures increased. Workforce restrictions, transportation delays, and material shortages also affected structural component fabrication and assembly operations. However, military aviation programs and government aerospace initiatives continued supporting demand for critical structural components. During the recovery period, increasing air travel, renewed aircraft orders, and investment in advanced manufacturing capabilities contributed to improving market conditions and aerospace structural production.
The fuselage structures segment is expected to be the largest during the forecast period
The fuselage structures segment is expected to account for the largest market share during the forecast period, supported by its essential role in aircraft structural integrity, passenger accommodation, and overall airframe performance. Fuselage structures incorporate complex load-bearing assemblies, frames, stringers, skin panels, and pressure-resistant sections that require high manufacturing precision. These components are required across commercial, military, business, and unmanned aircraft platforms, creating consistent demand from aerospace manufacturers. Advancements in lightweight composite fuselage construction, automated assembly, and precision fabrication are improving manufacturing efficiency. Increasing aircraft production and fleet modernization are further supporting segment expansion.
The advanced thermoplastic composites segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the advanced thermoplastic composites segment is anticipated to witness the highest growth rate due to increasing demand for lightweight, recyclable, and efficient aerospace structural materials. Thermoplastic composites offer advantages including improved impact resistance, rapid processing capabilities, and potential for welding and automated assembly. Aircraft manufacturers are exploring these materials for structural panels, brackets, interior support components, and selected load-bearing applications. Advancements in automated manufacturing, material processing, and joining technologies are supporting development. However, high material costs, qualification requirements, and challenges in scaling production remain important technical considerations for widespread adoption.
Region with largest share:
During the forecast period, North America is expected to hold the largest market share, supported by established aerospace manufacturing capabilities and substantial investments in aircraft production and structural technologies. The United States hosts major aircraft manufacturers, aerospace structural component suppliers, defense contractors, and advanced materials companies developing sophisticated airframe assemblies. Strong demand for commercial aircraft production, military aviation modernization, and advanced aerospace manufacturing supports regional growth. Expanding investment in automated production and lightweight composite structures further strengthens market opportunities. Additionally, extensive aerospace engineering expertise, research infrastructure, and established supplier networks support regional leadership.
Region with highest CAGR:
Over the forecast period, Asia Pacific is anticipated to exhibit the highest CAGR due to expanding commercial aviation activities, increasing aircraft production, and growing investments in aerospace manufacturing infrastructure. China, India, Japan, South Korea, and Southeast Asian countries are strengthening domestic aerospace supply chains to support rising passenger traffic and aircraft demand. Increasing investment in aircraft structural manufacturing, composite material production, and precision engineering is encouraging regional development. Government initiatives supporting domestic aircraft programs and aerospace industrial capabilities are creating opportunities for structural component manufacturers. Additionally, expanding international manufacturing partnerships are expected to support long-term market growth.
Key players in the market
Some of the key players in the Aerospace Structures Market include Airbus SE, The Boeing Company, GKN Aerospace, Leonardo S.p.A., Mitsubishi Heavy Industries, Ltd., Saab AB, FACC AG, Kawasaki Heavy Industries, Ltd., Daher, Collins Aerospace, Hexcel Corporation, Ducommun Incorporated, Magellan Aerospace Corporation, Tata Advanced Systems Limited, Mahindra Aerostructures Private Limited, Kineco Aerospace & Defence, Aernnova Aerospace, and Sonaca Group.
Key Developments:
In February 2026, Tata Advanced Systems Limited inaugurated India's first private-sector helicopter final assembly line for the Airbus H125 at Vemagal, Karnataka, in collaboration with Airbus SE. The facility supports manufacturing, integration, testing, and maintenance activities for the H125 helicopter, strengthening India's domestic aerospace production capabilities. The initiative represents an important expansion of the country's structural manufacturing and aircraft assembly infrastructure. It also supports the development of local aerospace suppliers, specialized manufacturing expertise, and advanced industrial capabilities required for future commercial and military rotorcraft programs.
In August 2025, Mahindra Aerostructures Private Limited secured a contract from Airbus Helicopters to manufacture the main fuselage of the H125 helicopter. The agreement expands the companies' existing manufacturing partnership and strengthens India's participation in international aerospace structural supply chains. Industrialization activities are being undertaken at Mahindra's Bengaluru facility, with the first fuselage delivery targeted for 2027. The contract follows an earlier agreement covering H130 helicopter fuselage manufacturing and highlights increasing demand for precision-engineered aerospace structures, localized production capabilities, and long-term partnerships between aircraft manufacturers and specialized structural component suppliers.
In June 2025, FACC AG announced new aerospace manufacturing agreements during the Paris Air Show, including expanded cooperation with international partners and a multi-year supply chain agreement with Kineco Aerospace & Defence. The partnership focuses on sourcing composite components for commercial aircraft programs and includes technical alignment, qualification, and operational cooperation activities. FACC also reported an expansion of its order backlog to more than $6 billion. These developments strengthen the company's international manufacturing network and support increasing demand for lightweight composite structures, advanced aerostructure assemblies, and resilient aerospace supply chains.
Structure Types Covered:
• Fuselage Structures
• Wing Structures
• Empennage and Tail Structures
• Landing Gear Support Structures
• Engine Mount and Pylon Structures
• Nacelle Structures
• Flight Control Surface Structures
• Cabin and Interior Support Structures
Materials Covered:
• Aluminum Alloys
• Titanium Alloys
• Steel Alloys
• Carbon Fiber Reinforced Polymer Composites
• Glass Fiber Reinforced Polymer Composites
• Advanced Thermoplastic Composites
• Ceramic Matrix Composites
• Metal Matrix Composites
Manufacturing Processes Covered:
• Machining and Precision Fabrication
• Sheet Metal Forming
• Forging and Casting
• Extrusion and Roll Forming
• Resin Transfer Molding
• Additive Manufacturing
• Adhesive Bonding
Structural Configurations Covered:
• Monocoque Structures
• Semi-Monocoque Structures
• Truss Structures
• Sandwich Panel Structures
• Stiffened Skin Structures
Production Stages Covered:
• Structural Component Fabrication
• Structural Subassembly Manufacturing
• Final Structural Assembly and Integration
• Replacement and Spare Structural Components
Applications Covered:
• Commercial Aviation
• Military Aviation
• Business and General Aviation
• Cargo and Freight Aviation
• Unmanned Aviation
• Advanced Air Mobility
End Users Covered:
• Commercial Aircraft Manufacturers
• Military Aircraft Manufacturers
• Business and General Aviation Manufacturers
• Helicopter and Rotorcraft Manufacturers
• Unmanned Aircraft Manufacturers
• Aerospace Structural Component Suppliers
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Aerospace Structures Market, By Structure Type
5.1 Fuselage Structures
5.2 Wing Structures
5.3 Empennage and Tail Structures
5.4 Landing Gear Support Structures
5.5 Engine Mount and Pylon Structures
5.6 Nacelle Structures
5.7 Flight Control Surface Structures
5.8 Cabin and Interior Support Structures
6 Global Aerospace Structures Market, By Material
6.1 Aluminum Alloys
6.2 Titanium Alloys
6.3 Steel Alloys
6.4 Carbon Fiber Reinforced Polymer Composites
6.5 Glass Fiber Reinforced Polymer Composites
6.6 Advanced Thermoplastic Composites
6.7 Ceramic Matrix Composites
6.8 Metal Matrix Composites
7 Global Aerospace Structures Market, By Manufacturing Process
7.1 Machining and Precision Fabrication
7.2 Sheet Metal Forming
7.3 Forging and Casting
7.4 Extrusion and Roll Forming
7.5 Resin Transfer Molding
7.6 Additive Manufacturing
7.7 Adhesive Bonding
8 Global Aerospace Structures Market, By Structural Configuration
8.1 Monocoque Structures
8.2 Semi-Monocoque Structures
8.3 Truss Structures
8.4 Sandwich Panel Structures
8.5 Stiffened Skin Structures
9 Global Aerospace Structures Market, By Production Stage
9.1 Structural Component Fabrication
9.2 Structural Subassembly Manufacturing
9.3 Final Structural Assembly and Integration
9.4 Replacement and Spare Structural Components
10 Global Aerospace Structures Market, By Application
10.1 Commercial Aviation
10.2 Military Aviation
10.3 Business and General Aviation
10.4 Cargo and Freight Aviation
10.5 Unmanned Aviation
10.6 Advanced Air Mobility
11 Global Aerospace Structures Market, By End User
11.1 Commercial Aircraft Manufacturers
11.2 Military Aircraft Manufacturers
11.3 Business and General Aviation Manufacturers
11.4 Helicopter and Rotorcraft Manufacturers
11.5 Unmanned Aircraft Manufacturers
11.6 Aerospace Structural Component Suppliers
12 Global Aerospace Structures Market, By Geography
12.1 North America
12.1.1 United States
12.1.2 Canada
12.1.3 Mexico
12.2 Europe
12.2.1 United Kingdom
12.2.2 Germany
12.2.3 France
12.2.4 Italy
12.2.5 Spain
12.2.6 Netherlands
12.2.7 Belgium
12.2.8 Sweden
12.2.9 Switzerland
12.2.10 Poland
12.2.11 Rest of Europe
12.3 Asia Pacific
12.3.1 China
12.3.2 Japan
12.3.3 India
12.3.4 South Korea
12.3.5 Australia
12.3.6 Indonesia
12.3.7 Thailand
12.3.8 Malaysia
12.3.9 Singapore
12.3.10 Vietnam
12.3.11 Rest of Asia Pacific
12.4 South America
12.4.1 Brazil
12.4.2 Argentina
12.4.3 Colombia
12.4.4 Chile
12.4.5 Peru
12.4.6 Rest of South America
12.5 Rest of the World (RoW)
12.5.1 Middle East
12.5.1.1 Saudi Arabia
12.5.1.2 United Arab Emirates
12.5.1.3 Qatar
12.5.1.4 Israel
12.5.1.5 Rest of Middle East
12.5.2 Africa
12.5.2.1 South Africa
12.5.2.2 Egypt
12.5.2.3 Morocco
12.5.2.4 Rest of Africa
13 Strategic Market Intelligence
13.1 Industry Value Network and Supply Chain Assessment
13.2 White-Space and Opportunity Mapping
13.3 Product Evolution and Market Life Cycle Analysis
13.4 Channel, Distributor, and Go-to-Market Assessment
14 Industry Developments and Strategic Initiatives
14.1 Mergers and Acquisitions
14.2 Partnerships, Alliances, and Joint Ventures
14.3 New Product Launches and Certifications
14.4 Capacity Expansion and Investments
14.5 Other Strategic Initiatives
15 Company Profiles
15.1 Airbus SE
15.2 The Boeing Company
15.3 GKN Aerospace
15.4 Leonardo S.p.A.
15.5 Mitsubishi Heavy Industries, Ltd.
15.6 Saab AB
15.7 FACC AG
15.8 Kawasaki Heavy Industries, Ltd.
15.9 Daher
15.10 Collins Aerospace
15.11 Hexcel Corporation
15.12 Ducommun Incorporated
15.13 Magellan Aerospace Corporation
15.14 Tata Advanced Systems Limited
15.15 Mahindra Aerostructures Private Limited
15.16 Kineco Aerospace & Defence
15.17 Aernnova Aerospace
15.18 Sonaca Group
List of Tables
1 Global Aerospace Structures Market Outlook, By Region (2023-2034) ($MN)
2 Global Aerospace Structures Market Outlook, By Structure Type (2023-2034) ($MN)
3 Global Aerospace Structures Market Outlook, By Fuselage Structures (2023-2034) ($MN)
4 Global Aerospace Structures Market Outlook, By Wing Structures (2023-2034) ($MN)
5 Global Aerospace Structures Market Outlook, By Empennage and Tail Structures (2023-2034) ($MN)
6 Global Aerospace Structures Market Outlook, By Landing Gear Support Structures (2023-2034) ($MN)
7 Global Aerospace Structures Market Outlook, By Engine Mount and Pylon Structures (2023-2034) ($MN)
8 Global Aerospace Structures Market Outlook, By Nacelle Structures (2023-2034) ($MN)
9 Global Aerospace Structures Market Outlook, By Flight Control Surface Structures (2023-2034) ($MN)
10 Global Aerospace Structures Market Outlook, By Cabin and Interior Support Structures (2023-2034) ($MN)
11 Global Aerospace Structures Market Outlook, By Material (2023-2034) ($MN)
12 Global Aerospace Structures Market Outlook, By Aluminum Alloys (2023-2034) ($MN)
13 Global Aerospace Structures Market Outlook, By Titanium Alloys (2023-2034) ($MN)
14 Global Aerospace Structures Market Outlook, By Steel Alloys (2023-2034) ($MN)
15 Global Aerospace Structures Market Outlook, By Carbon Fiber Reinforced Polymer Composites (2023-2034) ($MN)
16 Global Aerospace Structures Market Outlook, By Glass Fiber Reinforced Polymer Composites (2023-2034) ($MN)
17 Global Aerospace Structures Market Outlook, By Advanced Thermoplastic Composites (2023-2034) ($MN)
18 Global Aerospace Structures Market Outlook, By Ceramic Matrix Composites (2023-2034) ($MN)
19 Global Aerospace Structures Market Outlook, By Metal Matrix Composites (2023-2034) ($MN)
20 Global Aerospace Structures Market Outlook, By Manufacturing Process (2023-2034) ($MN)
21 Global Aerospace Structures Market Outlook, By Machining and Precision Fabrication (2023-2034) ($MN)
22 Global Aerospace Structures Market Outlook, By Sheet Metal Forming (2023-2034) ($MN)
23 Global Aerospace Structures Market Outlook, By Forging and Casting (2023-2034) ($MN)
24 Global Aerospace Structures Market Outlook, By Extrusion and Roll Forming (2023-2034) ($MN)
25 Global Aerospace Structures Market Outlook, By Resin Transfer Molding (2023-2034) ($MN)
26 Global Aerospace Structures Market Outlook, By Additive Manufacturing (2023-2034) ($MN)
27 Global Aerospace Structures Market Outlook, By Adhesive Bonding (2023-2034) ($MN)
28 Global Aerospace Structures Market Outlook, By Structural Configuration (2023-2034) ($MN)
29 Global Aerospace Structures Market Outlook, By Monocoque Structures (2023-2034) ($MN)
30 Global Aerospace Structures Market Outlook, By Semi-Monocoque Structures (2023-2034) ($MN)
31 Global Aerospace Structures Market Outlook, By Truss Structures (2023-2034) ($MN)
32 Global Aerospace Structures Market Outlook, By Sandwich Panel Structures (2023-2034) ($MN)
33 Global Aerospace Structures Market Outlook, By Stiffened Skin Structures (2023-2034) ($MN)
34 Global Aerospace Structures Market Outlook, By Production Stage (2023-2034) ($MN)
35 Global Aerospace Structures Market Outlook, By Structural Component Fabrication (2023-2034) ($MN)
36 Global Aerospace Structures Market Outlook, By Structural Subassembly Manufacturing (2023-2034) ($MN)
37 Global Aerospace Structures Market Outlook, By Final Structural Assembly and Integration (2023-2034) ($MN)
38 Global Aerospace Structures Market Outlook, By Replacement and Spare Structural Components (2023-2034) ($MN)
39 Global Aerospace Structures Market Outlook, By Application (2023-2034) ($MN)
40 Global Aerospace Structures Market Outlook, By Commercial Aviation (2023-2034) ($MN)
41 Global Aerospace Structures Market Outlook, By Military Aviation (2023-2034) ($MN)
42 Global Aerospace Structures Market Outlook, By Business and General Aviation (2023-2034) ($MN)
43 Global Aerospace Structures Market Outlook, By Cargo and Freight Aviation (2023-2034) ($MN)
44 Global Aerospace Structures Market Outlook, By Unmanned Aviation (2023-2034) ($MN)
45 Global Aerospace Structures Market Outlook, By Advanced Air Mobility (2023-2034) ($MN)
46 Global Aerospace Structures Market Outlook, By End User (2023-2034) ($MN)
47 Global Aerospace Structures Market Outlook, By Commercial Aircraft Manufacturers (2023-2034) ($MN)
48 Global Aerospace Structures Market Outlook, By Military Aircraft Manufacturers (2023-2034) ($MN)
49 Global Aerospace Structures Market Outlook, By Business and General Aviation Manufacturers (2023-2034) ($MN)
50 Global Aerospace Structures Market Outlook, By Helicopter and Rotorcraft Manufacturers (2023-2034) ($MN)
51 Global Aerospace Structures Market Outlook, By Unmanned Aircraft Manufacturers (2023-2034) ($MN)
52 Global Aerospace Structures Market Outlook, By Aerospace Structural Component Suppliers (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
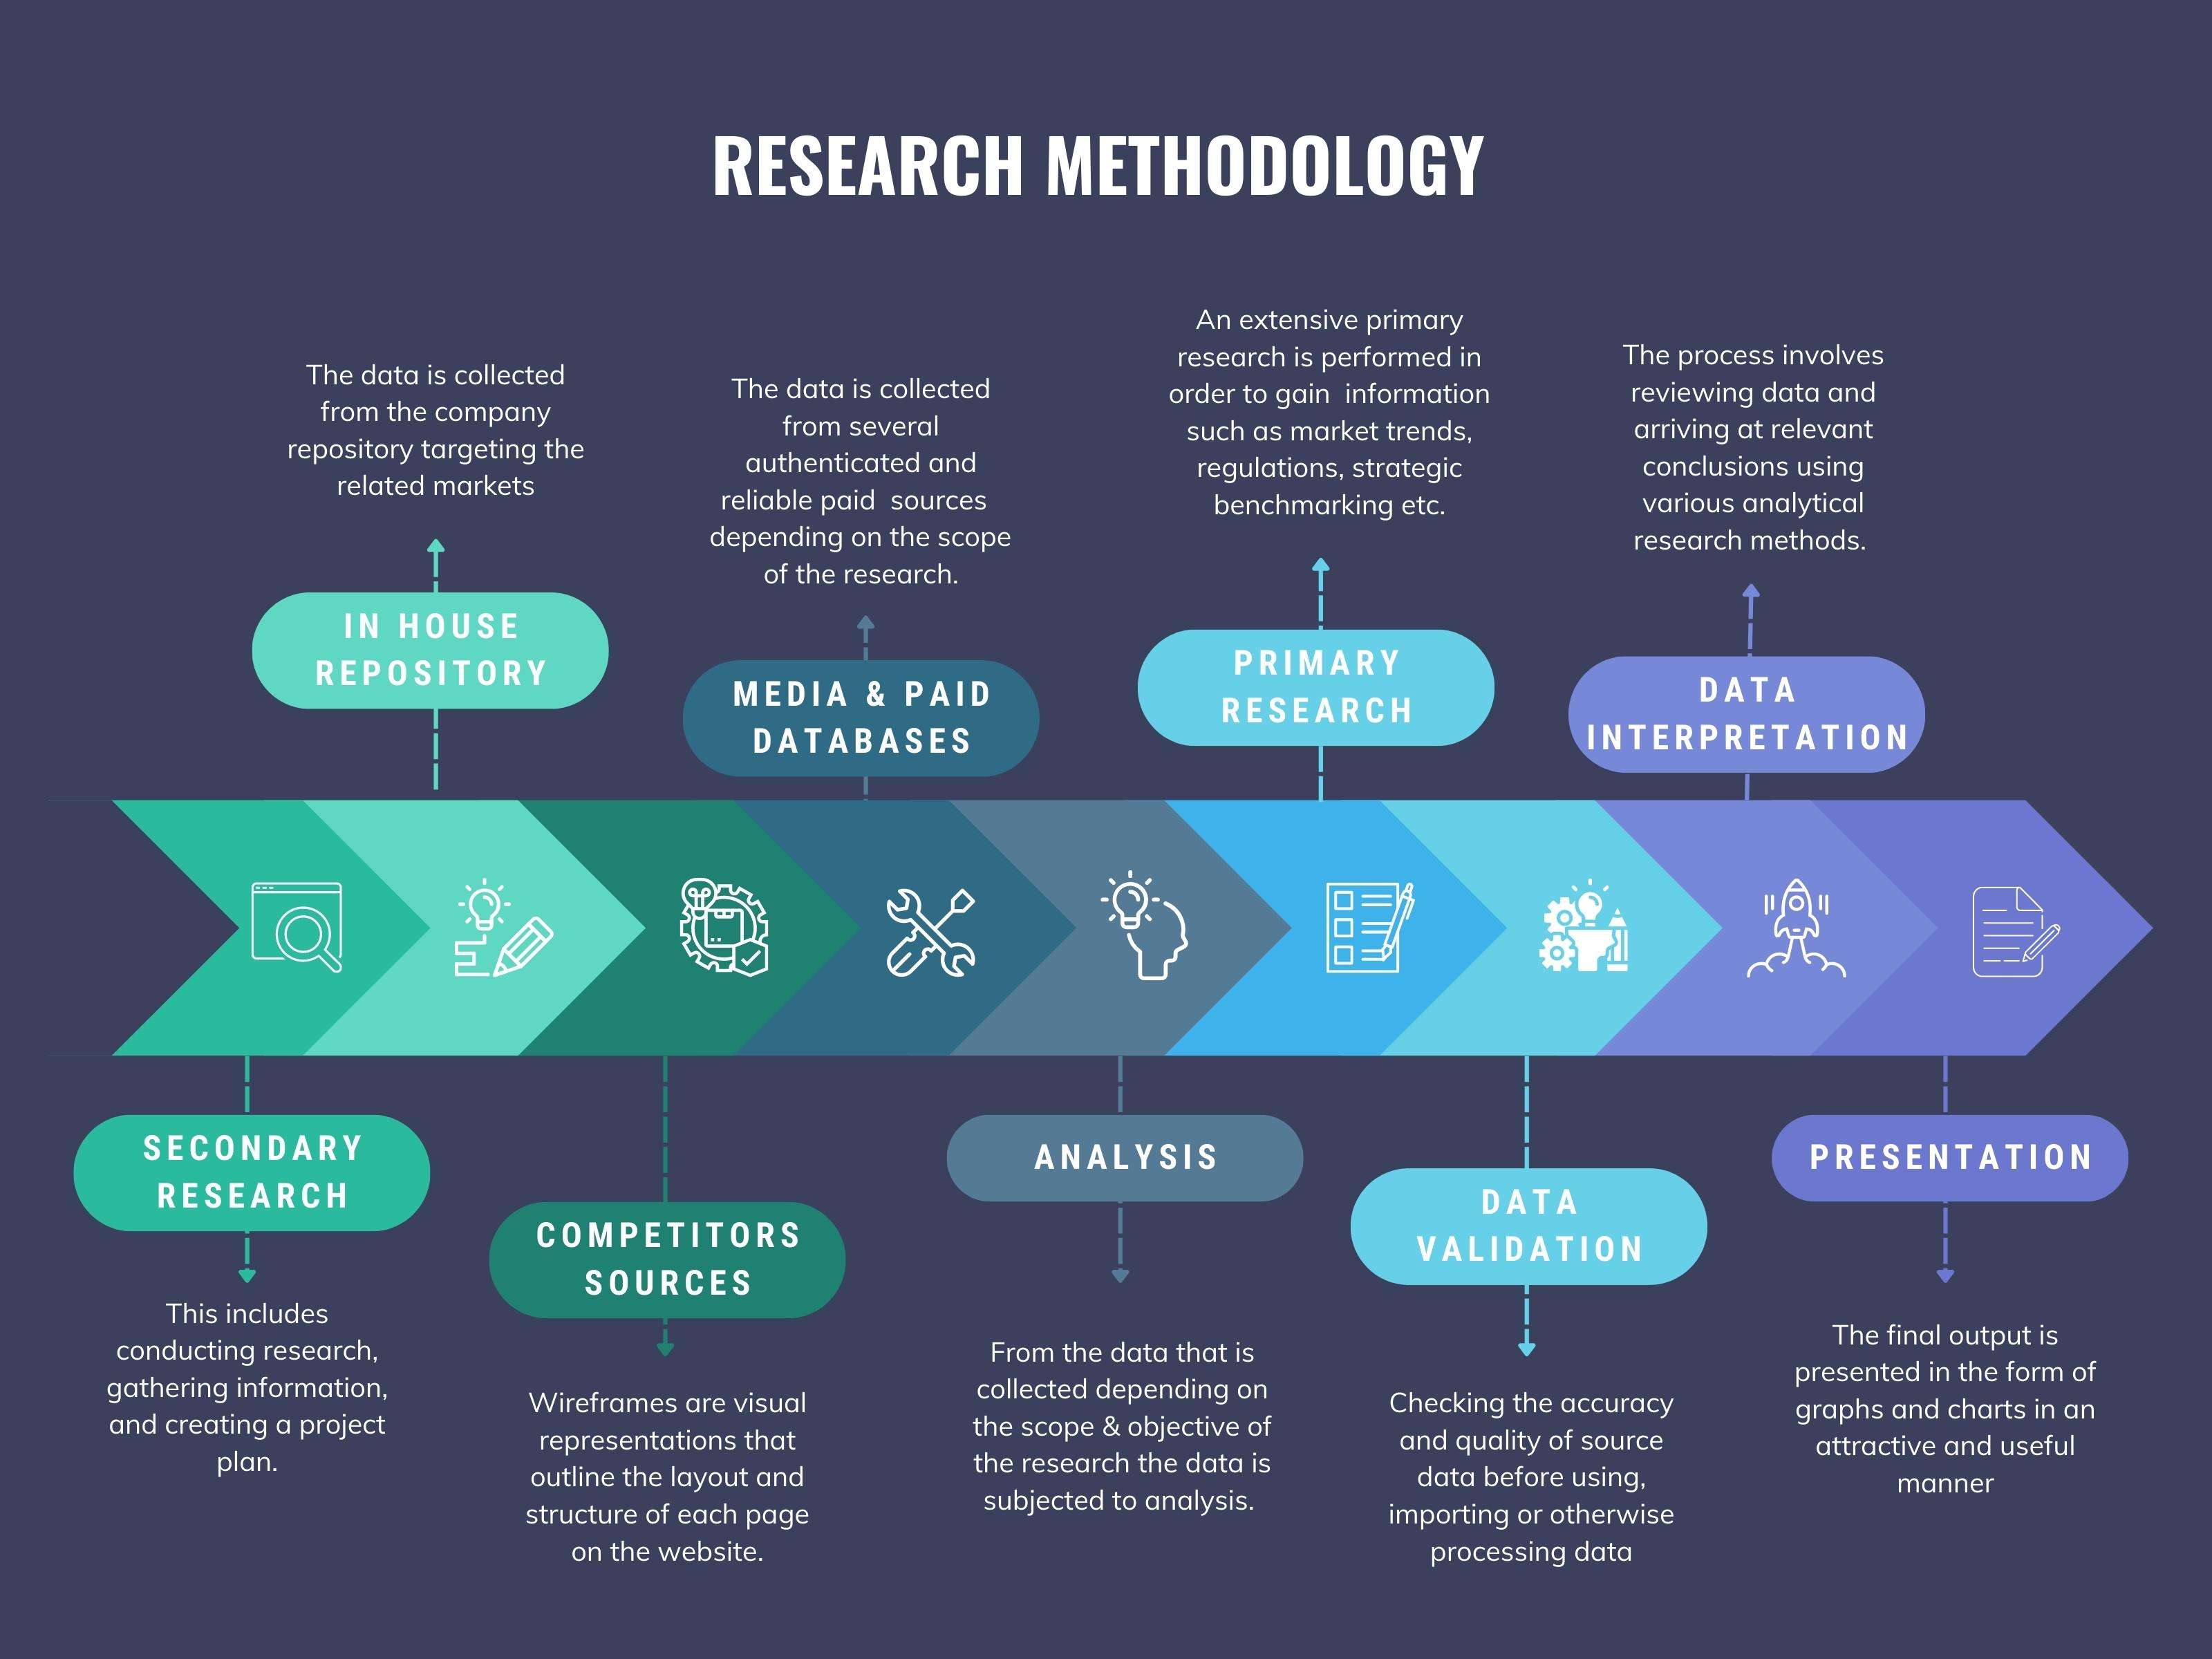
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.