Automotive Cylindrical Cell Market
Automotive Cylindrical Cell Market Forecasts to 2034 – Global Analysis By Cell Format (18650 Cells, 21700 Cells, 4680 and Large-Format Cylindrical Cells, and Other Standard and Custom Formats), Battery Chemistry, Application, Vehicle Type, Cell Diameter Class, and By Geography
Market Dynamics:
Driver:
Automated cell production and platform demand support format expansion
Cylindrical cells offer a repeatable geometry suited to highly automated manufacturing and quality inspection. Automakers with platforms designed around the format create recurring demand, while larger cells offer an opportunity to reduce the number of individual units and connections in a pack. These benefits must be balanced against heat removal and current distribution, but they provide a clear engineering path for continued development. Cell producers can also build on established process knowledge when introducing new diameters or heights. Demand is strongest where the complete pack architecture makes effective use of the format's manufacturing and mechanical characteristics.
Restraint:
Larger cells increase the difficulty of managing internal heat and uniformity
Increasing cell dimensions changes the distance over which heat and current must travel, making internal design and cooling more demanding. Electrode consistency, winding accuracy, electrolyte wetting, and formation become critical to achieving reliable output. A large cell also stores more energy in a single enclosure, requiring careful vent and fault-propagation design at pack level. Manufacturers cannot assume that a successful small format scales without additional development. Production ramps may involve yield challenges and extended qualification. Customers therefore assess a new cylindrical design against actual cycle performance and manufacturability, rather than treating fewer cells per pack as an automatic improvement.
Opportunity:
Direct pack integration can reduce assembly overhead
New cylindrical platforms create opportunities to coordinate cell connections, cooling, structural support, and monitoring within a direct-to-pack assembly. Automated welding and inspection can reduce the burden of handling many individual cells, while carefully designed grouping methods improve consistency. Suppliers of contact systems, adhesives, foams, and cooling components can participate alongside cell manufacturers. The opportunity is particularly attractive when a vehicle platform is developed around the battery layout from the beginning. Successful integration can improve usable space and manufacturing efficiency, but it must retain controlled venting, adequate isolation, and a practical response to damaged or defective cells.
Threat:
Prismatic and pouch alternatives compete for the same vehicle programs
Automakers can select other formats when they offer better packaging, fewer connections, or a preferred chemistry supply base. Advances in large prismatic cells and pouch-cell integration may narrow the advantages of a cylindrical design. Capacity investments also face the risk that customer programs are delayed or use less battery content than expected. A cell maker dependent on a small number of vehicle platforms can be particularly exposed. Maintaining competitiveness requires dependable ramp-up, cost control, and coordination with pack engineering. Format familiarity alone does not protect a supplier if another architecture better matches the customer's range, space, or sourcing priorities.
Covid-19 Impact:
The pandemic affected cylindrical-cell manufacturing through interruptions in equipment delivery, material supply, and vehicle production schedules. Factories also faced restrictions that complicated staffing and technical support during process changes. For new large-format programs, the disruption extended to pilot validation and the installation of specialized production lines. Demand recovery was uneven, making it difficult to align capacity expansion with customer launch dates. Manufacturers continued developing the format, but the period highlighted the need for reliable supply and flexible production planning. The effects were therefore different for established small-cell lines and emerging automotive designs still moving toward commercial qualification.
The 21700 Cells segment is expected to be the largest during the forecast period
21700 Cells is expected to retain the largest share over the forecast period because the format has an established automotive production base and accumulated qualification experience. It offers a familiar balance between individual-cell capacity, heat management, and pack assembly requirements. Customers using existing platforms can continue sourcing an approved format without redesigning the entire battery. Larger cells are expected to gain ground, but their ramps and vehicle integration take time. The segment outlook therefore reflects the commercial weight of operating programs and mature manufacturing, while recognizing that new platform introductions can progressively change the balance among cylindrical sizes.
The 4680 and Large-Format Cylindrical Cells segment is expected to have the highest CAGR during the forecast period
4680 and Large-Format Cylindrical Cells are anticipated to record the highest growth as new electric platforms adopt larger units and revised pack architectures. Their appeal includes fewer cells and connections for a given battery capacity, provided that internal current flow and cooling are adequately engineered. Growth starts from a smaller base and depends on successful production qualification. The market should distinguish between sampling, initial shipments, and sustained automotive output. Suppliers that demonstrate consistent yield and durability can benefit as customers move beyond development programs, while equipment and connection-system providers gain opportunities during the associated manufacturing transition.
Region with largest share:
Asia Pacific is expected to lead the market because the region combines established cylindrical-cell producers with extensive materials, equipment, and electronics supply chains. Manufacturing experience in Japan, South Korea, and China supports the development of new formats as well as continued output of existing ones. Regional vehicle and battery programs provide demand across several price and performance categories. The availability of specialized process knowledge helps suppliers manage coating, winding, formation, and quality control at scale. Continued leadership will depend on successful production ramps and customer diversification as automakers build more geographically distributed battery supply networks.
Region with highest CAGR:
Europe is anticipated to experience the highest growth as new vehicle platforms introduce cylindrical cells and direct pack assembly into regional manufacturing networks. This expands activity from a smaller installed base than the established Asian supply ecosystem. Battery assembly near vehicle plants creates demand for local integration expertise even where cells originate from specialist suppliers. Growth is tied to the actual launch and ramp-up of those programs, not simply to announced factory plans. Companies able to support welding, cooling, inspection, and traceability can benefit alongside cell makers as European manufacturers industrialize new cylindrical battery architectures.
Key players in the market
Some of the key players in the Automotive Cylindrical Cell Market include Panasonic Energy Co., Ltd., Contemporary Amperex Technology Co., Limited (CATL), Samsung SDI Co., Ltd., LG Energy Solution, Ltd., EVE Energy Co., Ltd., Tianjin Lishen Battery Joint-Stock Co., Ltd., Murata Manufacturing Co., Ltd., Tesla, Inc., BYD Company Limited, Gotion High-Tech Co., Ltd., Sunwoda Electronic Co., Ltd., SVOLT Energy Technology Co., Ltd., Amperex Technology Limited (ATL), and Toshiba Corporation.
Key Developments:
In October 2026, BMW announced the start of Gen6 high-voltage battery production in Shenyang using new cylindrical cells in a direct cell-to-pack arrangement. The milestone expanded its battery-assembly network and demonstrated industrial use of the format within a vehicle-specific pack manufacturing process.
In March 2025, Samsung SDI began supplying 46-series cylindrical battery modules to a U.S. customer. Initial applications were in micromobility, with electric-vehicle expansion planned. This parent cylindrical-battery development established an early production milestone without implying that the first shipments were already for passenger-car traction batteries.
In September 2024, Panasonic Energy announced completion of preparations for 4680 automotive-cell production at its revamped Wakayama facility. Production was to begin after final evaluation. The event marked manufacturing readiness and the establishment of a lead production site, rather than a claim of immediate full-volume customer deliveries.
Cell Formats Covered:
• 18650 Cells
• 21700 Cells
• 4680 and Large-Format Cylindrical Cells
• Other Standard and Custom Formats
Battery Chemistries Covered:
• Lithium Iron Phosphate (LFP)
• Nickel Manganese Cobalt (NMC)
• Nickel Cobalt Aluminum (NCA)
• Lithium Manganese-Rich and Other Chemistries
Applications Covered:
• Battery Electric Vehicles
• Hybrid and Plug-in Hybrid Vehicles
• Electric Commercial Vehicles
• Automotive Auxiliary and 12-Volt Systems
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles
• Heavy Commercial Vehicles
• Two-Wheelers and Specialty Vehicles
Cell Diameter Classes Covered:
• Small-Format Cylindrical Cells
• Medium-Format Cylindrical Cells
• Large-Format Cylindrical Cells
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
▪ Saudi Arabia
▪ United Arab Emirates
▪ Qatar
▪ Israel
▪ Rest of Middle East
o Africa
▪ South Africa
▪ Egypt
▪ Morocco
▪ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Cylindrical Cell Market, By Cell Format
5.1 18650 Cells
5.2 21700 Cells
5.3 4680 and Large-Format Cylindrical Cells
5.4 Other Standard and Custom Formats
6 Global Automotive Cylindrical Cell Market, By Battery Chemistry
6.1 Lithium Iron Phosphate (LFP)
6.2 Nickel Manganese Cobalt (NMC)
6.3 Nickel Cobalt Aluminum (NCA)
6.4 Lithium Manganese-Rich and Other Chemistries
7 Global Automotive Cylindrical Cell Market, By Application
7.1 Battery Electric Vehicles
7.2 Hybrid and Plug-in Hybrid Vehicles
7.3 Electric Commercial Vehicles
7.4 Automotive Auxiliary and 12-Volt Systems
8 Global Automotive Cylindrical Cell Market, By Vehicle Type
8.1 Passenger Cars
8.2 Light Commercial Vehicles
8.3 Heavy Commercial Vehicles
8.4 Two-Wheelers and Specialty Vehicles
9 Global Automotive Cylindrical Cell Market, By Cell Diameter Class
9.1 Small-Format Cylindrical Cells
9.2 Medium-Format Cylindrical Cells
9.3 Large-Format Cylindrical Cells
10 Global Automotive Cylindrical Cell Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Panasonic Energy Co., Ltd.
13.2 Contemporary Amperex Technology Co., Limited (CATL)
13.3 Samsung SDI Co., Ltd.
13.4 LG Energy Solution, Ltd.
13.5 EVE Energy Co., Ltd.
13.6 Tianjin Lishen Battery Joint-Stock Co., Ltd.
13.7 Murata Manufacturing Co., Ltd.
13.8 Tesla, Inc.
13.9 BYD Company Limited
13.10 Gotion High-Tech Co., Ltd.
13.11 Sunwoda Electronic Co., Ltd.
13.12 SVOLT Energy Technology Co., Ltd.
13.13 Amperex Technology Limited (ATL)
13.14 Toshiba Corporation
List of Tables
1 Global Automotive Cylindrical Cell Market Outlook, By Region (2023–2034) ($MN)
2 Global Automotive Cylindrical Cell Market Outlook, By Cell Format (2023–2034) ($MN)
3 Global Automotive Cylindrical Cell Market Outlook, By 18650 Cells (2023–2034) ($MN)
4 Global Automotive Cylindrical Cell Market Outlook, By 21700 Cells (2023–2034) ($MN)
5 Global Automotive Cylindrical Cell Market Outlook, By 4680 and Large-Format Cylindrical Cells (2023–2034) ($MN)
6 Global Automotive Cylindrical Cell Market Outlook, By Other Standard and Custom Formats (2023–2034) ($MN)
7 Global Automotive Cylindrical Cell Market Outlook, By Battery Chemistry (2023–2034) ($MN)
8 Global Automotive Cylindrical Cell Market Outlook, By Lithium Iron Phosphate (LFP) (2023–2034) ($MN)
9 Global Automotive Cylindrical Cell Market Outlook, By Nickel Manganese Cobalt (NMC) (2023–2034) ($MN)
10 Global Automotive Cylindrical Cell Market Outlook, By Nickel Cobalt Aluminum (NCA) (2023–2034) ($MN)
11 Global Automotive Cylindrical Cell Market Outlook, By Lithium Manganese-Rich and Other Chemistries (2023–2034) ($MN)
12 Global Automotive Cylindrical Cell Market Outlook, By Application (2023–2034) ($MN)
13 Global Automotive Cylindrical Cell Market Outlook, By Battery Electric Vehicles (2023–2034) ($MN)
14 Global Automotive Cylindrical Cell Market Outlook, By Hybrid and Plug-in Hybrid Vehicles (2023–2034) ($MN)
15 Global Automotive Cylindrical Cell Market Outlook, By Electric Commercial Vehicles (2023–2034) ($MN)
16 Global Automotive Cylindrical Cell Market Outlook, By Automotive Auxiliary and 12-Volt Systems (2023–2034) ($MN)
17 Global Automotive Cylindrical Cell Market Outlook, By Vehicle Type (2023–2034) ($MN)
18 Global Automotive Cylindrical Cell Market Outlook, By Passenger Cars (2023–2034) ($MN)
19 Global Automotive Cylindrical Cell Market Outlook, By Light Commercial Vehicles (2023–2034) ($MN)
20 Global Automotive Cylindrical Cell Market Outlook, By Heavy Commercial Vehicles (2023–2034) ($MN)
21 Global Automotive Cylindrical Cell Market Outlook, By Two-Wheelers and Specialty Vehicles (2023–2034) ($MN)
22 Global Automotive Cylindrical Cell Market Outlook, By Cell Diameter Class (2023–2034) ($MN)
23 Global Automotive Cylindrical Cell Market Outlook, By Small-Format Cylindrical Cells (2023–2034) ($MN)
24 Global Automotive Cylindrical Cell Market Outlook, By Medium-Format Cylindrical Cells (2023–2034) ($MN)
25 Global Automotive Cylindrical Cell Market Outlook, By Large-Format Cylindrical Cells (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
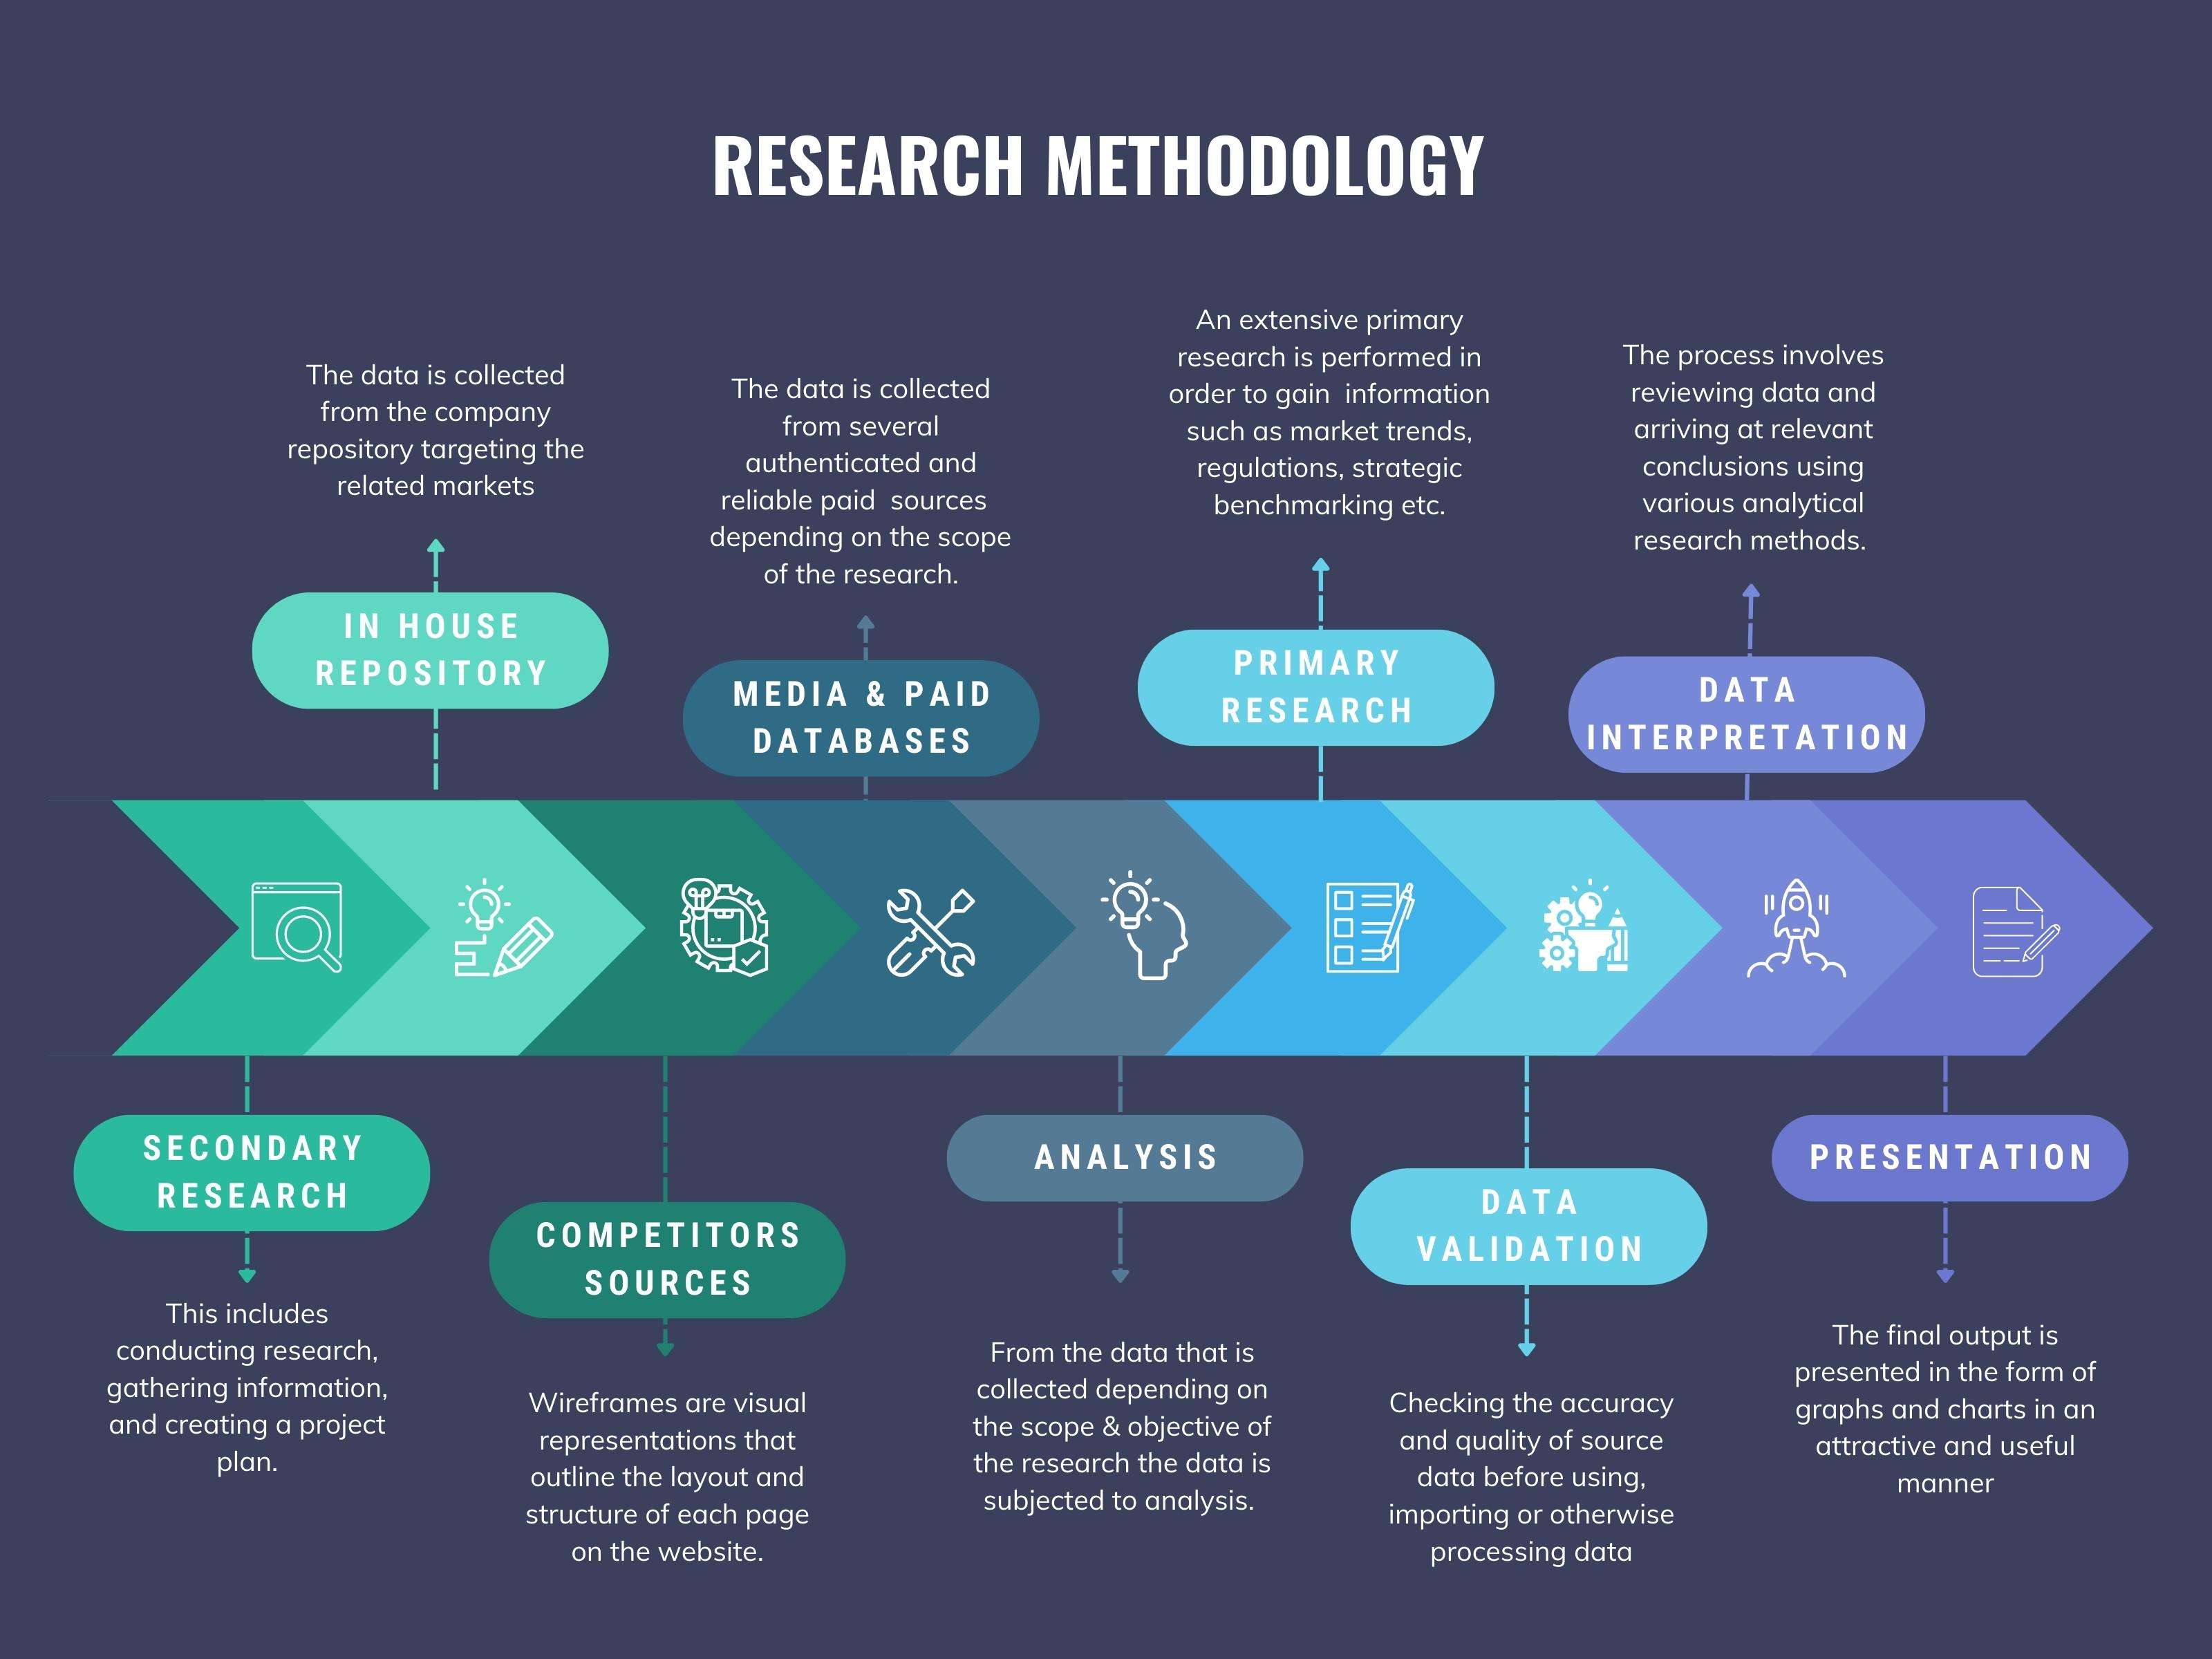
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.