Automotive Fleet Electrification Market
Automotive Fleet Electrification Market Forecasts To 2034 – Global Analysis By Vehicle Type (Passenger Cars, Two-Wheelers, Three-Wheelers, Light Commercial Vehicles, Medium Commercial Vehicles, Heavy Commercial Vehicles, Buses & Coaches and Special-Purpose & Off-Road Vehicles), Fleet Size, Propulsion Type, Charging Infrastructure, Electrification Deployment, Battery Technology, Application, End User and By Geography
According to Stratistics MRC, the Global Automotive Fleet Electrification Market is accounted for $65.3 billion in 2026 and is expected to reach $266.2 billion by 2034 growing at a CAGR of 19.2% during the forecast period. The Automotive Fleet Electrification Market involves the deployment and management of electric vehicles within commercial, corporate, public, and organizational fleets. It includes electric passenger vehicles, light commercial vehicles, heavy trucks, buses, and other fleet applications, supported by charging networks, battery systems, telematics, and energy-management technologies. Fleet operators consider factors such as driving patterns, vehicle range, charging requirements, battery performance, operating costs, and fleet utilization when implementing electrification programs. Participants include vehicle manufacturers, fleet management companies, charging infrastructure providers, utilities, energy firms, and technology developers. The market also covers solutions that connect electric vehicles, charging systems, fleet software, and energy resources for coordinated fleet operations.
Market Dynamics:
Driver:
Corporate Sustainability and Decarbonization Initiatives
Sustainability objectives are influencing fleet procurement and transportation strategies across businesses and public organizations. Companies with environmental and decarbonization targets may consider electric vehicles as part of broader efforts involving renewable electricity, energy efficiency, and emissions management. Logistics operators, corporate fleets, government agencies, and transportation providers can incorporate environmental criteria into vehicle purchasing and fleet-management decisions. Electrification can consequently become one component of a wider strategy for managing transportation-related emissions and energy use. These objectives may affect vehicle replacement schedules, charging infrastructure investments, fleet policies, and energy-management practices, particularly for organizations operating substantial numbers of vehicles across multiple locations.
Restraint:
High Initial Cost of Electric Fleet Vehicles
The substantial upfront expenditure associated with electric fleet vehicles can limit electrification decisions. Fleet operators purchasing electric cars, vans, buses, trucks, or specialized vehicles may face significant vehicle costs alongside investments in charging infrastructure, electrical upgrades, software, installation, and facility improvements. These combined requirements can create financial pressure, especially for smaller businesses with constrained investment budgets. While organizations may consider operating and maintenance economics over the vehicle lifecycle, the initial capital commitment can still influence procurement strategies. Fleet owners may therefore phase their transition over time or postpone vehicle replacement decisions while evaluating financing availability, infrastructure expenses, and the overall financial requirements of fleet electrification.
Opportunity:
Integration of Telematics and Fleet Management Technologies
Connected fleet technologies offer significant opportunities as organizations introduce electric vehicles into their operations. Telematics platforms can track vehicle positions, battery levels, charging status, energy consumption, driver activity, maintenance requirements, and route information. Combining these functions with electric fleet-management software can help operators coordinate vehicles and charging resources through centralized platforms. Technology providers can also develop applications for route planning, charging optimization, predictive maintenance, vehicle utilization, and operational monitoring. Compatibility with established fleet-management systems can further support the integration of electric vehicles into existing operations. This creates opportunities for software and telematics companies to provide specialized digital infrastructure for electrified fleets.
Threat:
Battery Supply Chain and Raw Material Risks
Battery-related supply-chain dependencies can introduce uncertainty into electric fleet deployment. Electric vehicle batteries rely on several critical minerals and specialized manufacturing processes, making the supply chain sensitive to material availability, processing capacity, geopolitical conditions, logistics disruptions, and market fluctuations. Such factors can affect battery production and, in turn, vehicle availability and procurement planning. Fleet operators converting large numbers of vehicles may need to account for potential changes in vehicle pricing, delivery schedules, and battery supply. The complexity of global battery supply networks therefore represents an important consideration for organizations developing long-term electrification strategies and sourcing electric commercial vehicles.
Covid-19 Impact:
COVID-19 significantly affected automotive fleet electrification through disruptions in manufacturing, supply networks, transportation activity, and investment planning. Factory closures and mobility restrictions delayed electric vehicle production and charging infrastructure development. Lower fleet utilization caused some operators to defer vehicle purchases and replacement programs, while interruptions in global supply chains affected the availability of batteries, semiconductors, and other components. At the same time, the pandemic increased attention toward resilient and technology-enabled transportation operations. With economic activity gradually returning, fleet operators reassessed vehicle strategies and increasingly considered electric mobility together with connected fleet-management technologies, energy efficiency, and operational resilience as part of future fleet planning.
The Passenger Cars segment is expected to be the largest during the forecast period
The Passenger Cars segment is expected to account for the largest market share during the forecast period, supported by the growing use of electric passenger vehicles across corporate, rental, shared-mobility, and institutional fleets. These vehicles address diverse requirements such as employee mobility, business transportation, service activities, and urban fleet operations. Their broad availability, compatibility with established charging solutions, and suitability for predictable daily travel patterns support their integration into electrification strategies. Passenger electric vehicles can also be connected with telematics, fleet-management software, and charging platforms, allowing organizations to coordinate vehicle utilization, monitor energy consumption, and manage electrified transportation activities more effectively.
The Last-Mile Delivery segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Last-Mile Delivery segment is predicted to witness the highest growth rate, supported by the expanding deployment of electric vehicles for parcel delivery, online-commerce logistics, grocery distribution, and short-distance commercial operations. These fleets commonly follow defined routes and predictable operating schedules, creating suitable conditions for electric vehicle integration. Operators can utilize electric vans, three-wheelers, and compact commercial vehicles alongside dedicated charging infrastructure and connected fleet-management systems. Increasing urban delivery activity and the need for efficient transportation solutions further support electrification opportunities in this application. The segment is particularly relevant for fleet operators conducting frequent delivery operations within densely populated urban and suburban areas.
Region with largest share:
During the forecast period, the Europe region is expected to hold the largest market share, supported by established electric mobility policies, emissions regulations, and growing integration of electric vehicles into business and commercial fleets. Organizations across the region are adopting electric cars, vans, buses, and commercial vehicles as part of regulatory compliance and environmental strategies. The availability of charging infrastructure and a developed electric vehicle industry also supports fleet deployment. Government support programs, low-emission urban policies, and corporate sustainability initiatives contribute to electrification activities. These conditions encourage the integration of electric vehicles across logistics, public transit, corporate transportation, and various other fleet-based mobility applications.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, driven by increasing electric vehicle production, supportive government policies, expanding charging networks, and greater adoption of electric vehicles by commercial fleet operators. Major markets including China, India, Japan, South Korea, and Southeast Asia are contributing to this expansion through investments in electric mobility and related infrastructure. Growing e-commerce activity and urban delivery requirements are supporting the deployment of electric fleet vehicles, while transit operators are adopting electric buses. Strong automotive manufacturing ecosystems, battery supply chains, and expanding electric commercial vehicle availability are also supporting electrification across regional fleet operations.
Key players in the market
Some of the key players in Automotive Fleet Electrification Market include BYD Company Limited, Ford Motor Company, Volvo Group, Daimler Truck Holding AG, PACCAR Inc., Tata Motors Limited, Ashok Leyland Limited, Iveco Group N.V., Hyundai Motor Company, Toyota Motor Corporation, Tesla, Inc., General Motors Company, ChargePoint Holdings, Inc., ABB Ltd., Siemens AG, Schneider Electric SE, Geotab Inc. and The Mobility House GmbH.
Key Developments:
In April 2026, Tata Motors entered into a strategic partnership with BillionE Mobility for systematic large-scale deployment of electric heavy-duty trucks. In April 2026, Tata Motors began deliveries of Prima E.55S electric prime movers, alongside an order for 250 additional vehicles.
In February 2026, BYD entered a strategic agreement with Localiza&Co covering the purchase of 10,000 hybrid and electric vehicles over two years. The vehicles are intended for rental, subscription, corporate fleet-management, and other mobility applications in Brazil.
In January 2026, Volvo Group advanced its collaboration with City Harvest and MN8 Energy under the Bronx is Breathing initiative. Volvo VNR Electric trucks for City Harvest will use charging infrastructure at the Fulton Fish Market and subsequently the planned freight-focused public charging hub.
Vehicle Type Covered:
• Passenger Cars
• Two-Wheelers
• Three-Wheelers
• Light Commercial Vehicles
• Medium Commercial Vehicles
• Heavy Commercial Vehicles
• Buses & Coaches
• Special-Purpose & Off-Road Vehicles
Fleet Sizes Covered:
• Small Fleets
• Medium Fleets
• Large Fleets
Propulsion Types Covered:
• Battery Electric Vehicles
• Plug-in Hybrid Electric Vehicles
• Fuel Cell Electric Vehicles
Charging Infrastructures Covered:
• AC Charging
• DC Fast Charging
• Ultra-Fast Charging
• Opportunity Charging
• Wireless Charging
• Battery Swapping
• Fleet Depot Charging
• Public Charging
• Workplace Charging
• Highway Charging
Electrification Deployments Covered:
• New Fleet Electrification
• Existing Fleet Replacement
• ICE-to-EV Fleet Conversion
• Mixed-Fleet Electrification
Battery Technologies Covered:
• Lithium Iron Phosphate
• Nickel Manganese Cobalt
• Nickel Cobalt Aluminum
• Solid-State Batteries
• Other Advanced Battery Technologies
Applications Covered:
• Last-Mile Delivery
• Long-Haul Transportation
• Urban Mobility
• Public Transportation
• Corporate Transportation
• Ride-Hailing & Shared Mobility
• Rental & Leasing
• Municipal Services
• Utility & Field Services
• Airport & Port Operations
• Construction & Industrial Operations
End Users Covered:
• Logistics & Delivery Companies
• Public Transit Operators
• Corporate Fleets
• Rental & Leasing Companies
• Ride-Hailing & Mobility Providers
• Government & Municipal Fleets
• Utility Companies
• Airport & Port Operators
• Construction & Industrial Companies
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Fleet Electrification Market, By Vehicle Type
5.1 Passenger Cars
5.2 Two-Wheelers
5.3 Three-Wheelers
5.4 Light Commercial Vehicles
5.5 Medium Commercial Vehicles
5.6 Heavy Commercial Vehicles
5.7 Buses & Coaches
5.8 Special-Purpose & Off-Road Vehicles
6 Global Automotive Fleet Electrification Market, By Fleet Size
6.1 Small Fleets
6.2 Medium Fleets
6.3 Large Fleets
7 Global Automotive Fleet Electrification Market, By Propulsion Type
7.1 Battery Electric Vehicles
7.2 Plug-in Hybrid Electric Vehicles
7.3 Fuel Cell Electric Vehicles
8 Global Automotive Fleet Electrification Market, By Charging Infrastructure
8.1 AC Charging
8.2 DC Fast Charging
8.3 Ultra-Fast Charging
8.4 Opportunity Charging
8.5 Wireless Charging
8.6 Battery Swapping
8.7 Fleet Depot Charging
8.8 Public Charging
8.9 Workplace Charging
8.10 Highway Charging
9 Global Automotive Fleet Electrification Market, By Electrification Deployment
9.1 New Fleet Electrification
9.2 Existing Fleet Replacement
9.3 ICE-to-EV Fleet Conversion
9.4 Mixed-Fleet Electrification
10 Global Automotive Fleet Electrification Market, By Battery Technology
10.1 Lithium Iron Phosphate
10.2 Nickel Manganese Cobalt
10.3 Nickel Cobalt Aluminum
10.4 Solid-State Batteries
10.5 Other Advanced Battery Technologies
11 Global Automotive Fleet Electrification Market, By Application
11.1 Last-Mile Delivery
11.2 Long-Haul Transportation
11.3 Urban Mobility
11.4 Public Transportation
11.5 Corporate Transportation
11.6 Ride-Hailing & Shared Mobility
11.7 Rental & Leasing
11.8 Municipal Services
11.9 Utility & Field Services
11.10 Airport & Port Operations
11.11 Construction & Industrial Operations
12 Global Automotive Fleet Electrification Market, By End User
12.1 Logistics & Delivery Companies
12.2 Public Transit Operators
12.3 Corporate Fleets
12.4 Rental & Leasing Companies
12.5 Ride-Hailing & Mobility Providers
12.6 Government & Municipal Fleets
12.7 Utility Companies
12.8 Airport & Port Operators
12.9 Construction & Industrial Companies
13 Global Automotive Fleet Electrification Market, By Geography
13.1 North America
13.1.1 United States
13.1.2 Canada
13.1.3 Mexico
13.2 Europe
13.2.1 United Kingdom
13.2.2 Germany
13.2.3 France
13.2.4 Italy
13.2.5 Spain
13.2.6 Netherlands
13.2.7 Belgium
13.2.8 Sweden
13.2.9 Switzerland
13.2.10 Poland
13.2.11 Rest of Europe
13.3 Asia Pacific
13.3.1 China
13.3.2 Japan
13.3.3 India
13.3.4 South Korea
13.3.5 Australia
13.3.6 Indonesia
13.3.7 Thailand
13.3.8 Malaysia
13.3.9 Singapore
13.3.10 Vietnam
13.3.11 Rest of Asia Pacific
13.4 South America
13.4.1 Brazil
13.4.2 Argentina
13.4.3 Colombia
13.4.4 Chile
13.4.5 Peru
13.4.6 Rest of South America
13.5 Rest of the World (RoW)
13.5.1 Middle East
13.5.1.1 Saudi Arabia
13.5.1.2 United Arab Emirates
13.5.1.3 Qatar
13.5.1.4 Israel
13.5.1.5 Rest of Middle East
13.5.2 Africa
13.5.2.1 South Africa
13.5.2.2 Egypt
13.5.2.3 Morocco
13.5.2.4 Rest of Africa
14 Strategic Market Intelligence
14.1 Industry Value Network and Supply Chain Assessment
14.2 White-Space and Opportunity Mapping
14.3 Product Evolution and Market Life Cycle Analysis
14.4 Channel, Distributor, and Go-to-Market Assessment
15 Industry Developments and Strategic Initiatives
15.1 Mergers and Acquisitions
15.2 Partnerships, Alliances, and Joint Ventures
15.3 New Product Launches and Certifications
15.4 Capacity Expansion and Investments
15.5 Other Strategic Initiatives
16 Company Profiles
16.1 BYD Company Limited
16.2 Ford Motor Company
16.3 Volvo Group
16.4 Daimler Truck Holding AG
16.5 PACCAR Inc.
16.6 Tata Motors Limited
16.7 Ashok Leyland Limited
16.8 Iveco Group N.V.
16.9 Hyundai Motor Company
16.10 Toyota Motor Corporation
16.11 Tesla, Inc.
16.12 General Motors Company
16.13 ChargePoint Holdings, Inc.
16.14 ABB Ltd.
16.15 Siemens AG
16.16 Schneider Electric SE
16.17 Geotab Inc.
16.18 The Mobility House GmbH
List of Tables
1 Global Automotive Fleet Electrification Market Outlook, By Region (2023-2034) ($MN)
2 Global Automotive Fleet Electrification Market Outlook, By Vehicle Type (2023-2034) ($MN)
3 Global Automotive Fleet Electrification Market Outlook, By Passenger Cars (2023-2034) ($MN)
4 Global Automotive Fleet Electrification Market Outlook, By Two-Wheelers (2023-2034) ($MN)
5 Global Automotive Fleet Electrification Market Outlook, By Three-Wheelers (2023-2034) ($MN)
6 Global Automotive Fleet Electrification Market Outlook, By Light Commercial Vehicles (2023-2034) ($MN)
7 Global Automotive Fleet Electrification Market Outlook, By Medium Commercial Vehicles (2023-2034) ($MN)
8 Global Automotive Fleet Electrification Market Outlook, By Heavy Commercial Vehicles (2023-2034) ($MN)
9 Global Automotive Fleet Electrification Market Outlook, By Buses & Coaches (2023-2034) ($MN)
10 Global Automotive Fleet Electrification Market Outlook, By Special-Purpose & Off-Road Vehicles (2023-2034) ($MN)
11 Global Automotive Fleet Electrification Market Outlook, By Fleet Size (2023-2034) ($MN)
12 Global Automotive Fleet Electrification Market Outlook, By Small Fleets (2023-2034) ($MN)
13 Global Automotive Fleet Electrification Market Outlook, By Medium Fleets (2023-2034) ($MN)
14 Global Automotive Fleet Electrification Market Outlook, By Large Fleets (2023-2034) ($MN)
15 Global Automotive Fleet Electrification Market Outlook, By Propulsion Type (2023-2034) ($MN)
16 Global Automotive Fleet Electrification Market Outlook, By Battery Electric Vehicles (2023-2034) ($MN)
17 Global Automotive Fleet Electrification Market Outlook, By Plug-in Hybrid Electric Vehicles (2023-2034) ($MN)
18 Global Automotive Fleet Electrification Market Outlook, By Fuel Cell Electric Vehicles (2023-2034) ($MN)
19 Global Automotive Fleet Electrification Market Outlook, By Charging Infrastructure (2023-2034) ($MN)
20 Global Automotive Fleet Electrification Market Outlook, By AC Charging (2023-2034) ($MN)
21 Global Automotive Fleet Electrification Market Outlook, By DC Fast Charging (2023-2034) ($MN)
22 Global Automotive Fleet Electrification Market Outlook, By Ultra-Fast Charging (2023-2034) ($MN)
23 Global Automotive Fleet Electrification Market Outlook, By Opportunity Charging (2023-2034) ($MN)
24 Global Automotive Fleet Electrification Market Outlook, By Wireless Charging (2023-2034) ($MN)
25 Global Automotive Fleet Electrification Market Outlook, By Battery Swapping (2023-2034) ($MN)
26 Global Automotive Fleet Electrification Market Outlook, By Fleet Depot Charging (2023-2034) ($MN)
27 Global Automotive Fleet Electrification Market Outlook, By Public Charging (2023-2034) ($MN)
28 Global Automotive Fleet Electrification Market Outlook, By Workplace Charging (2023-2034) ($MN)
29 Global Automotive Fleet Electrification Market Outlook, By Highway Charging (2023-2034) ($MN)
30 Global Automotive Fleet Electrification Market Outlook, By Electrification Deployment (2023-2034) ($MN)
31 Global Automotive Fleet Electrification Market Outlook, By New Fleet Electrification (2023-2034) ($MN)
32 Global Automotive Fleet Electrification Market Outlook, By Existing Fleet Replacement (2023-2034) ($MN)
33 Global Automotive Fleet Electrification Market Outlook, By ICE-to-EV Fleet Conversion (2023-2034) ($MN)
34 Global Automotive Fleet Electrification Market Outlook, By Mixed-Fleet Electrification (2023-2034) ($MN)
35 Global Automotive Fleet Electrification Market Outlook, By Battery Technology (2023-2034) ($MN)
36 Global Automotive Fleet Electrification Market Outlook, By Lithium Iron Phosphate (2023-2034) ($MN)
37 Global Automotive Fleet Electrification Market Outlook, By Nickel Manganese Cobalt (2023-2034) ($MN)
38 Global Automotive Fleet Electrification Market Outlook, By Nickel Cobalt Aluminum (2023-2034) ($MN)
39 Global Automotive Fleet Electrification Market Outlook, By Solid-State Batteries (2023-2034) ($MN)
40 Global Automotive Fleet Electrification Market Outlook, By Other Advanced Battery Technologies (2023-2034) ($MN)
41 Global Automotive Fleet Electrification Market Outlook, By Application (2023-2034) ($MN)
42 Global Automotive Fleet Electrification Market Outlook, By Last-Mile Delivery (2023-2034) ($MN)
43 Global Automotive Fleet Electrification Market Outlook, By Long-Haul Transportation (2023-2034) ($MN)
44 Global Automotive Fleet Electrification Market Outlook, By Urban Mobility (2023-2034) ($MN)
45 Global Automotive Fleet Electrification Market Outlook, By Public Transportation (2023-2034) ($MN)
46 Global Automotive Fleet Electrification Market Outlook, By Corporate Transportation (2023-2034) ($MN)
47 Global Automotive Fleet Electrification Market Outlook, By Ride-Hailing & Shared Mobility (2023-2034) ($MN)
48 Global Automotive Fleet Electrification Market Outlook, By Rental & Leasing (2023-2034) ($MN)
49 Global Automotive Fleet Electrification Market Outlook, By Municipal Services (2023-2034) ($MN)
50 Global Automotive Fleet Electrification Market Outlook, By Utility & Field Services (2023-2034) ($MN)
51 Global Automotive Fleet Electrification Market Outlook, By Airport & Port Operations (2023-2034) ($MN)
52 Global Automotive Fleet Electrification Market Outlook, By Construction & Industrial Operations (2023-2034) ($MN)
53 Global Automotive Fleet Electrification Market Outlook, By End User (2023-2034) ($MN)
54 Global Automotive Fleet Electrification Market Outlook, By Logistics & Delivery Companies (2023-2034) ($MN)
55 Global Automotive Fleet Electrification Market Outlook, By Public Transit Operators (2023-2034) ($MN)
56 Global Automotive Fleet Electrification Market Outlook, By Corporate Fleets (2023-2034) ($MN)
57 Global Automotive Fleet Electrification Market Outlook, By Rental & Leasing Companies (2023-2034) ($MN)
58 Global Automotive Fleet Electrification Market Outlook, By Ride-Hailing & Mobility Providers (2023-2034) ($MN)
59 Global Automotive Fleet Electrification Market Outlook, By Government & Municipal Fleets (2023-2034) ($MN)
60 Global Automotive Fleet Electrification Market Outlook, By Utility Companies (2023-2034) ($MN)
61 Global Automotive Fleet Electrification Market Outlook, By Airport & Port Operators (2023-2034) ($MN)
62 Global Automotive Fleet Electrification Market Outlook, By Construction & Industrial Companies (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
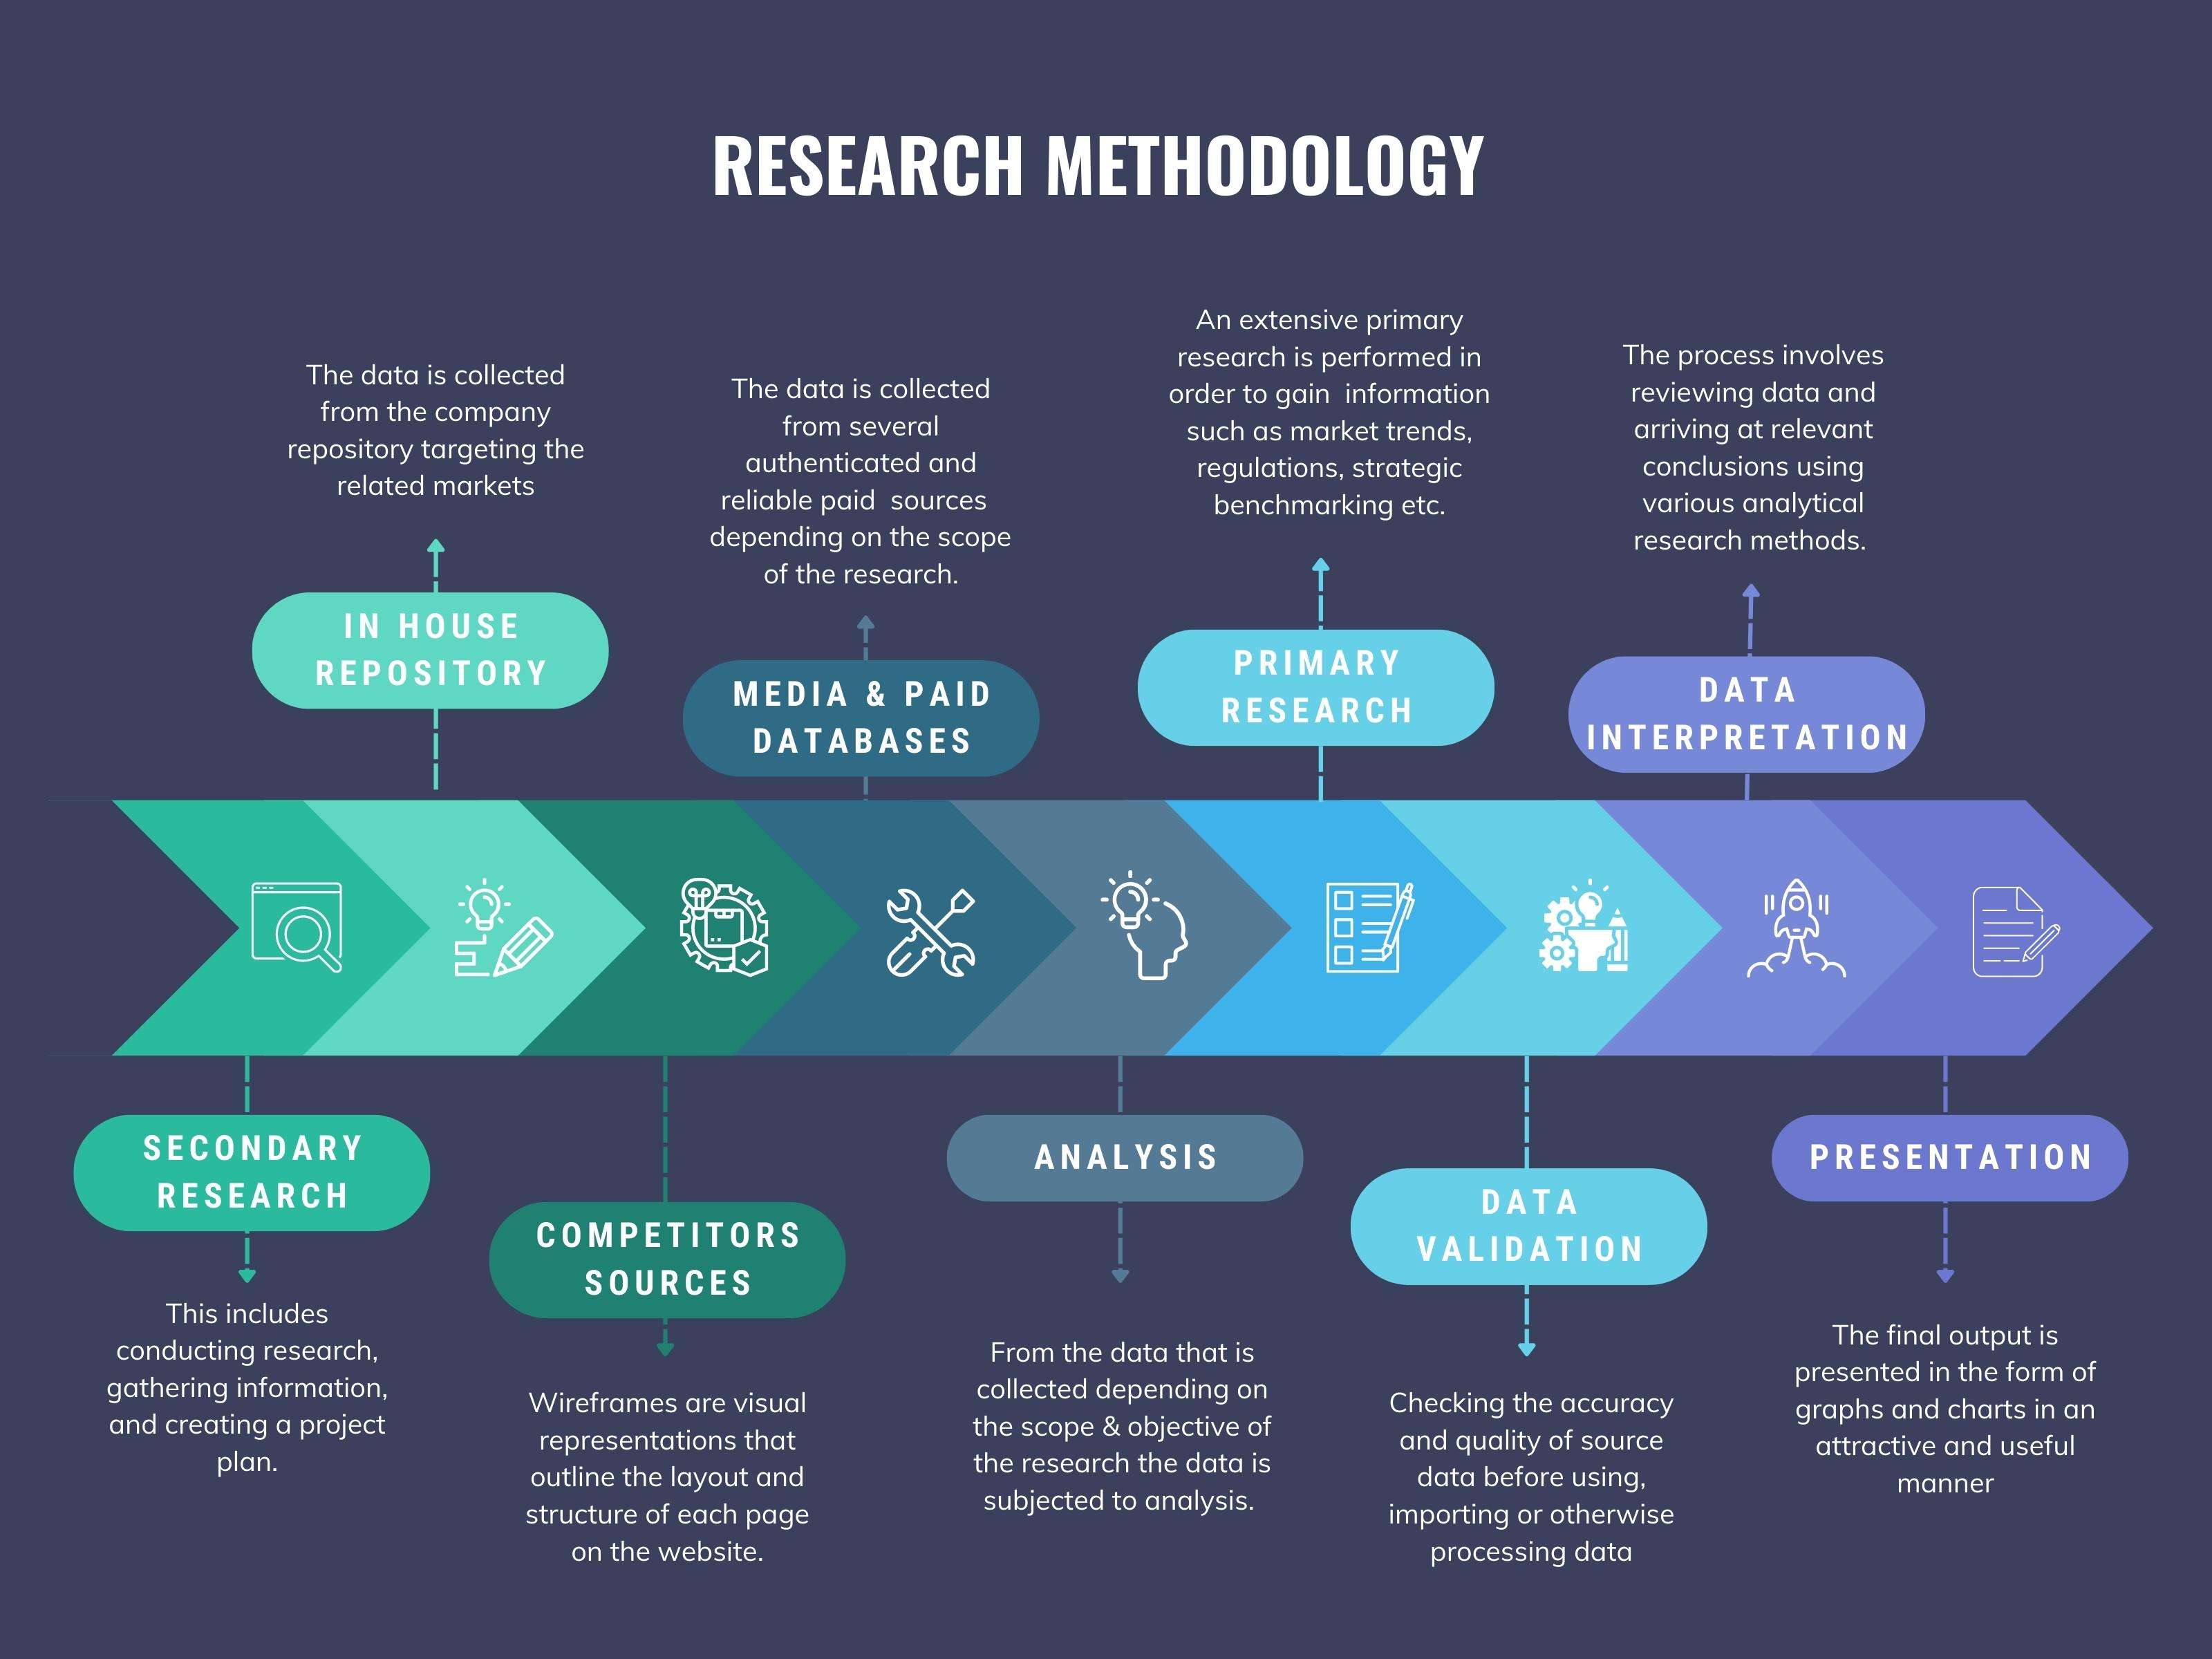
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.