Automotive Machine Learning Market
Automotive Machine Learning Market Forecasts To 2034 – Global Analysis By Component (Hardware, Software and Services), Machine Learning Type, Automotive System, Vehicle Type, Propulsion, Deployment, Technology, Application, End User and By Geography
According to Stratistics MRC, the Global Automotive Machine Learning Market is accounted for $5.4 billion in 2026 and is expected to reach $21.5 billion by 2034 growing at a CAGR of 19.0% during the forecast period. The Automotive Machine Learning Market encompasses the use of machine learning technologies across automotive applications to enhance vehicle intelligence, operational efficiency, safety, and user experiences. These technologies process extensive data collected from cameras, radar, lidar, sensors, connected platforms, and vehicle control systems. Key applications include autonomous driving, advanced driver assistance, predictive vehicle maintenance, intelligent routing, driver personalization, cybersecurity, traffic analysis, and smart manufacturing. Automotive manufacturers and technology companies are incorporating machine learning into increasingly software-driven and connected vehicles. Advances in artificial intelligence, onboard computing, vehicle connectivity, automated driving technologies, and data processing capabilities are contributing to the expanding adoption of machine learning throughout the automotive industry.
Market Dynamics:
Driver:
Increasing Vehicle Connectivity and Data Generation
The rapid growth of connected vehicles is increasing the availability of automotive data and supporting wider adoption of machine learning. Modern vehicles collect information from telematics, sensors, infotainment systems, navigation platforms, diagnostic equipment, and communication technologies. Machine learning can transform this extensive data into actionable information for predictive maintenance, traffic analysis, personalized services, vehicle optimization, and operational improvements. Increasing deployment of connected-car platforms and vehicle-to-everything communication is also expanding the volume and diversity of information generated by vehicles. With automobiles becoming increasingly software-driven and digitally connected, manufacturers and technology companies are using machine learning to interpret complex datasets and deliver smarter vehicle capabilities.
Restraint:
High Development and Implementation Costs
Significant expenses associated with developing and deploying machine learning technologies can limit market expansion. Automotive machine learning requires investment in data acquisition, algorithm design, model training, validation processes, computing systems, sensors, chips, and skilled technical personnel. Before implementation, systems must also undergo extensive testing across different road, weather, and operating conditions. These requirements can create financial challenges for smaller automotive companies and technology providers with constrained research and development resources. Additional costs may arise when new machine learning solutions need to be integrated into existing vehicle platforms. Consequently, high technology and implementation expenditures can delay adoption, particularly within cost-sensitive automotive segments.
Opportunity:
Expansion of Edge AI and In-Vehicle Machine Learning
Growing adoption of edge AI and onboard machine learning is opening new opportunities throughout the automotive technology ecosystem. Running machine learning models within vehicles can provide rapid processing, reduce reliance on cloud connectivity, and enable intelligent functions that require immediate responses. Potential applications include driver monitoring, object recognition, autonomous driving, predictive maintenance, cybersecurity, and personalized vehicle services. Advances in automotive semiconductors, neural processing units, system-on-chip platforms, and energy-efficient computing are supporting more sophisticated AI processing directly inside vehicles. As manufacturers pursue faster and more dependable intelligent capabilities, new opportunities are developing for semiconductor companies, software providers, AI developers, and automotive suppliers specializing in edge machine learning.
Threat:
Dependence on High-Quality Automotive Data
The reliance of machine learning systems on extensive and reliable automotive datasets can create a significant market challenge. Effective models require diverse and representative information covering different roads, climates, traffic conditions, geographic environments, vehicle configurations, and driving scenarios. Collecting, labeling, validating, and maintaining such datasets can require substantial time and resources. Incomplete, inaccurate, biased, or poorly representative data may reduce algorithm effectiveness and complicate system validation. Additional difficulties can arise from data ownership, privacy requirements, accessibility restrictions, and inconsistent data formats. These factors may hinder the training and improvement of machine learning models and create challenges for companies developing advanced automotive intelligence solutions.
Covid-19 Impact:
The COVID-19 outbreak produced both challenges and opportunities for the Automotive Machine Learning Market. Initial lockdowns disrupted manufacturing facilities, automotive supply chains, vehicle sales, technology development, and testing activities, causing some projects and investments to be postponed. At the same time, the pandemic encouraged automakers to accelerate digitalization, automation, remote operations, connected mobility, and intelligent manufacturing practices. Machine learning became increasingly relevant for applications such as predictive maintenance, manufacturing optimization, supply-chain analysis, autonomous driving, and contactless vehicle services. With automotive production gradually recovering, continued investment in artificial intelligence, connected vehicles, software-defined architectures, and automated driving technologies helped strengthen the market's recovery.
The Hardware segment is expected to be the largest during the forecast period
The Hardware segment is expected to account for the largest market share during the forecast period, driven by the expanding use of advanced processors, computing platforms, sensors, accelerators, and automotive semiconductor technologies needed to execute machine learning workloads. Intelligent vehicle functions require powerful processing capabilities for real-time data analysis, environmental perception, automated decision-making, driver assistance, and predictive applications. Rising integration of cameras, radar, lidar, GPUs, neural processing units, and system-on-chip solutions is creating stronger demand for specialized automotive computing hardware. Furthermore, increasing vehicle connectivity and the transition toward software-defined vehicle architectures are encouraging automakers to incorporate more sophisticated hardware platforms.
The Sensor Fusion segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Sensor Fusion segment is predicted to witness the highest growth rate, driven by increasing integration of multiple sensing technologies, including cameras, radar, lidar, and ultrasonic systems, within modern vehicles. Machine learning enables these diverse data sources to be combined and interpreted more effectively, supporting improved object recognition, localization, environmental awareness, and driving decisions. The expanding deployment of advanced driver assistance and automated driving functions is creating stronger requirements for dependable multi-sensor perception. In addition, connected and software-defined vehicle architectures are encouraging the development of advanced sensor fusion technologies capable of processing information in real time and enhancing overall vehicle intelligence and operational capabilities.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by its established automotive and technology ecosystem and strong concentration of companies involved in artificial intelligence, semiconductors, and vehicle technologies. Increasing development of autonomous driving, advanced driver assistance, connected mobility, and software-defined vehicles is creating significant demand for machine learning capabilities. The region's advanced computing infrastructure and high level of vehicle connectivity further support adoption across automotive applications. In addition, substantial research and development activity and collaboration between automotive manufacturers and technology providers are encouraging the development and deployment of machine learning solutions across passenger vehicles, commercial vehicles, and intelligent mobility platforms.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, supported by increasing vehicle production, electrification, connectivity, and deployment of advanced driver assistance technologies. Automotive companies and technology providers across the region are strengthening investments in artificial intelligence, autonomous mobility, semiconductor technologies, and connected vehicle platforms. The growing adoption of intelligent vehicles is creating opportunities for machine learning applications in automated driving, sensor processing, predictive maintenance, personalization, and vehicle optimization. Improvements in digital infrastructure, expanding technology investment, and stronger cooperation between automotive manufacturers and technology firms are also contributing to the rapid development and adoption of machine learning solutions throughout the region.
Key players in the market
Some of the key players in Automotive Machine Learning Market include NVIDIA Corporation, Qualcomm Technologies, Inc., Mobileye Global Inc., Robert Bosch GmbH, Continental AG, Aptiv PLC, DENSO Corporation, ZF Friedrichshafen AG, Valeo SE, Hyundai Mobis Co., Ltd., NXP Semiconductors N.V., Renesas Electronics Corporation, Texas Instruments Incorporated, Ambarella, Inc., Huawei Technologies Co., Ltd., Horizon Robotics, Inc., Magna International Inc., Tesla, Inc.
Key Developments:
In September 2026, Ambarella and ZEDEDA announced a strategic partnership to bring cloud-orchestrated AI to physical-edge devices, including vehicles. ZEDEDA’s platform can deploy, update, and manage AI models on Ambarella edge-AI SoCs, supporting automotive and mobility applications.
In January 2026, NVIDIA announced an expanded collaboration with Hyundai Motor Company and Kia to advance data-driven autonomous driving using NVIDIA accelerated computing, AI infrastructure, and autonomous-driving software together with Hyundai Motor Group's vehicle data and software-defined vehicle capabilities.
In February 2024, Texas Instruments announced a collaboration with Synopsys to provide a Virtualizer development kit for TI’s TDA5 automotive SoCs.
Components Covered:
• Hardware
• Software
• Services
Machine Learning Types Covered:
• Supervised Learning
• Unsupervised Learning
• Semi-Supervised Learning
• Reinforcement Learning
• Deep Learning
Automotive Systems Covered:
• Advanced Driver Assistance Systems (ADAS)
• Autonomous Driving Systems
• In-Vehicle Infotainment (IVI)
• Telematics and Connectivity Systems
• Powertrain Systems
• Battery Management Systems
• Vehicle Diagnostics Systems
• Vehicle Cybersecurity Systems
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles
• Heavy Commercial Vehicles
• Buses
• Two-Wheelers
Propulsions Covered:
• Internal Combustion Engine Vehicles
• Hybrid Electric Vehicles
• Plug-in Hybrid Electric Vehicles
• Battery Electric Vehicles
• Fuel Cell Electric Vehicles
Deployments Covered:
• On-Board
• Edge-Based
• Cloud-Based
• Hybrid
Technologies Covered:
• Computer Vision
• Natural Language Processing
• Speech Recognition
• Predictive Analytics
• Anomaly Detection
• Sensor Fusion
• Recommendation Systems
Applications Covered:
• Autonomous Driving
• Driver and Occupant Monitoring
• Object and Environment Recognition
• Path and Trajectory Planning
• Predictive Maintenance
• Vehicle Health Monitoring
• Vehicle Personalization
• Fleet Optimization
• Demand Forecasting
• Manufacturing and Quality Inspection
End Users Covered:
• Automotive OEMs
• Tier 1 Suppliers
• Tier 2 and Tier 3 Suppliers
• Mobility and Fleet Operators
• Automotive Technology Providers
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Machine Learning Market, By Component
5.1 Hardware
5.2 Software
5.3 Services
6 Global Automotive Machine Learning Market, By Machine Learning Type
6.1 Supervised Learning
6.2 Unsupervised Learning
6.3 Semi-Supervised Learning
6.4 Reinforcement Learning
6.5 Deep Learning
7 Global Automotive Machine Learning Market, By Automotive System
7.1 Advanced Driver Assistance Systems (ADAS)
7.2 Autonomous Driving Systems
7.3 In-Vehicle Infotainment (IVI)
7.4 Telematics and Connectivity Systems
7.5 Powertrain Systems
7.6 Battery Management Systems
7.7 Vehicle Diagnostics Systems
7.8 Vehicle Cybersecurity Systems
8 Global Automotive Machine Learning Market, By Vehicle Type
8.1 Passenger Cars
8.2 Light Commercial Vehicles
8.3 Heavy Commercial Vehicles
8.4 Buses
8.5 Two-Wheelers
9 Global Automotive Machine Learning Market, By Propulsion
9.1 Internal Combustion Engine Vehicles
9.2 Hybrid Electric Vehicles
9.3 Plug-in Hybrid Electric Vehicles
9.4 Battery Electric Vehicles
9.5 Fuel Cell Electric Vehicles
10 Global Automotive Machine Learning Market, By Deployment
10.1 On-Board
10.2 Edge-Based
10.3 Cloud-Based
10.4 Hybrid
11 Global Automotive Machine Learning Market, By Technology
11.1 Computer Vision
11.2 Natural Language Processing
11.3 Speech Recognition
11.4 Predictive Analytics
11.5 Anomaly Detection
11.6 Sensor Fusion
11.7 Recommendation Systems
12 Global Automotive Machine Learning Market, By Application
12.1 Autonomous Driving
12.2 Driver and Occupant Monitoring
12.3 Object and Environment Recognition
12.4 Path and Trajectory Planning
12.5 Predictive Maintenance
12.6 Vehicle Health Monitoring
12.7 Vehicle Personalization
12.8 Fleet Optimization
12.9 Demand Forecasting
12.1 Manufacturing and Quality Inspection
13 Global Automotive Machine Learning Market, By End User
13.1 Automotive OEMs
13.2 Tier 1 Suppliers
13.3 Tier 2 and Tier 3 Suppliers
13.4 Mobility and Fleet Operators
13.5 Automotive Technology Providers
14 Global Automotive Machine Learning Market, By Geography
14.1 North America
14.1.1 United States
14.1.2 Canada
14.1.3 Mexico
14.2 Europe
14.2.1 United Kingdom
14.2.2 Germany
14.2.3 France
14.2.4 Italy
14.2.5 Spain
14.2.6 Netherlands
14.2.7 Belgium
14.2.8 Sweden
14.2.9 Switzerland
14.2.10 Poland
14.2.11 Rest of Europe
14.3 Asia Pacific
14.3.1 China
14.3.2 Japan
14.3.3 India
14.3.4 South Korea
14.3.5 Australia
14.3.6 Indonesia
14.3.7 Thailand
14.3.8 Malaysia
14.3.9 Singapore
14.3.10 Vietnam
14.3.11 Rest of Asia Pacific
14.4 South America
14.4.1 Brazil
14.4.2 Argentina
14.4.3 Colombia
14.4.4 Chile
14.4.5 Peru
14.4.6 Rest of South America
14.5 Rest of the World (RoW)
14.5.1 Middle East
14.5.1.1 Saudi Arabia
14.5.1.2 United Arab Emirates
14.5.1.3 Qatar
14.5.1.4 Israel
14.5.1.5 Rest of Middle East
14.5.2 Africa
14.5.2.1 South Africa
14.5.2.2 Egypt
14.5.2.3 Morocco
14.5.2.4 Rest of Africa
15 Strategic Market Intelligence
15.1 Industry Value Network and Supply Chain Assessment
15.2 White-Space and Opportunity Mapping
15.3 Product Evolution and Market Life Cycle Analysis
15.4 Channel, Distributor, and Go-to-Market Assessment
16 Industry Developments and Strategic Initiatives
16.1 Mergers and Acquisitions
16.2 Partnerships, Alliances, and Joint Ventures
16.3 New Product Launches and Certifications
16.4 Capacity Expansion and Investments
16.5 Other Strategic Initiatives
17 Company Profiles
17.1 NVIDIA Corporation
17.2 Qualcomm Technologies, Inc.
17.3 Mobileye Global Inc.
17.4 Robert Bosch GmbH
17.5 Continental AG
17.6 Aptiv PLC
17.7 DENSO Corporation
17.8 ZF Friedrichshafen AG
17.9 Valeo SE
17.10 Hyundai Mobis Co., Ltd.
17.11 NXP Semiconductors N.V.
17.12 Renesas Electronics Corporation
17.13 Texas Instruments Incorporated
17.14 Ambarella, Inc.
17.15 Huawei Technologies Co., Ltd.
17.16 Horizon Robotics, Inc.
17.17 Magna International Inc.
17.18 Tesla, Inc.
List of Tables
1 Global Automotive Machine Learning Market Outlook, By Region (2023-2034) ($MN)
2 Global Automotive Machine Learning Market Outlook, By Component (2023-2034) ($MN)
3 Global Automotive Machine Learning Market Outlook, By Hardware (2023-2034) ($MN)
4 Global Automotive Machine Learning Market Outlook, By Software (2023-2034) ($MN)
5 Global Automotive Machine Learning Market Outlook, By Services (2023-2034) ($MN)
6 Global Automotive Machine Learning Market Outlook, By Machine Learning Type (2023-2034) ($MN)
7 Global Automotive Machine Learning Market Outlook, By Supervised Learning (2023-2034) ($MN)
8 Global Automotive Machine Learning Market Outlook, By Unsupervised Learning (2023-2034) ($MN)
9 Global Automotive Machine Learning Market Outlook, By Semi-Supervised Learning (2023-2034) ($MN)
10 Global Automotive Machine Learning Market Outlook, By Reinforcement Learning (2023-2034) ($MN)
11 Global Automotive Machine Learning Market Outlook, By Deep Learning (2023-2034) ($MN)
12 Global Automotive Machine Learning Market Outlook, By Automotive System (2023-2034) ($MN)
13 Global Automotive Machine Learning Market Outlook, By Advanced Driver Assistance Systems (ADAS) (2023-2034) ($MN)
14 Global Automotive Machine Learning Market Outlook, By Autonomous Driving Systems (2023-2034) ($MN)
15 Global Automotive Machine Learning Market Outlook, By In-Vehicle Infotainment (IVI) (2023-2034) ($MN)
16 Global Automotive Machine Learning Market Outlook, By Telematics and Connectivity Systems (2023-2034) ($MN)
17 Global Automotive Machine Learning Market Outlook, By Powertrain Systems (2023-2034) ($MN)
18 Global Automotive Machine Learning Market Outlook, By Battery Management Systems (2023-2034) ($MN)
19 Global Automotive Machine Learning Market Outlook, By Vehicle Diagnostics Systems (2023-2034) ($MN)
20 Global Automotive Machine Learning Market Outlook, By Vehicle Cybersecurity Systems (2023-2034) ($MN)
21 Global Automotive Machine Learning Market Outlook, By Vehicle Type (2023-2034) ($MN)
22 Global Automotive Machine Learning Market Outlook, By Passenger Cars (2023-2034) ($MN)
23 Global Automotive Machine Learning Market Outlook, By Light Commercial Vehicles (2023-2034) ($MN)
24 Global Automotive Machine Learning Market Outlook, By Heavy Commercial Vehicles (2023-2034) ($MN)
25 Global Automotive Machine Learning Market Outlook, By Buses (2023-2034) ($MN)
26 Global Automotive Machine Learning Market Outlook, By Two-Wheelers (2023-2034) ($MN)
27 Global Automotive Machine Learning Market Outlook, By Propulsion (2023-2034) ($MN)
28 Global Automotive Machine Learning Market Outlook, By Internal Combustion Engine Vehicles (2023-2034) ($MN)
29 Global Automotive Machine Learning Market Outlook, By Hybrid Electric Vehicles (2023-2034) ($MN)
30 Global Automotive Machine Learning Market Outlook, By Plug-in Hybrid Electric Vehicles (2023-2034) ($MN)
31 Global Automotive Machine Learning Market Outlook, By Battery Electric Vehicles (2023-2034) ($MN)
32 Global Automotive Machine Learning Market Outlook, By Fuel Cell Electric Vehicles (2023-2034) ($MN)
33 Global Automotive Machine Learning Market Outlook, By Deployment (2023-2034) ($MN)
34 Global Automotive Machine Learning Market Outlook, By On-Board (2023-2034) ($MN)
35 Global Automotive Machine Learning Market Outlook, By Edge-Based (2023-2034) ($MN)
36 Global Automotive Machine Learning Market Outlook, By Cloud-Based (2023-2034) ($MN)
37 Global Automotive Machine Learning Market Outlook, By Hybrid (2023-2034) ($MN)
38 Global Automotive Machine Learning Market Outlook, By Technology (2023-2034) ($MN)
39 Global Automotive Machine Learning Market Outlook, By Computer Vision (2023-2034) ($MN)
40 Global Automotive Machine Learning Market Outlook, By Natural Language Processing (2023-2034) ($MN)
41 Global Automotive Machine Learning Market Outlook, By Speech Recognition (2023-2034) ($MN)
42 Global Automotive Machine Learning Market Outlook, By Predictive Analytics (2023-2034) ($MN)
43 Global Automotive Machine Learning Market Outlook, By Anomaly Detection (2023-2034) ($MN)
44 Global Automotive Machine Learning Market Outlook, By Sensor Fusion (2023-2034) ($MN)
45 Global Automotive Machine Learning Market Outlook, By Recommendation Systems (2023-2034) ($MN)
46 Global Automotive Machine Learning Market Outlook, By Application (2023-2034) ($MN)
47 Global Automotive Machine Learning Market Outlook, By Autonomous Driving (2023-2034) ($MN)
48 Global Automotive Machine Learning Market Outlook, By Driver and Occupant Monitoring (2023-2034) ($MN)
49 Global Automotive Machine Learning Market Outlook, By Object and Environment Recognition (2023-2034) ($MN)
50 Global Automotive Machine Learning Market Outlook, By Path and Trajectory Planning (2023-2034) ($MN)
51 Global Automotive Machine Learning Market Outlook, By Predictive Maintenance (2023-2034) ($MN)
52 Global Automotive Machine Learning Market Outlook, By Vehicle Health Monitoring (2023-2034) ($MN)
53 Global Automotive Machine Learning Market Outlook, By Vehicle Personalization (2023-2034) ($MN)
54 Global Automotive Machine Learning Market Outlook, By Fleet Optimization (2023-2034) ($MN)
55 Global Automotive Machine Learning Market Outlook, By Demand Forecasting (2023-2034) ($MN)
56 Global Automotive Machine Learning Market Outlook, By Manufacturing and Quality Inspection (2023-2034) ($MN)
57 Global Automotive Machine Learning Market Outlook, By End User (2023-2034) ($MN)
58 Global Automotive Machine Learning Market Outlook, By Automotive OEMs (2023-2034) ($MN)
59 Global Automotive Machine Learning Market Outlook, By Tier 1 Suppliers (2023-2034) ($MN)
60 Global Automotive Machine Learning Market Outlook, By Tier 2 and Tier 3 Suppliers (2023-2034) ($MN)
61 Global Automotive Machine Learning Market Outlook, By Mobility and Fleet Operators (2023-2034) ($MN)
62 Global Automotive Machine Learning Market Outlook, By Automotive Technology Providers (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
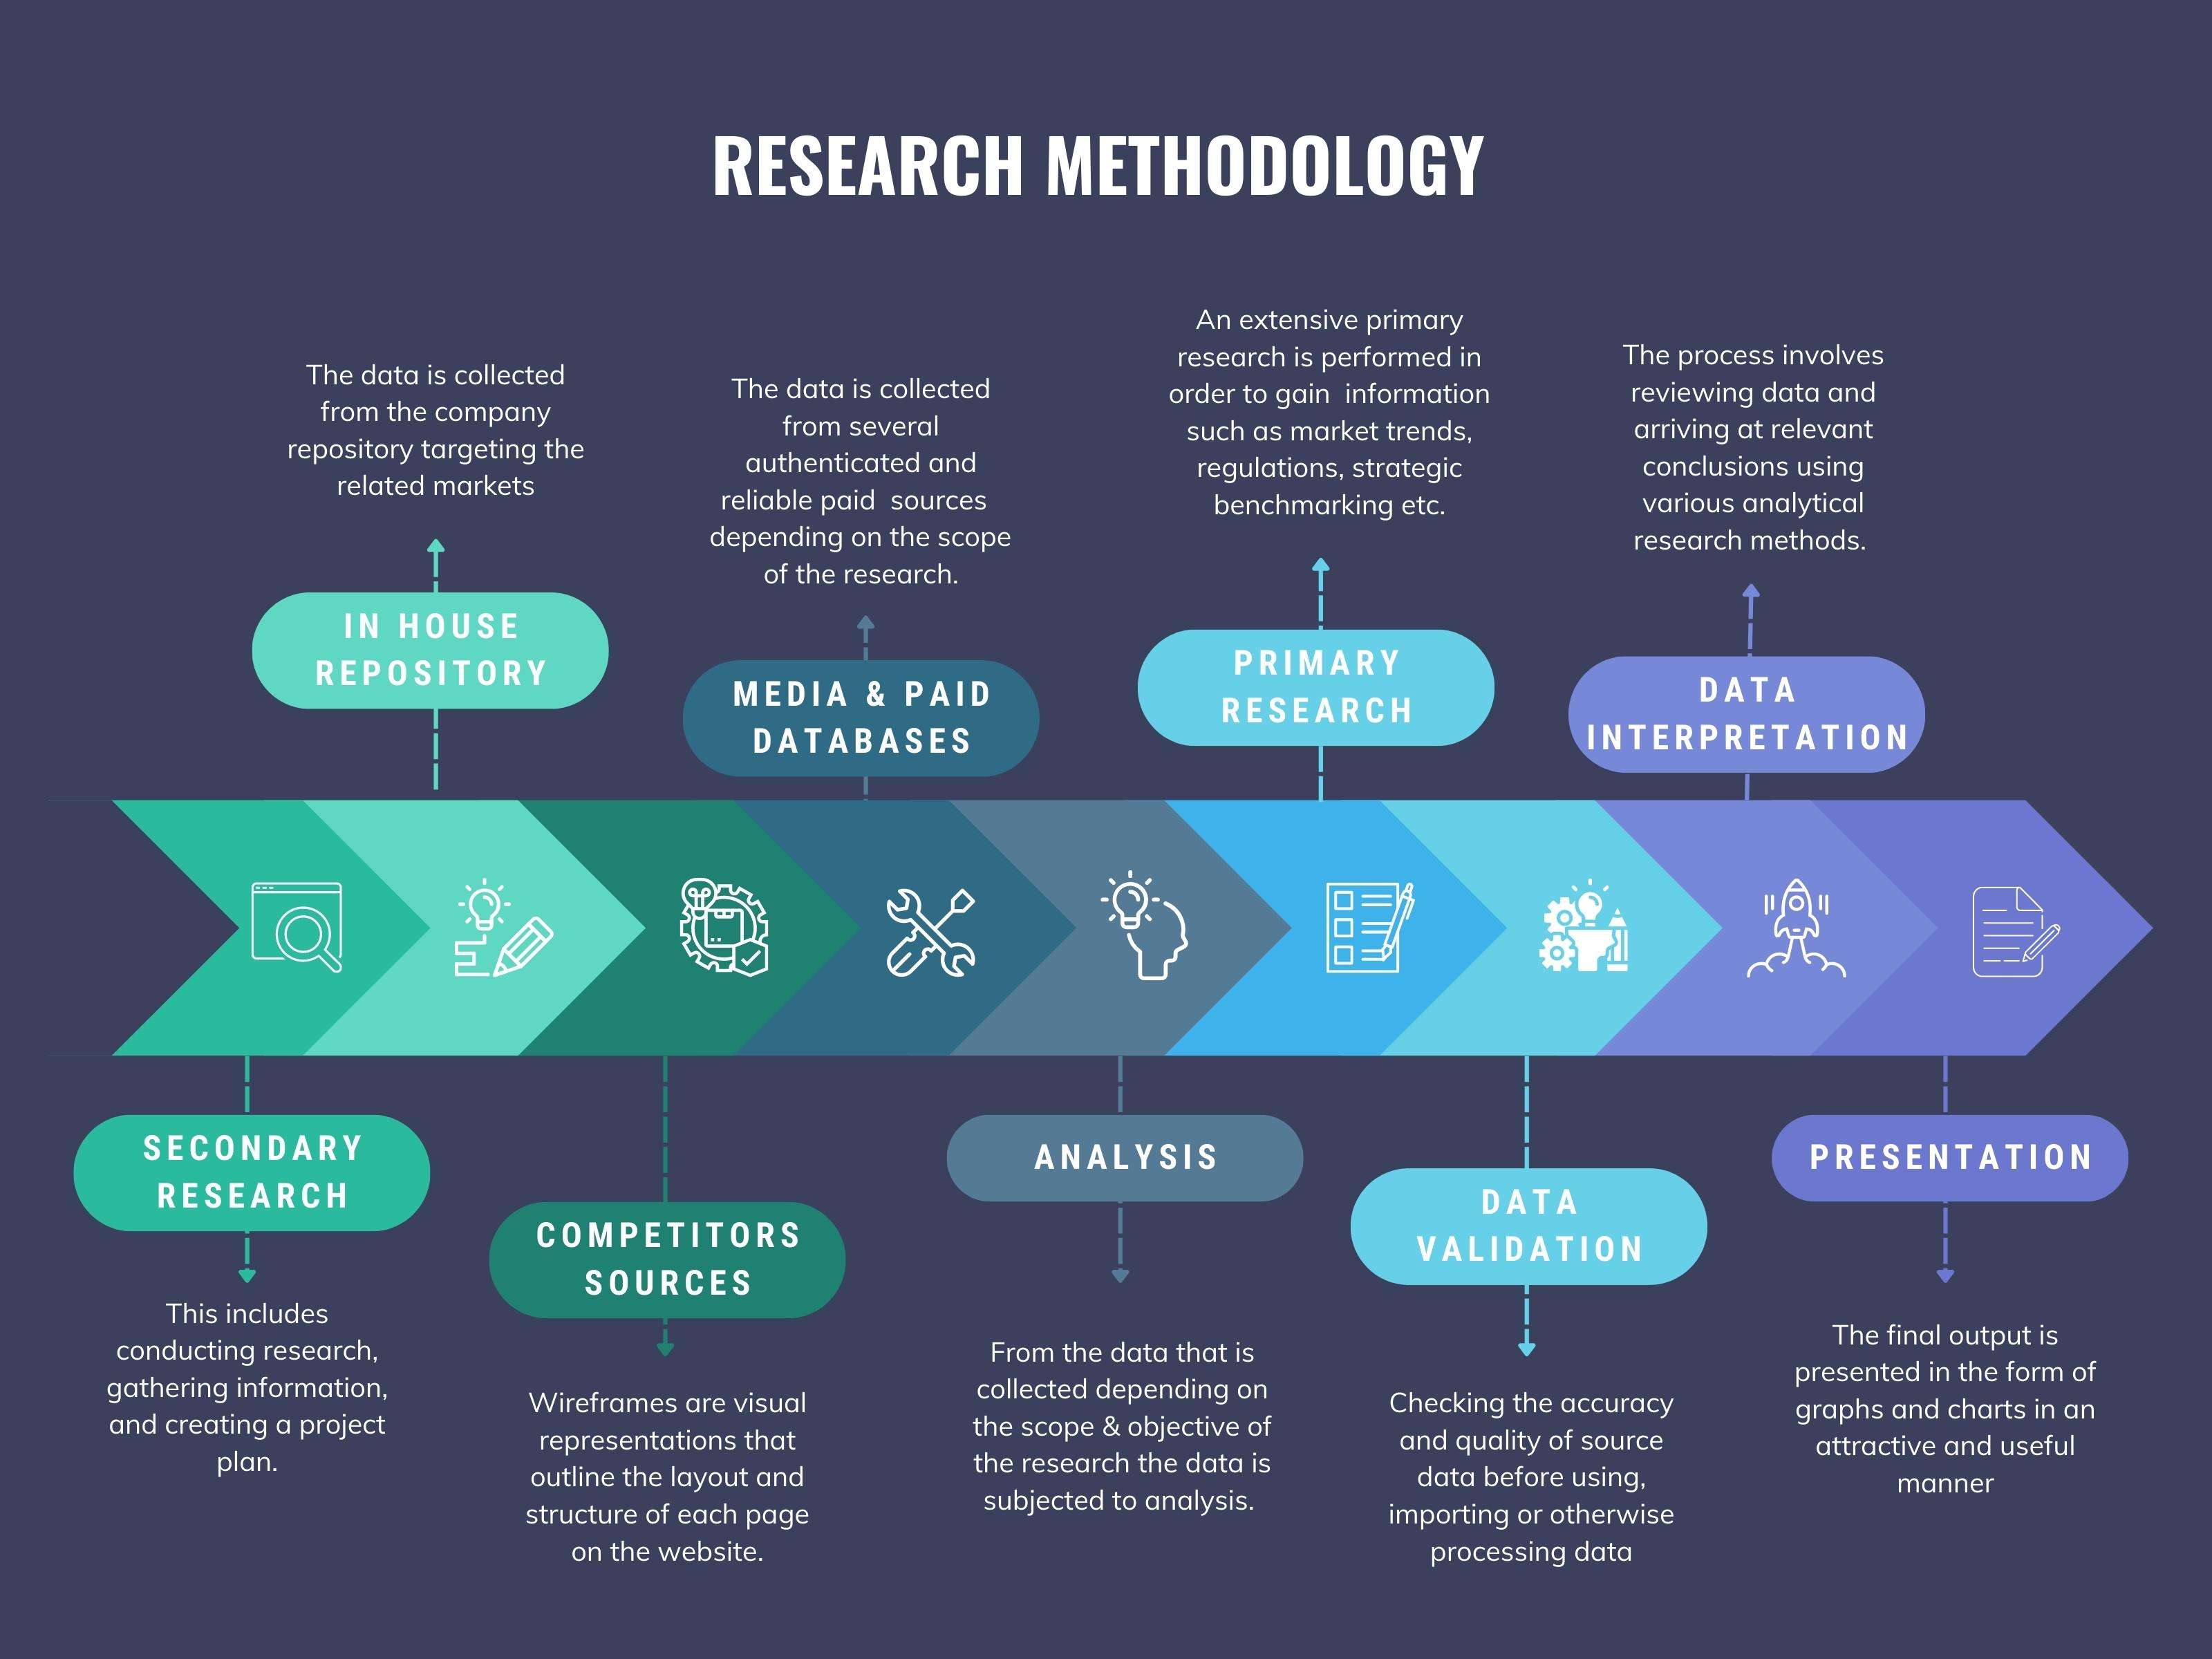
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.