Automotive Suspension Market
Automotive Suspension Market Forecasts to 2034 – Global Analysis By Component (Coil Springs, Leaf Springs, Air Springs, Shock Absorbers & Dampers, Struts, Control Arms, Ball Joints, Stabilizer Bars & Links, Bushings, and Other Components), Suspension Configuration, System Type, Vehicle Type, Propulsion, and By Geography
According to Stratistics MRC, the Global Automotive Suspension Market is accounted for $54.3 billion in 2026 and is expected to reach $82.1 billion by 2034 growing at a CAGR of 5.3% during the forecast period. Automotive suspension systems are critical vehicle components that connect the vehicle body to its wheels, providing ride comfort, vehicle stability, and handling performance while absorbing road shocks and maintaining tire contact with the road surface. The market encompasses various suspension types across passenger cars, light commercial vehicles, heavy commercial vehicles, off-highway vehicles, and two-wheelers, serving internal combustion engine vehicles, hybrid electric vehicles, plug-in hybrid electric vehicles, battery electric vehicles, and fuel cell electric vehicles.
Market Dynamics:
Driver:
Growing vehicle production and increasing demand for ride comfort
The continuous growth in global vehicle production and rising consumer expectations for ride comfort and vehicle dynamics are primary drivers for the automotive suspension market. Consumers increasingly prioritize ride quality, handling, and comfort in vehicle purchasing decisions. Automotive manufacturers are investing in advanced suspension technologies including adaptive dampers, air suspension, and active suspension systems to differentiate their vehicles. The growing premiumization trend across vehicle segments is expanding adoption of advanced suspension technologies. As vehicle production grows and consumer expectations rise, suspension system demand increases across all vehicle types and segments, supporting sustained market expansion.
Restraint:
High cost of advanced suspension technologies
The significant costs associated with advanced suspension technologies and the needs for specialized manufacturing capabilities represent a major restraint for the market. Advanced systems including adaptive dampers, air suspension, and active suspension require substantial investment in development and manufacturing. OEMs may limit advanced suspension availability to premium vehicle segments to manage costs. Replacement and maintenance costs for advanced systems are higher than conventional suspension. Price sensitivity in entry-level and mid-range vehicle segments may limit adoption. These cost barriers may constrain market growth, particularly in cost-sensitive vehicle segments and developing regions.
Opportunity:
Adoption of advanced suspension technologies in electric vehicles
The growing electric vehicle market presents significant opportunities for suspension system manufacturers, as EV-specific suspension requirements and the need to manage battery weight and vehicle dynamics create demand for specialized solutions. The additional weight of batteries increases demands on suspension components, requiring robust and durable systems. The absence of engine noise in EVs heightens the importance of suspension refinement for ride comfort. EV manufacturers are increasingly adopting advanced suspension technologies including air suspension and adaptive dampers. As EV production scales and technology becomes more accessible, suspension demand in the EV sector expands.
Threat:
Competition from alternative mobility solutions
Competition from alternative mobility solutions including ride-sharing, micro-mobility, and public transportation may affect long-term vehicle ownership trends and suspension market demand. Shared mobility reduces individual vehicle ownership, potentially affecting suspension demand. Compact mobility solutions including electric bikes and scooters require different suspension solutions. Urban planning policies promoting reduced vehicle usage may affect vehicle parc growth. This mobility transition may impact suspension demand patterns, particularly in regions with significant urban density and alternative transportation adoption.
Covid-19 Impact:
The COVID-19 pandemic had a significant impact on the automotive suspension market. Vehicle production shutdowns and supply chain disruptions temporarily affected suspension system production and installation. Semiconductor shortages affected vehicle production volumes. However, vehicle demand rebounded strongly post-pandemic, with consumers prioritizing personal mobility. The shift toward vehicle ownership in some markets increased demand. Recovery across all vehicle segments has supported suspension market growth, with continued investment in advanced suspension technologies.
The Passenger Cars segment is expected to be the largest during the forecast period
The Passenger Cars segment is expected to account for the largest market share during the forecast period, driven by the high global production volume of passenger vehicles, strong consumer demand for ride comfort, and continuous innovation in passenger car suspension systems. Passenger cars represent the largest vehicle category globally, with substantial production volumes and aftermarket demand. The segment benefits from consumer focus on ride quality and handling, driving adoption of advanced suspension technologies. Growing premiumization across vehicle segments is expanding advanced suspension penetration. As passenger car production continues growing and consumer expectations rise, passenger cars maintain the largest vehicle type segment share.
The Battery Electric Vehicles (BEV) segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Battery Electric Vehicles (BEV) segment is predicted to witness the highest growth rate, fueled by the rapid expansion of EV production, increasing EV adoption globally, and the specialized suspension requirements of electric vehicles. EV-specific suspension requirements include managing battery weight and optimizing ride dynamics. The absence of engine noise heightens suspension refinement importance. EV manufacturers are increasingly adopting advanced suspension technologies. The segment benefits from strong policy support for EV adoption and automaker electrification commitments. As EV production scales and technology adoption accelerates, BEVs deliver the fastest propulsion segment growth.
Region with largest share:
During the forecast period, the Asia-Pacific region is expected to hold the largest market share, supported by the world's largest vehicle production base, growing vehicle parc, and expanding automotive manufacturing capacity in China, India, Japan, and South Korea. The region accounts for a substantial share of global vehicle production and suspension consumption. Rising vehicle ownership and consumer expectations for ride comfort support suspension demand. Strong automotive manufacturing capabilities provide supply chain advantages. With the world's largest vehicle production and growing consumer expectations, Asia Pacific maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by continued vehicle production growth, rising consumer expectations, and increasing adoption of advanced suspension technologies across the region. The region's large and growing vehicle production creates substantial suspension demand. Rising disposable incomes and vehicle ownership are expanding the addressable market. Increasing premiumization and consumer focus on ride comfort support advanced suspension adoption. As vehicle production and technology adoption accelerate, Asia Pacific delivers the fastest automotive suspension market growth globally.
Key players in the market
Some of the key players in Automotive Suspension Market include ZF Friedrichshafen AG, Tenneco Inc., thyssenkrupp AG, KYB Corporation, Continental AG, HL Mando Corporation, Marelli Holdings Co., Ltd., Hitachi Astemo, Ltd., Schaeffler AG, Sogefi S.p.A., NHK Spring Co., Ltd., BWI Group, Multimatic Inc., Hendrickson Holdings, Inc., Gabriel India Limited, Rassini, S.A.B. de C.V., F-TECH INC., and Benteler International AG.
Key Developments:
In June 2026, Tenneco announced the completion of a fully automated Monroe® Full Active suspension (FAS) actuators production line at its Suzhou facility in China, accelerating its local manufacturing of electronically controlled active damping systems for intelligent electric vehicles.
In June 2026, ZF demonstrated its unified commercial vehicle chassis software architecture at its CV Tech Day 2026, integrating electronic suspension control, steering, and braking into a single software-defined vehicle platform.
In May 2026, consumer electronics and automotive Tier-1 supplier Luxshare agreed to acquire all equity in BWI Group's controlling shareholder entity, securing control of BWI's global chassis and magnetorheological (MR) active damper production footprint to accelerate steer-by-wire and active suspension commercialization.
In February 2026, Hendrickson showcased its advanced vocational suspension lineup at CONEXPO-CON/AGG 2026, highlighting the HAULMAAX® EX heavy-duty rubber suspension and PRIMAAX® EX severe-duty air suspension systems for vocational truck rear drive axles.
Components Covered:
• Coil Springs
• Leaf Springs
• Air Springs
• Shock Absorbers and Dampers
• Struts
• Control Arms
• Ball Joints
• Stabilizer Bars and Links
• Bushings
• Other Components
Suspension Configurations Covered:
• Independent Suspension
• Dependent Suspension
• Semi-Independent Suspension
System Types Covered:
• Passive Suspension Systems
• Semi-Active Suspension Systems
• Active Suspension Systems
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles (LCVs)
• Heavy Commercial Vehicles (HCVs)
• Off-Highway Vehicles
• Two-Wheelers
Propulsions Covered:
• Internal Combustion Engine Vehicles (ICE)
• Hybrid Electric Vehicles (HEV)
• Plug-in Hybrid Electric Vehicles (PHEV)
• Battery Electric Vehicles (BEV)
• Fuel Cell Electric Vehicles (FCEV)
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Suspension Market, By Component
5.1 Coil Springs
5.2 Leaf Springs
5.3 Air Springs
5.4 Shock Absorbers and Dampers
5.5 Struts
5.6 Control Arms
5.7 Ball Joints
5.8 Stabilizer Bars and Links
5.9 Bushings
5.10 Other Components
6 Global Automotive Suspension Market, By Suspension Configuration
6.1 Independent Suspension
6.1.1 MacPherson Strut
6.1.2 Double Wishbone
6.1.3 Multi-Link
6.1.4 Trailing Arm
6.1.5 Other Independent Configurations
6.2 Dependent Suspension
6.2.1 Solid Axle
6.2.2 Leaf Spring Suspension
6.2.3 Other Dependent Configurations
6.3 Semi-Independent Suspension
6.3.1 Torsion Beam
6.3.2 Other Semi-Independent Configurations
7 Global Automotive Suspension Market, By System Type
7.1 Passive Suspension Systems
7.2 Semi-Active Suspension Systems
7.3 Active Suspension Systems
8 Global Automotive Suspension Market, By Vehicle Type
8.1 Passenger Cars
8.1.1 Hatchbacks
8.1.2 Sedans
8.1.3 SUVs and Crossovers
8.1.4 Luxury and Premium Vehicles
8.2 Light Commercial Vehicles (LCVs)
8.3 Heavy Commercial Vehicles (HCVs)
8.3.1 Trucks
8.3.2 Buses and Coaches
8.4 Off-Highway Vehicles
8.4.1 Construction Equipment
8.4.2 Agricultural Vehicles
8.4.3 Mining Vehicles
8.4.4 Other Off-Highway Vehicles
8.5 Two-Wheelers
9 Global Automotive Suspension Market, By Propulsion
9.1 Internal Combustion Engine Vehicles (ICE)
9.2 Hybrid Electric Vehicles (HEV)
9.3 Plug-in Hybrid Electric Vehicles (PHEV)
9.4 Battery Electric Vehicles (BEV)
9.5 Fuel Cell Electric Vehicles (FCEV)
10 Global Automotive Suspension Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 ZF Friedrichshafen AG
13.2 Tenneco Inc.
13.3 thyssenkrupp AG
13.4 KYB Corporation
13.5 Continental AG
13.6 HL Mando Corporation
13.7 Marelli Holdings Co., Ltd.
13.8 Hitachi Astemo, Ltd.
13.9 Schaeffler AG
13.10 Sogefi S.p.A.
13.11 NHK Spring Co., Ltd.
13.12 BWI Group
13.13 Multimatic Inc.
13.14 Hendrickson Holdings, Inc.
13.15 Gabriel India Limited
13.16 Rassini, S.A.B. de C.V.
13.17 F-TECH INC.
13.18 Benteler International AG
List of Tables
1 Global Automotive Suspension Market Outlook, By Region (2023–2034) ($MN)
2 Global Automotive Suspension Market Outlook, By Component (2023–2034) ($MN)
3 Global Automotive Suspension Market Outlook, By Coil Springs (2023–2034) ($MN)
4 Global Automotive Suspension Market Outlook, By Leaf Springs (2023–2034) ($MN)
5 Global Automotive Suspension Market Outlook, By Air Springs (2023–2034) ($MN)
6 Global Automotive Suspension Market Outlook, By Shock Absorbers and Dampers (2023–2034) ($MN)
7 Global Automotive Suspension Market Outlook, By Struts (2023–2034) ($MN)
8 Global Automotive Suspension Market Outlook, By Control Arms (2023–2034) ($MN)
9 Global Automotive Suspension Market Outlook, By Ball Joints (2023–2034) ($MN)
10 Global Automotive Suspension Market Outlook, By Stabilizer Bars and Links (2023–2034) ($MN)
11 Global Automotive Suspension Market Outlook, By Bushings (2023–2034) ($MN)
12 Global Automotive Suspension Market Outlook, By Other Components (2023–2034) ($MN)
13 Global Automotive Suspension Market Outlook, By Suspension Configuration (2023–2034) ($MN)
14 Global Automotive Suspension Market Outlook, By Independent Suspension (2023–2034) ($MN)
15 Global Automotive Suspension Market Outlook, By MacPherson Strut (2023–2034) ($MN)
16 Global Automotive Suspension Market Outlook, By Double Wishbone (2023–2034) ($MN)
17 Global Automotive Suspension Market Outlook, By Multi-Link (2023–2034) ($MN)
18 Global Automotive Suspension Market Outlook, By Trailing Arm (2023–2034) ($MN)
19 Global Automotive Suspension Market Outlook, By Other Independent Configurations (2023–2034) ($MN)
20 Global Automotive Suspension Market Outlook, By Dependent Suspension (2023–2034) ($MN)
21 Global Automotive Suspension Market Outlook, By Solid Axle (2023–2034) ($MN)
22 Global Automotive Suspension Market Outlook, By Leaf Spring Suspension (2023–2034) ($MN)
23 Global Automotive Suspension Market Outlook, By Other Dependent Configurations (2023–2034) ($MN)
24 Global Automotive Suspension Market Outlook, By Semi-Independent Suspension (2023–2034) ($MN)
25 Global Automotive Suspension Market Outlook, By Torsion Beam (2023–2034) ($MN)
26 Global Automotive Suspension Market Outlook, By Other Semi-Independent Configurations (2023–2034) ($MN)
27 Global Automotive Suspension Market Outlook, By System Type (2023–2034) ($MN)
28 Global Automotive Suspension Market Outlook, By Passive Suspension Systems (2023–2034) ($MN)
29 Global Automotive Suspension Market Outlook, By Semi-Active Suspension Systems (2023–2034) ($MN)
30 Global Automotive Suspension Market Outlook, By Active Suspension Systems (2023–2034) ($MN)
31 Global Automotive Suspension Market Outlook, By Vehicle Type (2023–2034) ($MN)
32 Global Automotive Suspension Market Outlook, By Passenger Cars (2023–2034) ($MN)
33 Global Automotive Suspension Market Outlook, By Hatchbacks (2023–2034) ($MN)
34 Global Automotive Suspension Market Outlook, By Sedans (2023–2034) ($MN)
35 Global Automotive Suspension Market Outlook, By SUVs and Crossovers (2023–2034) ($MN)
36 Global Automotive Suspension Market Outlook, By Luxury and Premium Vehicles (2023–2034) ($MN)
37 Global Automotive Suspension Market Outlook, By Light Commercial Vehicles (LCVs) (2023–2034) ($MN)
38 Global Automotive Suspension Market Outlook, By Heavy Commercial Vehicles (HCVs) (2023–2034) ($MN)
39 Global Automotive Suspension Market Outlook, By Trucks (2023–2034) ($MN)
40 Global Automotive Suspension Market Outlook, By Buses and Coaches (2023–2034) ($MN)
41 Global Automotive Suspension Market Outlook, By Off-Highway Vehicles (2023–2034) ($MN)
42 Global Automotive Suspension Market Outlook, By Construction Equipment (2023–2034) ($MN)
43 Global Automotive Suspension Market Outlook, By Agricultural Vehicles (2023–2034) ($MN)
44 Global Automotive Suspension Market Outlook, By Mining Vehicles (2023–2034) ($MN)
45 Global Automotive Suspension Market Outlook, By Other Off-Highway Vehicles (2023–2034) ($MN)
46 Global Automotive Suspension Market Outlook, By Two-Wheelers (2023–2034) ($MN)
47 Global Automotive Suspension Market Outlook, By Propulsion (2023–2034) ($MN)
48 Global Automotive Suspension Market Outlook, By Internal Combustion Engine Vehicles (ICE) (2023–2034) ($MN)
49 Global Automotive Suspension Market Outlook, By Hybrid Electric Vehicles (HEV) (2023–2034) ($MN)
50 Global Automotive Suspension Market Outlook, By Plug-in Hybrid Electric Vehicles (PHEV) (2023–2034) ($MN)
51 Global Automotive Suspension Market Outlook, By Battery Electric Vehicles (BEV) (2023–2034) ($MN)
52 Global Automotive Suspension Market Outlook, By Fuel Cell Electric Vehicles (FCEV) (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
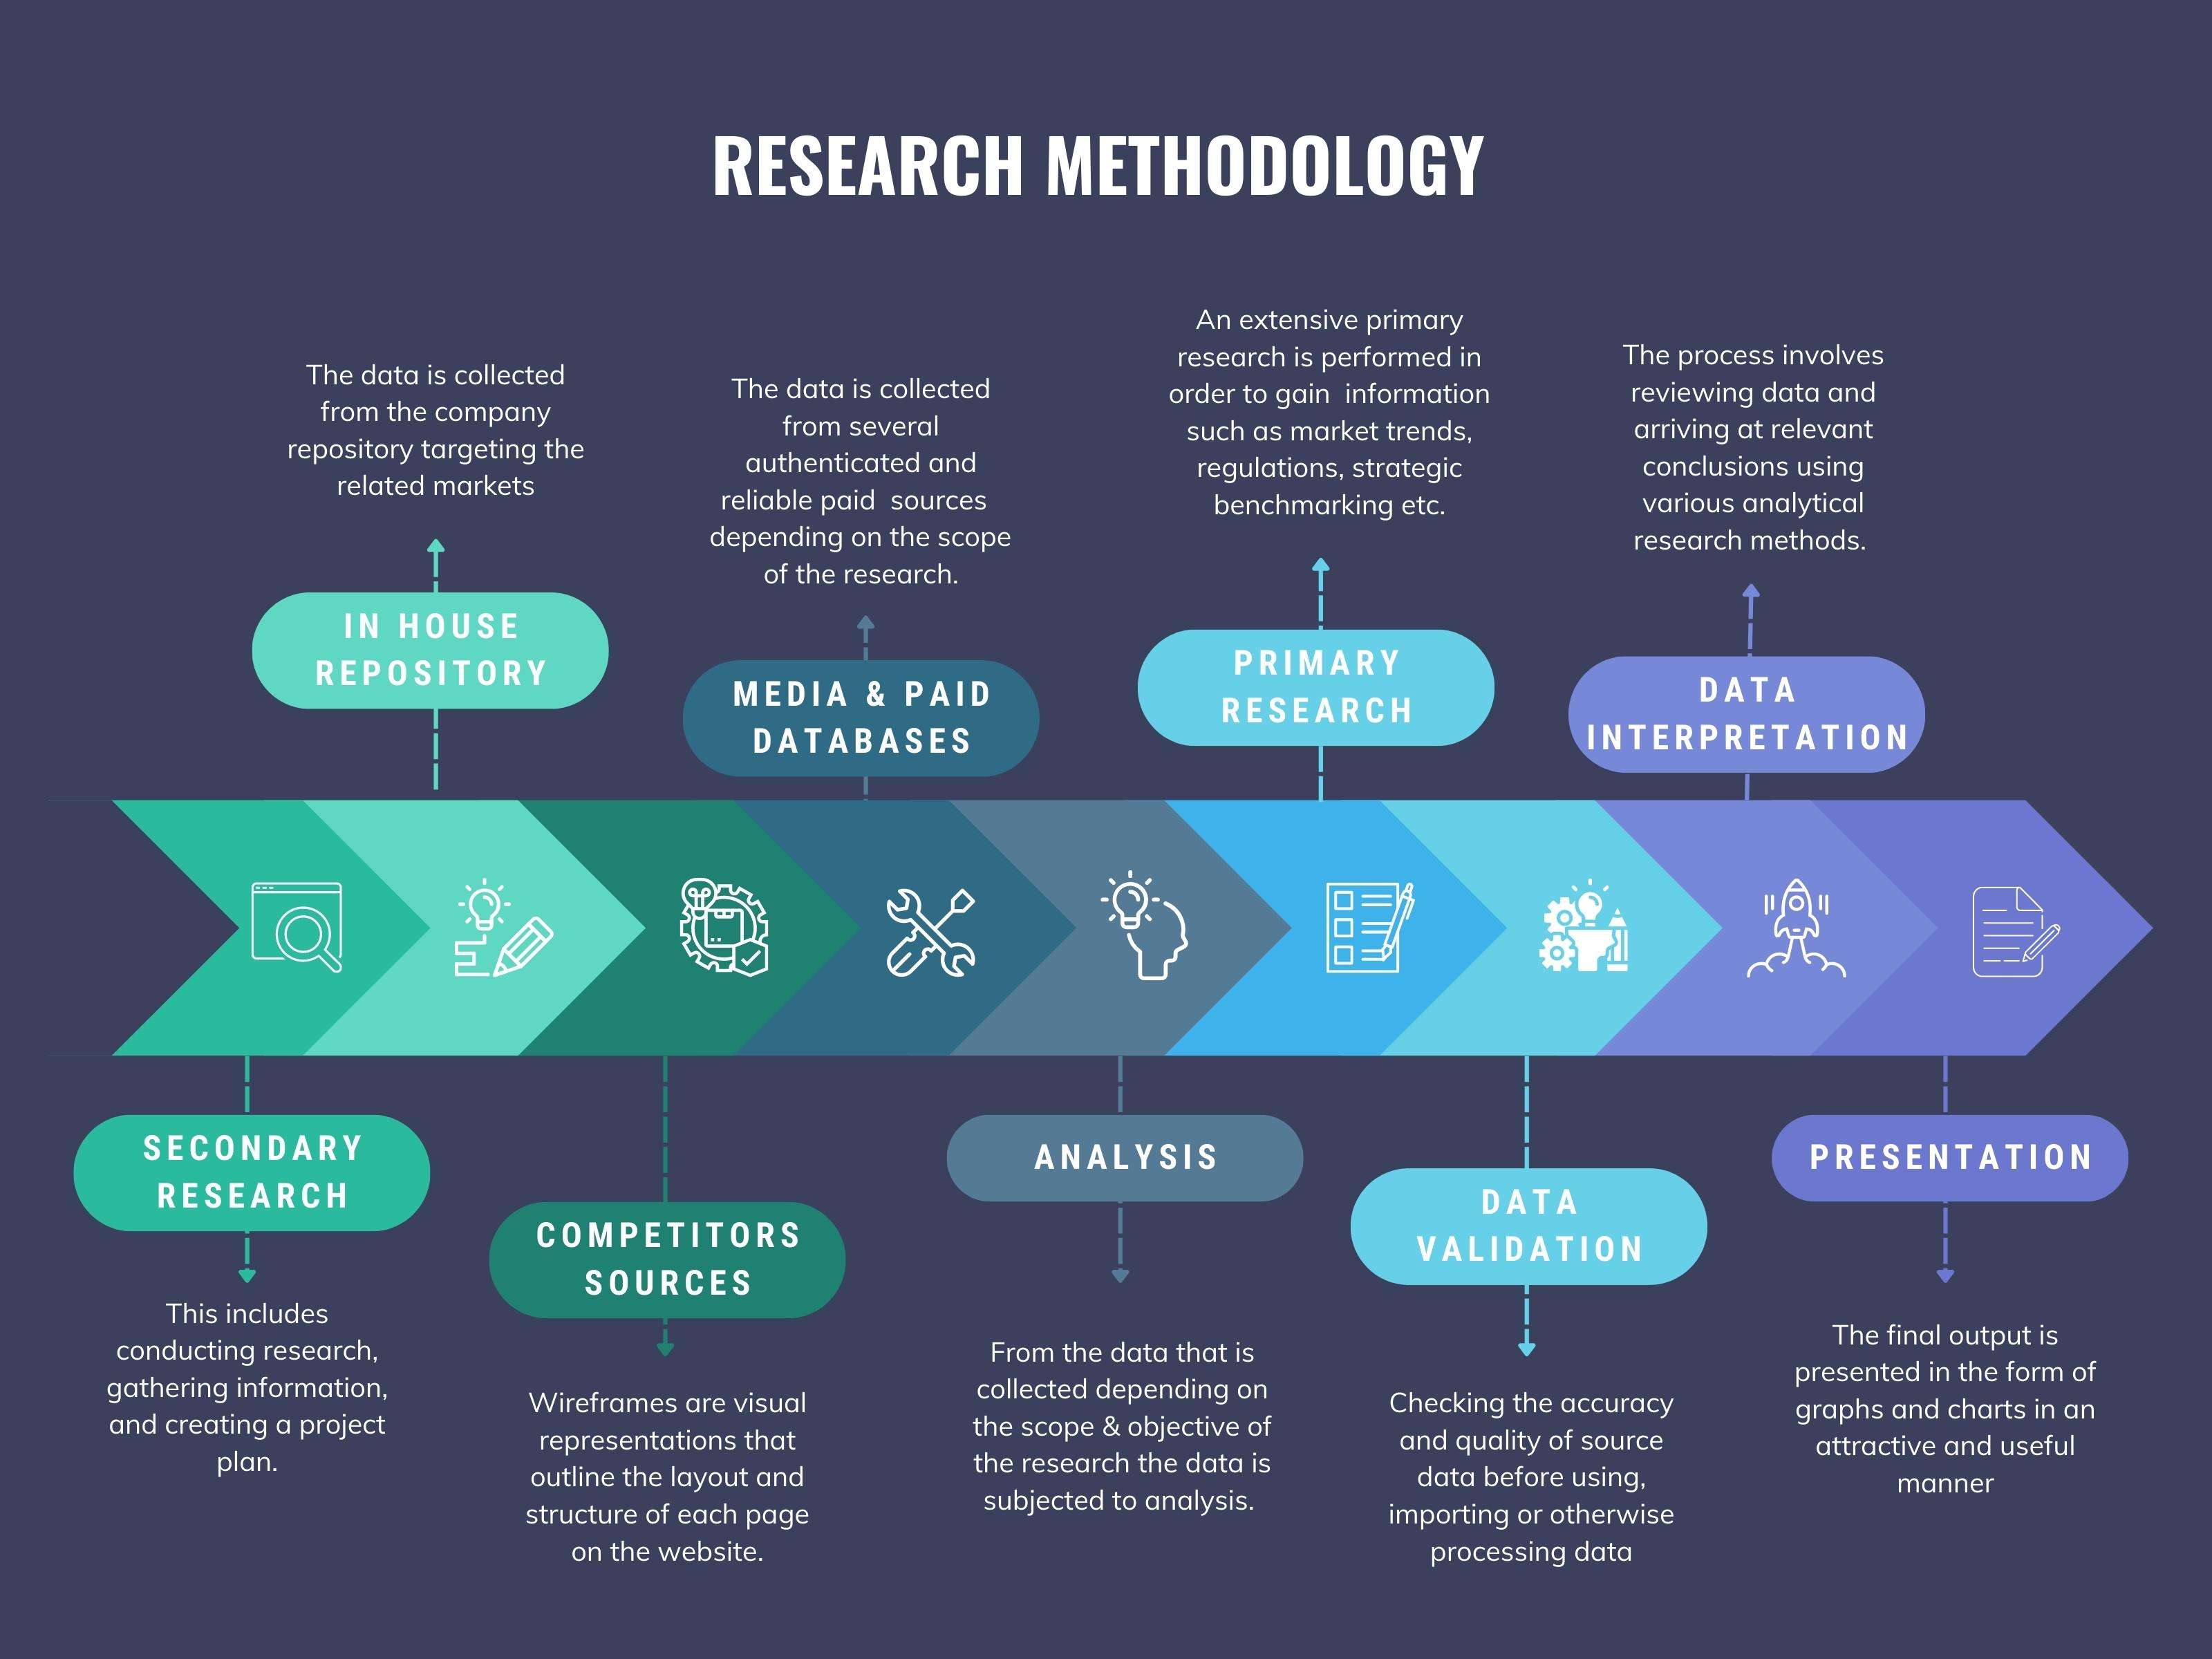
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.