Cargo And Freighter Aircraft Conversion And Leasing Market
Cargo & Freighter Aircraft Conversion & Leasing Market Forecasts To 2034 - Global Analysis By Aircraft Type (Narrowbody Aircraft, Widebody Aircraft and Regional Aircraft), Conversion Type, Aircraft Model, Aircraft Source, Leasing Model, Lease Financing Arrangement, Leasing Duration, Application, End User and By Geography
According to Stratistics MRC, the Global Cargo and Freighter Aircraft Conversion and Leasing Market is accounted for $7.7 billion in 2026 and is expected to reach $12.6 billion by 2034 growing at a CAGR of 6.3% during the forecast period. The Cargo and Freighter Aircraft Conversion and Leasing Market involves modifying passenger planes for cargo operations and supplying freighter aircraft through leasing services. Growth is supported by rising e-commerce activity, expanding cross-border commerce, and increasing requirements for efficient air cargo delivery. Converting existing aircraft into freighters allows operators to maximize asset utilization, extend service life, and avoid the high costs of acquiring new cargo aircraft. Leasing arrangements help cargo carriers manage financial commitments, adjust fleet capacity, and respond to changing freight demand. The market includes aircraft leasing companies, conversion providers, maintenance organizations, and freight operators supporting global air transportation networks.
Market Dynamics:
Driver:
Increasing Demand for Air Cargo Transportation
Rising requirements for air freight services are supporting growth in the Cargo and Freighter Aircraft Conversion and Leasing Market. Businesses across manufacturing, healthcare, electronics, and distribution industries rely on aircraft to move valuable or time-critical shipments between domestic and international destinations. Expanding global commerce and increasingly interconnected supply chains further increase the importance of reliable air cargo services. To accommodate higher shipment volumes, freight operators must expand capacity and maintain dependable delivery schedules. Aircraft conversion allows companies to repurpose passenger planes for cargo operations, while leasing provides access to additional freighters. These solutions help improve fleet availability and accommodate evolving transportation needs.
Restraint:
High Aircraft Conversion and Maintenance Costs
The substantial expenses associated with aircraft conversion and maintenance can restrict the growth of the Cargo and Freighter Aircraft Conversion and Leasing Market. Passenger-to-freighter modification involves complex engineering work, structural strengthening, cargo access installation, technical inspections, and compliance approvals. These requirements increase project expenditure and necessitate highly qualified personnel and specialized facilities. Older aircraft may require additional repairs or component replacements, further increasing costs. Higher investment requirements can reduce returns for aircraft owners and conversion providers while raising leasing expenses for cargo operators. Consequently, smaller market participants may delay fleet investments, particularly when financial resources are limited or freight market conditions remain unpredictable.
Opportunity:
Adoption of Fuel-Efficient Technologies and Sustainable Aviation Practices
Increasing attention to sustainability and operating efficiency offers new development prospects for aircraft conversion and leasing providers. Freight companies are examining fuel consumption, emissions, and environmental compliance when making fleet decisions. Conversion specialists can investigate suitable technical improvements, structural weight reductions, and other modifications that support more efficient aircraft operations. Lessors may attract customers by providing freighters that meet relevant operational efficiency requirements and contribute to corporate sustainability goals. Collaboration among engineering firms, maintenance organizations, aircraft manufacturers, and technology companies can facilitate innovation. Such efforts may improve the commercial appeal of converted aircraft and help operators pursue cost-effective fleet renewal strategies.
Threat:
Tightening Environmental Regulations and Sustainability Requirements
Increasing environmental expectations and stricter aviation policies may create significant challenges for aircraft conversion and leasing companies. Regulations concerning carbon emissions, aircraft noise, and fuel consumption can increase compliance responsibilities for cargo operators. Some converted aircraft, particularly older models, may find it more difficult to meet changing environmental standards than newer, more efficient freighters. Businesses may need to invest in additional technical improvements, revise operating practices, or replace aircraft earlier than anticipated. Restrictions at particular airports could further limit deployment opportunities. These factors may increase costs, reduce fleet flexibility, and affect the long-term financial attractiveness of certain conversion and leasing investments.
Covid-19 Impact:
The COVID-19 outbreak reshaped the Cargo and Freighter Aircraft Conversion and Leasing Market by weakening passenger air travel and highlighting the importance of cargo transportation. Travel restrictions left many passenger aircraft underutilized, encouraging operators to consider converting appropriate aircraft for freight operations. Increased shipments of healthcare products, medicines, protective equipment, and essential commodities created additional demand for air cargo capacity. Nevertheless, disrupted supply chains, limited workforce availability, approval delays, and economic uncertainty complicated conversion projects and leasing decisions. Airlines and lessors had to adjust their operating strategies, while the crisis strengthened long-term interest in dedicated cargo aircraft and adaptable leasing arrangements.
The Narrowbody Aircraft segment is expected to be the largest during the forecast period
The Narrowbody Aircraft segment is expected to account for the largest market share during the forecast period, driven by the suitability of narrowbody aircraft for domestic routes, regional freight distribution, and short- to medium-distance cargo transportation. Relatively economical operations, efficient fuel consumption, and compatibility with a broad range of airports make these aircraft appealing to freight carriers and lessors. Converting passenger narrowbody aircraft into dedicated freighters allows operators to increase cargo capacity without depending entirely on newly manufactured aircraft. Their versatility and ability to serve diverse routes further strengthen demand for conversion services and leasing solutions.
The E-Commerce Logistics Operators segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the E-Commerce Logistics Operators segment is predicted to witness the highest growth rate, Increasing online purchasing activity, international e-commerce transactions, and demand for rapid order fulfillment are creating greater requirements for efficient air freight services. Logistics operators are expanding their transportation capabilities to accommodate growing package volumes, peak-season demand, and cross-border deliveries. Converting passenger aircraft into freighters offers an effective way to expand cargo capacity, while leasing helps businesses obtain aircraft without committing significant capital to ownership. Furthermore, the development of distribution hubs, fulfillment facilities, and international shipping networks is expected to strengthen demand for cargo aircraft conversion and leasing services.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, Its established freight transportation network, expanding online retail sector, and substantial express shipping activity support regional market growth. The concentration of cargo carriers, aircraft lessors, aircraft conversion companies, and maintenance organizations strengthens the industry ecosystem. The United States plays an important role in connecting domestic distribution networks with international trade routes, creating demand for additional freighter capacity. Furthermore, developed airport infrastructure, specialized engineering expertise, and growing requirements for reliable air cargo transportation encourage operators to invest in aircraft conversion programs and flexible leasing arrangements.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, Expanding online retail, rising cross-border commerce, and increasing demand for rapid parcel transportation are generating greater requirements for cargo aircraft. Industrial development and investments in airports, logistics hubs, and distribution networks across China, India, and Southeast Asia are further supporting market expansion. Regional airlines and freight service providers are exploring efficient ways to increase aircraft capacity and respond to changing transportation needs. Passenger-to-freighter conversions and leasing arrangements can help operators manage investment costs while strengthening regional and international freight networks.
Key players in the market
Some of the key players in Cargo and Freighter Aircraft Conversion and Leasing Market include AerCap Holdings N.V., Air Transport Services Group, Boeing, Israel Aerospace Industries, Elbe Flugzeugwerke GmbH, Aeronautical Engineers, Inc., Mammoth Freighters, Precision Aircraft Solutions, ST Engineering, Air Lease Corporation, Avolon, BBAM Limited Partnership, Altavair, Titan Aviation Leasing, AviaAM Leasing, Asia Pacific Aviation Leasing, PEMCO Conv and STAECO.
Key Developments:
In July 2026, AerCap Cargo signed agreements to lease three Boeing 777-300ERSF converted freighters to China Southern Air Logistics. The aircraft are scheduled for delivery beginning in October 2027, strengthening the cargo operator's planned widebody freighter capacity.
In June 2026, ATSG announced a long-term lease agreement for an Airbus A330P2F owned by its subsidiary Cargo Aircraft Management. The aircraft is expected to enter service in the fourth quarter of 2026, supporting Cathay Cargo's regional freight network across mainland China and other Asian destinations.
In February 2026, EFW signed an agreement to convert an Airbus A330 passenger aircraft into a freighter for the aircraft lessor. Work was planned at EFW's partner facility in China, with engineering planning and certification supported by EFW's Dresden headquarters.
Aircraft Types Covered:
• Narrowbody Aircraft
• Widebody Aircraft
• Regional Aircraft
Conversion Types Covered:
• Passenger-to-Freighter Conversion
• Passenger-to-Combi Conversion
• Quick-Change Conversion
Aircraft Models Covered:
• Boeing 737 Family
• Boeing 757 Family
• Boeing 767 Family
• Boeing 777 Family
• Airbus A320 Family
• Airbus A330 Family
• Other Eligible Aircraft Models
Aircraft Sources Covered:
• Passenger-to-Freighter Converted Aircraft
• Previously Converted Freighter Aircraft
• Factory-Built Freighter Aircraft Available for Lease
Leasing Models Covered:
• Dry Lease
• Wet Lease
• Damp Lease
Lease Financing Arrangements Covered:
• Operating Lease
• Finance Lease
• Sale-and-Leaseback
Leasing Durations Covered:
• Short-Term Lease
• Medium-Term Lease
• Long-Term Lease
Applications Covered:
• General Air Freight Transportation
• Express and Parcel Delivery
• E-Commerce Cargo Transportation
• Industrial and Heavy Cargo Transportation
• Perishable and Temperature-Sensitive Cargo Transportation
• Humanitarian and Emergency Relief Operations
• Military and Government Airlift
End Users Covered:
• Dedicated Cargo Airlines
• Express Parcel and Courier Operators
• Integrated Logistics Providers
• Freight Forwarders
• E-Commerce Logistics Operators
• Aircraft Leasing Companies
• Postal and Mail Service Operators
• Government and Defense Operators
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Aircraft Type
5.1 Narrowbody Aircraft
5.2 Widebody Aircraft
5.3 Regional Aircraft
6 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Conversion Type
6.1 Passenger-to-Freighter Conversion
6.2 Passenger-to-Combi Conversion
6.3 Quick-Change Conversion
7 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Aircraft Model
7.1 Boeing 737 Family
7.2 Boeing 757 Family
7.3 Boeing 767 Family
7.4 Boeing 777 Family
7.5 Airbus A320 Family
7.6 Airbus A330 Family
7.7 Other Eligible Aircraft Models
8 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Aircraft Source
8.1 Passenger-to-Freighter Converted Aircraft
8.2 Previously Converted Freighter Aircraft
8.3 Factory-Built Freighter Aircraft Available for Lease
9 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Leasing Model
9.1 Dry Lease
9.2 Wet Lease
9.3 Damp Lease
10 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Lease Financing Arrangement
10.1 Operating Lease
10.2 Finance Lease
10.3 Sale-and-Leaseback
11 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Leasing Duration
11.1 Short-Term Lease
11.2 Medium-Term Lease
11.3 Long-Term Lease
12 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Application
12.1 General Air Freight Transportation
12.2 Express and Parcel Delivery
12.3 E-Commerce Cargo Transportation
12.4 Industrial and Heavy Cargo Transportation
12.5 Perishable and Temperature-Sensitive Cargo Transportation
12.6 Humanitarian and Emergency Relief Operations
12.7 Military and Government Airlift
13 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By End User
13.1 Dedicated Cargo Airlines
13.2 Express Parcel and Courier Operators
13.3 Integrated Logistics Providers
13.4 Freight Forwarders
13.5 E-Commerce Logistics Operators
13.6 Aircraft Leasing Companies
13.7 Postal and Mail Service Operators
13.8 Government and Defense Operators
14 Global Cargo & Freighter Aircraft Conversion & Leasing Market, By Geography
14.1 North America
14.1.1 United States
14.1.2 Canada
14.1.3 Mexico
14.2 Europe
14.2.1 United Kingdom
14.2.2 Germany
14.2.3 France
14.2.4 Italy
14.2.5 Spain
14.2.6 Netherlands
14.2.7 Belgium
14.2.8 Sweden
14.2.9 Switzerland
14.2.10 Poland
14.2.11 Rest of Europe
14.3 Asia Pacific
14.3.1 China
14.3.2 Japan
14.3.3 India
14.3.4 South Korea
14.3.5 Australia
14.3.6 Indonesia
14.3.7 Thailand
14.3.8 Malaysia
14.3.9 Singapore
14.3.10 Vietnam
14.3.11 Rest of Asia Pacific
14.4 South America
14.4.1 Brazil
14.4.2 Argentina
14.4.3 Colombia
14.4.4 Chile
14.4.5 Peru
14.4.6 Rest of South America
14.5 Rest of the World (RoW)
14.5.1 Middle East
14.5.1.1 Saudi Arabia
14.5.1.2 United Arab Emirates
14.5.1.3 Qatar
14.5.1.4 Israel
14.5.1.5 Rest of Middle East
14.5.2 Africa
14.5.2.1 South Africa
14.5.2.2 Egypt
14.5.2.3 Morocco
14.5.2.4 Rest of Africa
15 Strategic Market Intelligence
15.1 Industry Value Network and Supply Chain Assessment
15.2 White-Space and Opportunity Mapping
15.3 Product Evolution and Market Life Cycle Analysis
15.4 Channel, Distributor, and Go-to-Market Assessment
16 Industry Developments and Strategic Initiatives
16.1 Mergers and Acquisitions
16.2 Partnerships, Alliances, and Joint Ventures
16.3 New Product Launches and Certifications
16.4 Capacity Expansion and Investments
16.5 Other Strategic Initiatives
17 Company Profiles
17.1 AerCap Holdings N.V.
17.2 Air Transport Services Group
17.3 Boeing
17.4 Israel Aerospace Industries
17.5 Elbe Flugzeugwerke GmbH
17.6 Aeronautical Engineers, Inc.
17.7 Mammoth Freighters
17.8 Precision Aircraft Solutions
17.9 ST Engineering
17.10 Air Lease Corporation
17.11 Avolon
17.12 BBAM Limited Partnership
17.13 Altavair
17.14 Titan Aviation Leasing
17.15 AviaAM Leasing
17.16 Asia Pacific Aviation Leasing
17.17 PEMCO Conv
17.18 STAECO
List of Tables
1 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Region (2023-2034) ($MN)
2 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Aircraft Type (2023-2034) ($MN)
3 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Narrowbody Aircraft (2023-2034) ($MN)
4 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Widebody Aircraft (2023-2034) ($MN)
5 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Regional Aircraft (2023-2034) ($MN)
6 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Conversion Type (2023-2034) ($MN)
7 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Passenger-to-Freighter Conversion (2023-2034) ($MN)
8 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Passenger-to-Combi Conversion (2023-2034) ($MN)
9 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Quick-Change Conversion (2023-2034) ($MN)
10 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Aircraft Model (2023-2034) ($MN)
11 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Boeing 737 Family (2023-2034) ($MN)
12 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Boeing 757 Family (2023-2034) ($MN)
13 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Boeing 767 Family (2023-2034) ($MN)
14 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Boeing 777 Family (2023-2034) ($MN)
15 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Airbus A320 Family (2023-2034) ($MN)
16 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Airbus A330 Family (2023-2034) ($MN)
17 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Other Eligible Aircraft Models (2023-2034) ($MN)
18 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Aircraft Source (2023-2034) ($MN)
19 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Passenger-to-Freighter Converted Aircraft (2023-2034) ($MN)
20 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Previously Converted Freighter Aircraft (2023-2034) ($MN)
21 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Factory-Built Freighter Aircraft Available for Lease (2023-2034) ($MN)
22 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Leasing Model (2023-2034) ($MN)
23 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Dry Lease (2023-2034) ($MN)
24 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Wet Lease (2023-2034) ($MN)
25 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Damp Lease (2023-2034) ($MN)
26 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Lease Financing Arrangement (2023-2034) ($MN)
27 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Operating Lease (2023-2034) ($MN)
28 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Finance Lease (2023-2034) ($MN)
29 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Sale-and-Leaseback (2023-2034) ($MN)
30 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Leasing Duration (2023-2034) ($MN)
31 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Short-Term Lease (2023-2034) ($MN)
32 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Medium-Term Lease (2023-2034) ($MN)
33 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Long-Term Lease (2023-2034) ($MN)
34 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Application (2023-2034) ($MN)
35 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By General Air Freight Transportation (2023-2034) ($MN)
36 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Express and Parcel Delivery (2023-2034) ($MN)
37 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By E-Commerce Cargo Transportation (2023-2034) ($MN)
38 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Industrial and Heavy Cargo Transportation (2023-2034) ($MN)
39 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Perishable and Temperature-Sensitive Cargo Transportation (2023-2034) ($MN)
40 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Humanitarian and Emergency Relief Operations (2023-2034) ($MN)
41 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Military and Government Airlift (2023-2034) ($MN)
42 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By End User (2023-2034) ($MN)
43 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Dedicated Cargo Airlines (2023-2034) ($MN)
44 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Express Parcel and Courier Operators (2023-2034) ($MN)
45 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Integrated Logistics Providers (2023-2034) ($MN)
46 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Freight Forwarders (2023-2034) ($MN)
47 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By E-Commerce Logistics Operators (2023-2034) ($MN)
48 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Aircraft Leasing Companies (2023-2034) ($MN)
49 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Postal and Mail Service Operators (2023-2034) ($MN)
50 Global Cargo & Freighter Aircraft Conversion & Leasing Market Outlook, By Government and Defense Operators (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
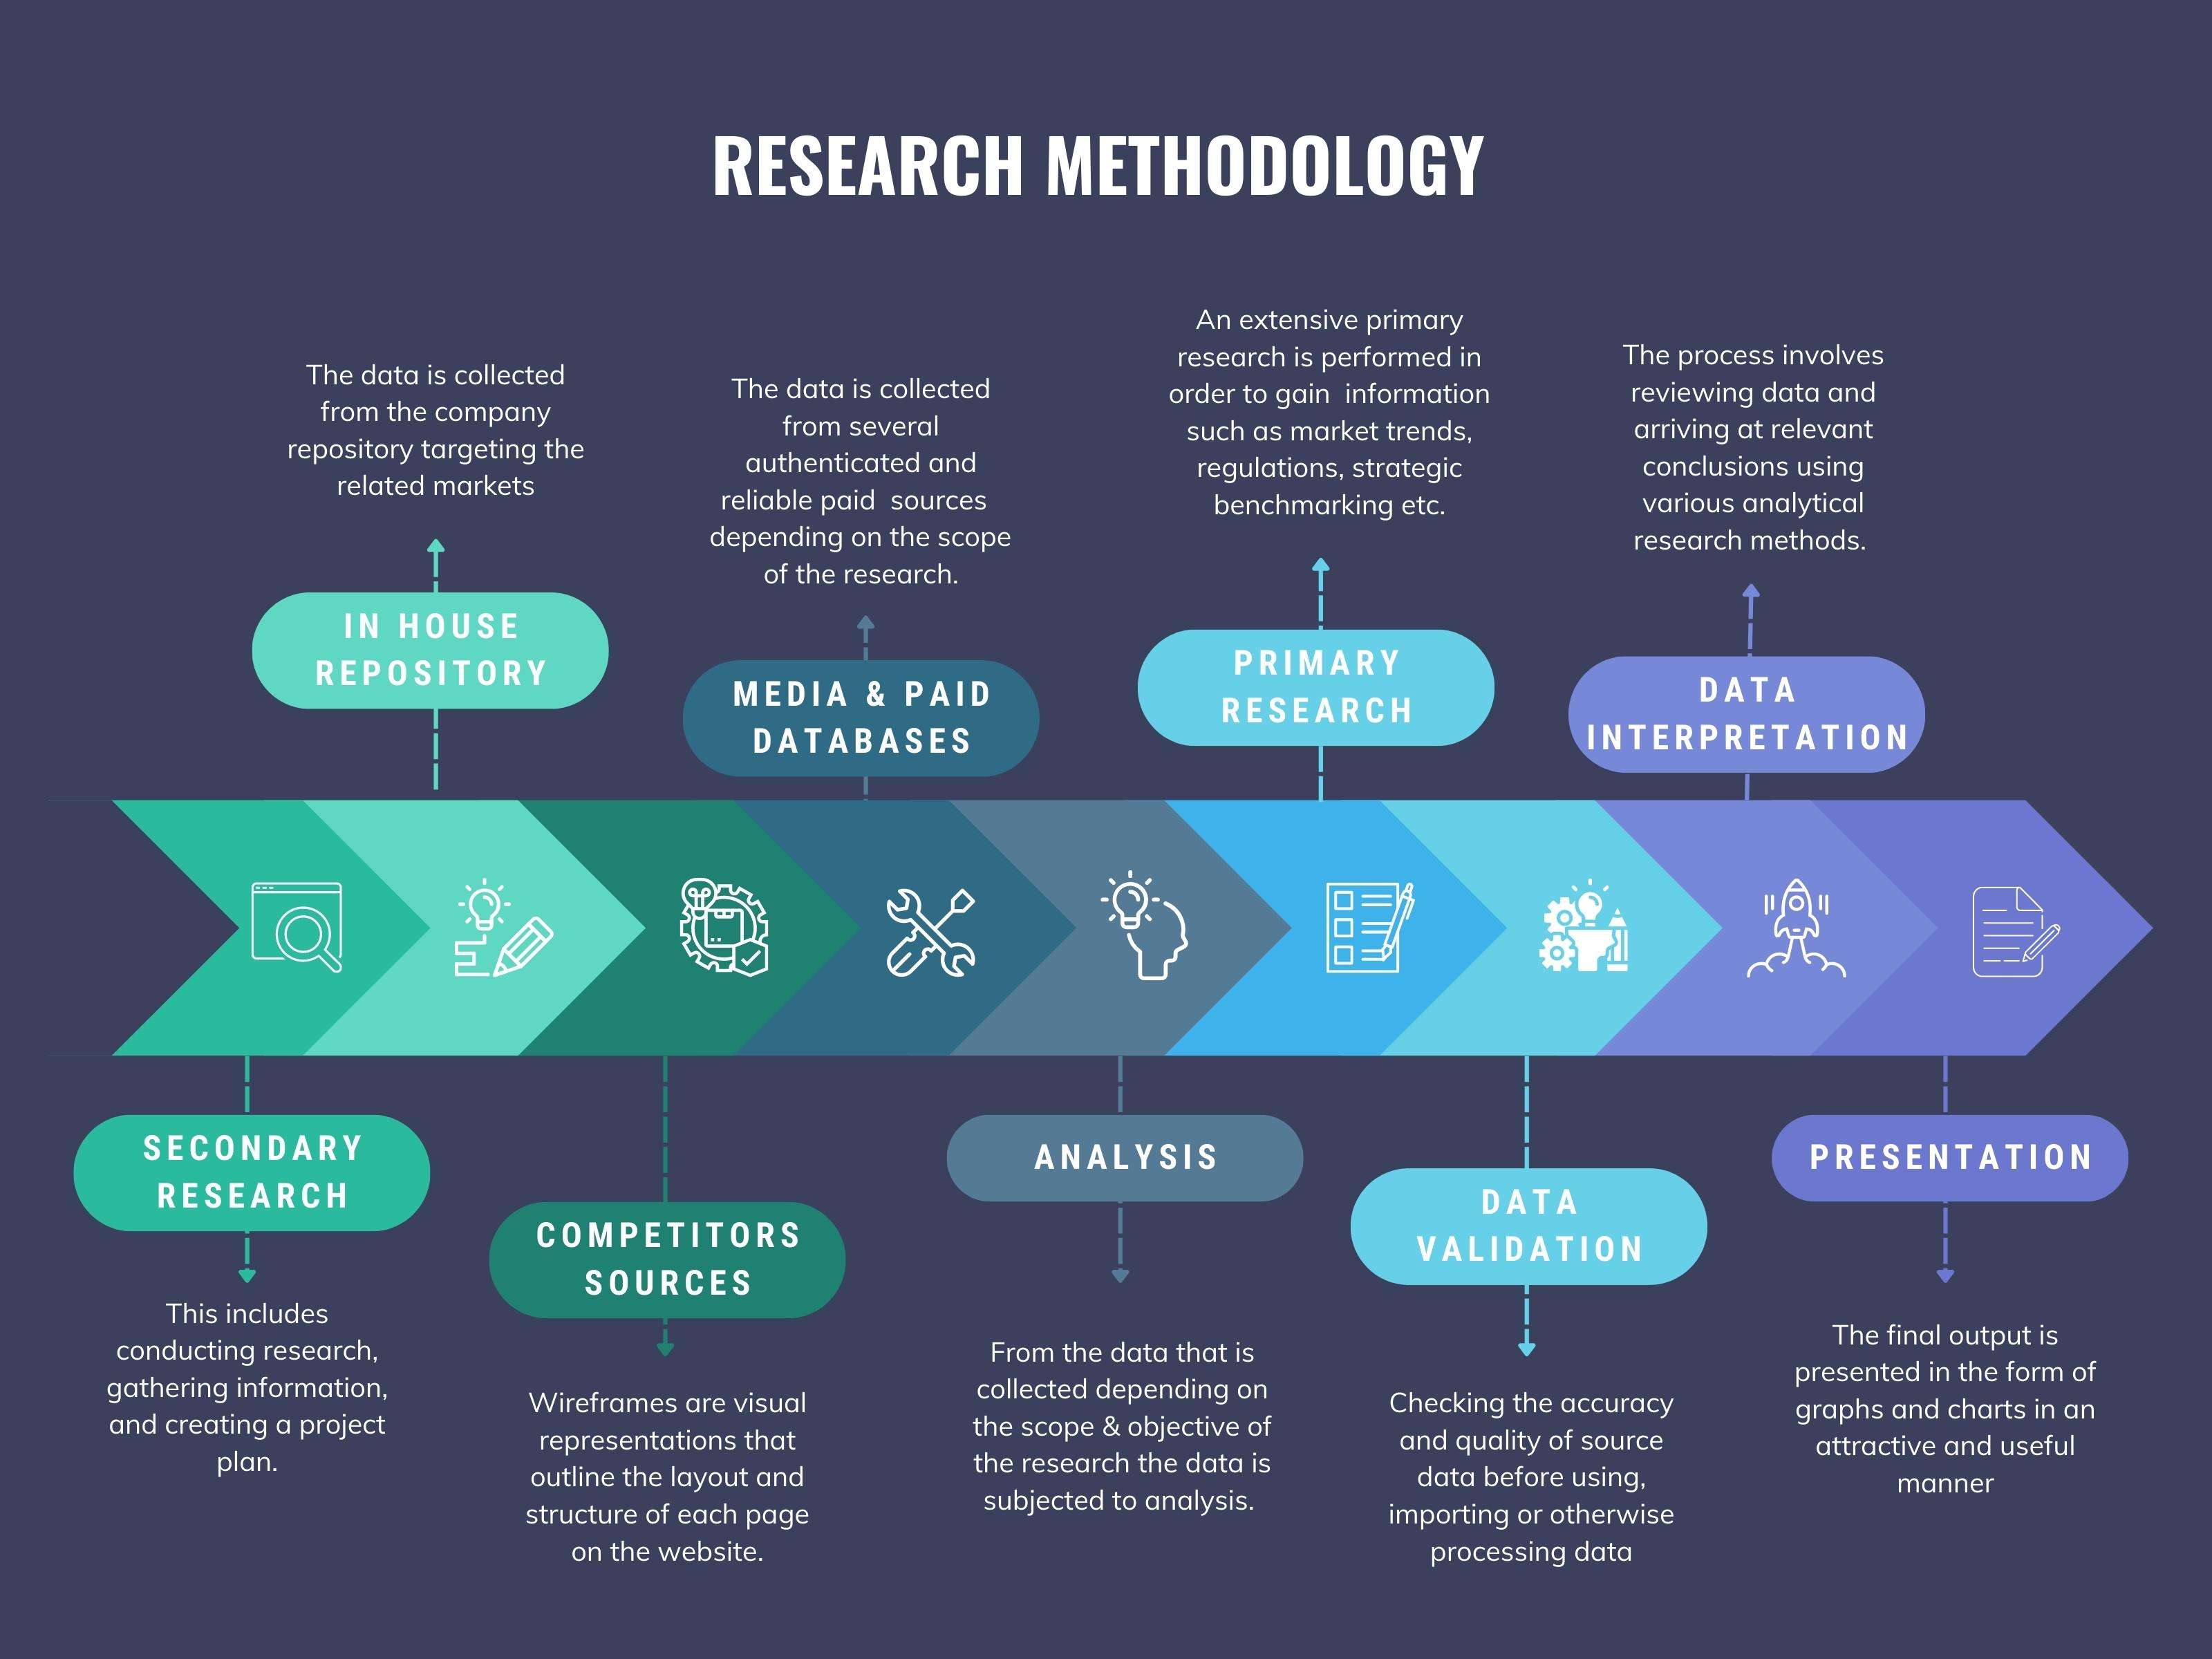
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.