Data Center Gpu Market
Data Center GPU Market Forecasts To 2034 – Global Analysis By GPU Type (Discrete GPUs, Integrated GPUs and Hybrid GPUs), GPU Architecture, Form Factor, Cooling Type, Function, Deployment, Data Center Type, Memory Technology, Application, End User and By Geography
According to Stratistics MRC, the Global Data Center GPU Market is accounted for $150.5 billion in 2026 and is expected to reach $1118.6 billion by 2034 growing at a CAGR of 28.5% during the forecast period. The Data Center GPU Market covers graphics processing technologies developed for intensive data center applications, including artificial intelligence, machine learning, high-performance computing, cloud services, scientific workloads, and analytics. These GPUs enable extensive parallel computation for processing large datasets and complex computational models. The market incorporates GPU hardware, software ecosystems, memory solutions, networking technologies, and related infrastructure. Major applications include AI training and inference, accelerated computing, simulation, virtualization, and enterprise data processing. The competitive landscape includes GPU manufacturers, cloud platforms, and technology companies offering specialized architectures and solutions for advanced data center computing requirements.
Market Dynamics:
Driver:
Increasing Data Processing Requirements
The expanding quantity of data produced by businesses, connected devices, digital services, and software applications is increasing the need for accelerated processing within data centers. Companies must analyze extensive datasets to support business intelligence, cybersecurity, customer insights, recommendation engines, and real-time operational decisions. GPUs can perform large numbers of data-processing operations concurrently, complementing CPUs in computationally intensive analytics and processing workloads. As data-centric applications become increasingly widespread, enterprises and infrastructure providers are adopting accelerated computing systems to address processing requirements. The growing necessity for efficient analysis and handling of large datasets is consequently supporting greater integration of GPU technologies into data center infrastructure.
Restraint:
High Cost of Data Center GPUs
The substantial investment required for sophisticated data center GPUs can limit their adoption across organizations. GPUs designed for intensive AI, machine learning, and high-performance computing workloads generally involve higher procurement costs than standard computing components. Deployment expenses can also extend beyond the GPU itself, encompassing specialized servers, advanced memory, high-speed networking, thermal management, electricity infrastructure, and supporting software. These requirements can significantly increase the overall expenditure associated with GPU-based computing environments. Small and medium-sized businesses or organizations operating with constrained budgets may find large GPU deployments challenging, especially when their workloads do not provide sufficient utilization to justify the considerable infrastructure and equipment investment required.
Opportunity:
Integration of GPUs with Advanced Networking and Memory Technologies
Combining GPUs with advanced memory and networking technologies creates opportunities for developing more capable data center computing platforms. AI and high-performance applications frequently transfer substantial quantities of information among processors, memory, storage, and networking components. GPU manufacturers can work with memory suppliers, networking companies, semiconductor developers, and infrastructure providers to create integrated systems incorporating high-bandwidth memory, fast interconnects, advanced networking, and optimized software. Improved coordination among these components can support communication across large accelerator clusters and demanding workloads. This trend can encourage strategic collaboration, ecosystem development, and integrated platform offerings, allowing technology providers to deliver comprehensive accelerated computing infrastructure for data-intensive applications.
Threat:
Rapid Technological Competition and Product Substitution
Fast innovation across computing and semiconductor technologies can increase substitution risks for data center GPUs. New processor architectures, dedicated AI chips, custom accelerators, neuromorphic technologies, and other emerging solutions are being designed for specialized computational workloads. Advances in these alternatives could enable some applications to meet performance requirements without extensive use of traditional GPUs. Data center operators may consequently compare multiple processor architectures based on workload suitability, power requirements, software support, and total infrastructure costs. Rapid technology cycles can also reduce the effective lifespan of existing solutions, requiring GPU companies to maintain substantial investments in research, architecture development, software platforms, and continuous product innovation.
Covid-19 Impact:
The COVID-19 pandemic affected the Data Center GPU Market through accelerated digitalization, increased remote working, expanded cloud usage, and greater dependence on online platforms. Businesses and institutions adopted cloud-based infrastructure, virtual communication, digital services, and data-intensive applications, increasing requirements for computing resources and data center capacity. However, pandemic-related restrictions disrupted semiconductor production, transportation networks, component sourcing, and hardware deliveries, creating obstacles for GPU availability and infrastructure expansion. Data center operators also encountered operational challenges resulting from workforce limitations and facility restrictions. Consequently, COVID-19 highlighted the importance of advanced computing infrastructure while creating simultaneous supply chain and deployment difficulties for GPU manufacturers and data center operators.
The Discrete GPUs segment is expected to be the largest during the forecast period
The Discrete GPUs segment is expected to account for the largest market share during the forecast period, driven by its dedicated processing resources, high performance, and suitability for computationally intensive data center applications. Unlike integrated solutions, discrete GPUs function separately from CPUs and provide extensive parallel processing capabilities for artificial intelligence, machine learning, analytics, high-performance computing, and scientific workloads. Their ability to scale across multi-GPU configurations allows data centers to address demanding computational requirements efficiently. Growing needs for accelerated processing, sophisticated AI models, extensive datasets, and specialized computing infrastructure are contributing to the increasing deployment of discrete GPUs within advanced data center environments.
The Generative AI segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Generative AI segment is predicted to witness the highest growth rate, supported by the expanding use of large language models, multimodal systems, AI-generated content, and advanced artificial intelligence applications. These workloads require significant computational capabilities for training, model optimization, fine-tuning, and inference, increasing the need for powerful GPUs within data center infrastructure. Cloud providers, technology companies, enterprises, and research institutions are developing accelerated computing environments to accommodate increasingly complex AI models. The broader integration of generative AI into software development, customer support, content production, healthcare, financial services, and other applications is encouraging investment in specialized GPU infrastructure capable of supporting demanding and computationally intensive AI workloads.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, supported by its extensive data center ecosystem, concentration of leading technology companies, and broad adoption of cloud and artificial intelligence technologies. The region benefits from established GPU suppliers, semiconductor manufacturers, cloud platforms, and large data center operators. Increasing deployment of generative AI, machine learning, high-performance computing, analytics, and other demanding workloads is supporting the use of GPU-accelerated infrastructure. The presence of hyperscale facilities and continued investment in advanced computing systems further strengthens regional demand. In addition, mature digital infrastructure, technical expertise, and established technology ecosystems support North America’s prominent position in the market.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, supported by increasing data center capacity, expanding cloud services, and greater adoption of artificial intelligence technologies. Countries throughout the region are developing hyperscale data centers, AI-focused infrastructure, and advanced digital platforms, increasing demand for GPU-accelerated computing resources. Growing applications of generative AI, machine learning, analytics, and high-performance computing are encouraging businesses to adopt sophisticated accelerator solutions. Accelerating digital transformation among enterprises and public-sector organizations is further supporting infrastructure requirements. In addition, developing technology ecosystems and investments in semiconductor manufacturing and data center facilities are creating favorable conditions for expanding GPU deployment across the region.
Key players in the market
Some of the key players in Data Center GPU Market include Intel Corporation, Advanced Micro Devices, Inc., NVIDIA Corporation, Huawei Technologies Co., Ltd., Biren Technology, Moore Threads Technology Co., Ltd., Iluvatar CoreX, Cambricon Technologies Corporation Limited, Jingjia Microelectronics Co., Ltd., Enflame Technology Co., Ltd., MetaX Integrated Circuits Co., Ltd., Alibaba Group Holding Limited, Baidu, Inc., Fujitsu Limited, IBM Corporation, Lenovo Group Limited, Inspur Group and Foxconn Industrial Internet Co., Ltd.
Key Developments:
In July 2026, AMD and Microsoft expanded their long-term strategic partnership, with Microsoft planning to deploy AMD Helios rack-scale systems and next-generation AMD Instinct GPUs on Azure for frontier-model inference and AI services.
In May 2026, NVIDIA and IREN announced a strategic partnership supporting deployment of up to 5 GW of NVIDIA DSX-aligned AI infrastructure across IREN’s data-center pipeline, combining NVIDIA accelerated computing with IREN’s data-center and infrastructure capabilities.
In April 2026, Intel and Google announced a multiyear collaboration to advance AI and cloud infrastructure, including continued use of Intel Xeon processors and expanded co-development of custom ASIC-based infrastructure processing units (IPUs) for large-scale AI infrastructure.
GPU Types Covered:
• Discrete GPUs
• Integrated GPUs
• Hybrid GPUs
GPU Architectures Covered:
• CUDA-Based Architectures
• CDNA-Based Architectures
• Xe-Based Architectures
• Other GPU Architectures
Form Factors Covered:
• Single-Slot GPUs
• Dual-Slot GPUs
• Multi-Slot GPUs
• SXM Modules
• Rack-Scale GPU Systems
Cooling Types Covered:
• Air-Cooled
• Liquid-Cooled
• Immersion-Cooled
Functions Covered:
• AI Training
• AI Inference
• High-Performance Computing
• Graphics and Visualization
• Media and Video Processing
Deployments Covered:
• Cloud
• On-Premises
Data Center Types Covered:
• Hyperscale Data Centers
• Enterprise Data Centers
• Colocation Data Centers
• Edge Data Centers
Memory Technologies Covered:
• HBM
• GDDR
• Other Memory Technologies
Applications Covered:
• Generative AI
• Machine Learning
• Data Analytics
• High-Performance Computing
• Graphics Rendering
• Media Processing
• Virtualization and VDI
End Users Covered:
• Cloud Service Providers
• Enterprises
• Government and Research Institutions
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Data Center GPU Market, By GPU Type
5.1 Discrete GPUs
5.2 Integrated GPUs
5.3 Hybrid GPUs
6 Global Data Center GPU Market, By GPU Architecture
6.1 CUDA-Based Architectures
6.2 CDNA-Based Architectures
6.3 Xe-Based Architectures
6.4 Other GPU Architectures
7 Global Data Center GPU Market, By Form Factor
7.1 Single-Slot GPUs
7.2 Dual-Slot GPUs
7.3 Multi-Slot GPUs
7.4 SXM Modules
7.5 Rack-Scale GPU Systems
8 Global Data Center GPU Market, By Cooling Type
8.1 Air-Cooled
8.2 Liquid-Cooled
8.3 Immersion-Cooled
9 Global Data Center GPU Market, By Function
9.1 AI Training
9.2 AI Inference
9.3 High-Performance Computing
9.4 Graphics and Visualization
9.5 Media and Video Processing
10 Global Data Center GPU Market, By Deployment
10.1 Cloud
10.2 On-Premises
11 Global Data Center GPU Market, By Data Center Type
11.1 Hyperscale Data Centers
11.2 Enterprise Data Centers
11.3 Colocation Data Centers
11.4 Edge Data Centers
12 Global Data Center GPU Market, By Memory Technology
12.1 HBM
12.2 GDDR
12.3 Other Memory Technologies
13 Global Data Center GPU Market, By Application
13.1 Generative AI
13.2 Machine Learning
13.3 Data Analytics
13.4 High-Performance Computing
13.5 Graphics Rendering
13.6 Media Processing
13.7 Virtualization and VDI
14 Global Data Center GPU Market, By End User
14.1 Cloud Service Providers
14.2 Enterprises
14.3 Government and Research Institutions
15 Global Data Center GPU Market, By Geography
15.1 North America
15.1.1 United States
15.1.2 Canada
15.1.3 Mexico
15.2 Europe
15.2.1 United Kingdom
15.2.2 Germany
15.2.3 France
15.2.4 Italy
15.2.5 Spain
15.2.6 Netherlands
15.2.7 Belgium
15.2.8 Sweden
15.2.9 Switzerland
15.2.10 Poland
15.2.11 Rest of Europe
15.3 Asia Pacific
15.3.1 China
15.3.2 Japan
15.3.3 India
15.3.4 South Korea
15.3.5 Australia
15.3.6 Indonesia
15.3.7 Thailand
15.3.8 Malaysia
15.3.9 Singapore
15.3.10 Vietnam
15.3.11 Rest of Asia Pacific
15.4 South America
15.4.1 Brazil
15.4.2 Argentina
15.4.3 Colombia
15.4.4 Chile
15.4.5 Peru
15.4.6 Rest of South America
15.5 Rest of the World (RoW)
15.5.1 Middle East
15.5.1.1 Saudi Arabia
15.5.1.2 United Arab Emirates
15.5.1.3 Qatar
15.5.1.4 Israel
15.5.1.5 Rest of Middle East
15.5.2 Africa
15.5.2.1 South Africa
15.5.2.2 Egypt
15.5.2.3 Morocco
15.5.2.4 Rest of Africa
16 Strategic Market Intelligence
16.1 Industry Value Network and Supply Chain Assessment
16.2 White-Space and Opportunity Mapping
16.3 Product Evolution and Market Life Cycle Analysis
16.4 Channel, Distributor, and Go-to-Market Assessment
17 Industry Developments and Strategic Initiatives
17.1 Mergers and Acquisitions
17.2 Partnerships, Alliances, and Joint Ventures
17.3 New Product Launches and Certifications
17.4 Capacity Expansion and Investments
17.5 Other Strategic Initiatives
18 Company Profiles
18.1 Intel Corporation
18.2 Advanced Micro Devices, Inc.
18.3 NVIDIA Corporation
18.4 Huawei Technologies Co., Ltd.
18.5 Biren Technology
18.6 Moore Threads Technology Co., Ltd.
18.7 Iluvatar CoreX
18.8 Cambricon Technologies Corporation Limited
18.9 Jingjia Microelectronics Co., Ltd.
18.10 Enflame Technology Co., Ltd.
18.11 MetaX Integrated Circuits Co., Ltd.
18.12 Alibaba Group Holding Limited
18.13 Baidu, Inc.
18.14 Fujitsu Limited
18.15 IBM Corporation
18.16 Lenovo Group Limited
18.17 Inspur Group
18.18 Foxconn Industrial Internet Co., Ltd.
List of Tables
1 Global Data Center GPU Market Outlook, By Region (2023-2034) ($MN)
2 Global Data Center GPU Market Outlook, By GPU Type (2023-2034) ($MN)
3 Global Data Center GPU Market Outlook, By Discrete GPUs (2023-2034) ($MN)
4 Global Data Center GPU Market Outlook, By Integrated GPUs (2023-2034) ($MN)
5 Global Data Center GPU Market Outlook, By Hybrid GPUs (2023-2034) ($MN)
6 Global Data Center GPU Market Outlook, By GPU Architecture (2023-2034) ($MN)
7 Global Data Center GPU Market Outlook, By CUDA-Based Architectures (2023-2034) ($MN)
8 Global Data Center GPU Market Outlook, By CDNA-Based Architectures (2023-2034) ($MN)
9 Global Data Center GPU Market Outlook, By Xe-Based Architectures (2023-2034) ($MN)
10 Global Data Center GPU Market Outlook, By Other GPU Architectures (2023-2034) ($MN)
11 Global Data Center GPU Market Outlook, By Form Factor (2023-2034) ($MN)
12 Global Data Center GPU Market Outlook, By Single-Slot GPUs (2023-2034) ($MN)
13 Global Data Center GPU Market Outlook, By Dual-Slot GPUs (2023-2034) ($MN)
14 Global Data Center GPU Market Outlook, By Multi-Slot GPUs (2023-2034) ($MN)
15 Global Data Center GPU Market Outlook, By SXM Modules (2023-2034) ($MN)
16 Global Data Center GPU Market Outlook, By Rack-Scale GPU Systems (2023-2034) ($MN)
17 Global Data Center GPU Market Outlook, By Cooling Type (2023-2034) ($MN)
18 Global Data Center GPU Market Outlook, By Air-Cooled (2023-2034) ($MN)
19 Global Data Center GPU Market Outlook, By Liquid-Cooled (2023-2034) ($MN)
20 Global Data Center GPU Market Outlook, By Immersion-Cooled (2023-2034) ($MN)
21 Global Data Center GPU Market Outlook, By Function (2023-2034) ($MN)
22 Global Data Center GPU Market Outlook, By AI Training (2023-2034) ($MN)
23 Global Data Center GPU Market Outlook, By AI Inference (2023-2034) ($MN)
24 Global Data Center GPU Market Outlook, By High-Performance Computing (2023-2034) ($MN)
25 Global Data Center GPU Market Outlook, By Graphics and Visualization (2023-2034) ($MN)
26 Global Data Center GPU Market Outlook, By Media and Video Processing (2023-2034) ($MN)
27 Global Data Center GPU Market Outlook, By Deployment (2023-2034) ($MN)
28 Global Data Center GPU Market Outlook, By Cloud (2023-2034) ($MN)
29 Global Data Center GPU Market Outlook, By On-Premises (2023-2034) ($MN)
30 Global Data Center GPU Market Outlook, By Data Center Type (2023-2034) ($MN)
31 Global Data Center GPU Market Outlook, By Hyperscale Data Centers (2023-2034) ($MN)
32 Global Data Center GPU Market Outlook, By Enterprise Data Centers (2023-2034) ($MN)
33 Global Data Center GPU Market Outlook, By Colocation Data Centers (2023-2034) ($MN)
34 Global Data Center GPU Market Outlook, By Edge Data Centers (2023-2034) ($MN)
35 Global Data Center GPU Market Outlook, By Memory Technology (2023-2034) ($MN)
36 Global Data Center GPU Market Outlook, By HBM (2023-2034) ($MN)
37 Global Data Center GPU Market Outlook, By GDDR (2023-2034) ($MN)
38 Global Data Center GPU Market Outlook, By Other Memory Technologies (2023-2034) ($MN)
39 Global Data Center GPU Market Outlook, By Application (2023-2034) ($MN)
40 Global Data Center GPU Market Outlook, By Generative AI (2023-2034) ($MN)
41 Global Data Center GPU Market Outlook, By Machine Learning (2023-2034) ($MN)
42 Global Data Center GPU Market Outlook, By Data Analytics (2023-2034) ($MN)
43 Global Data Center GPU Market Outlook, By High-Performance Computing (2023-2034) ($MN)
44 Global Data Center GPU Market Outlook, By Graphics Rendering (2023-2034) ($MN)
45 Global Data Center GPU Market Outlook, By Media Processing (2023-2034) ($MN)
46 Global Data Center GPU Market Outlook, By Virtualization and VDI (2023-2034) ($MN)
47 Global Data Center GPU Market Outlook, By End User (2023-2034) ($MN)
48 Global Data Center GPU Market Outlook, By Cloud Service Providers (2023-2034) ($MN)
49 Global Data Center GPU Market Outlook, By Enterprises (2023-2034) ($MN)
50 Global Data Center GPU Market Outlook, By Government and Research Institutions (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
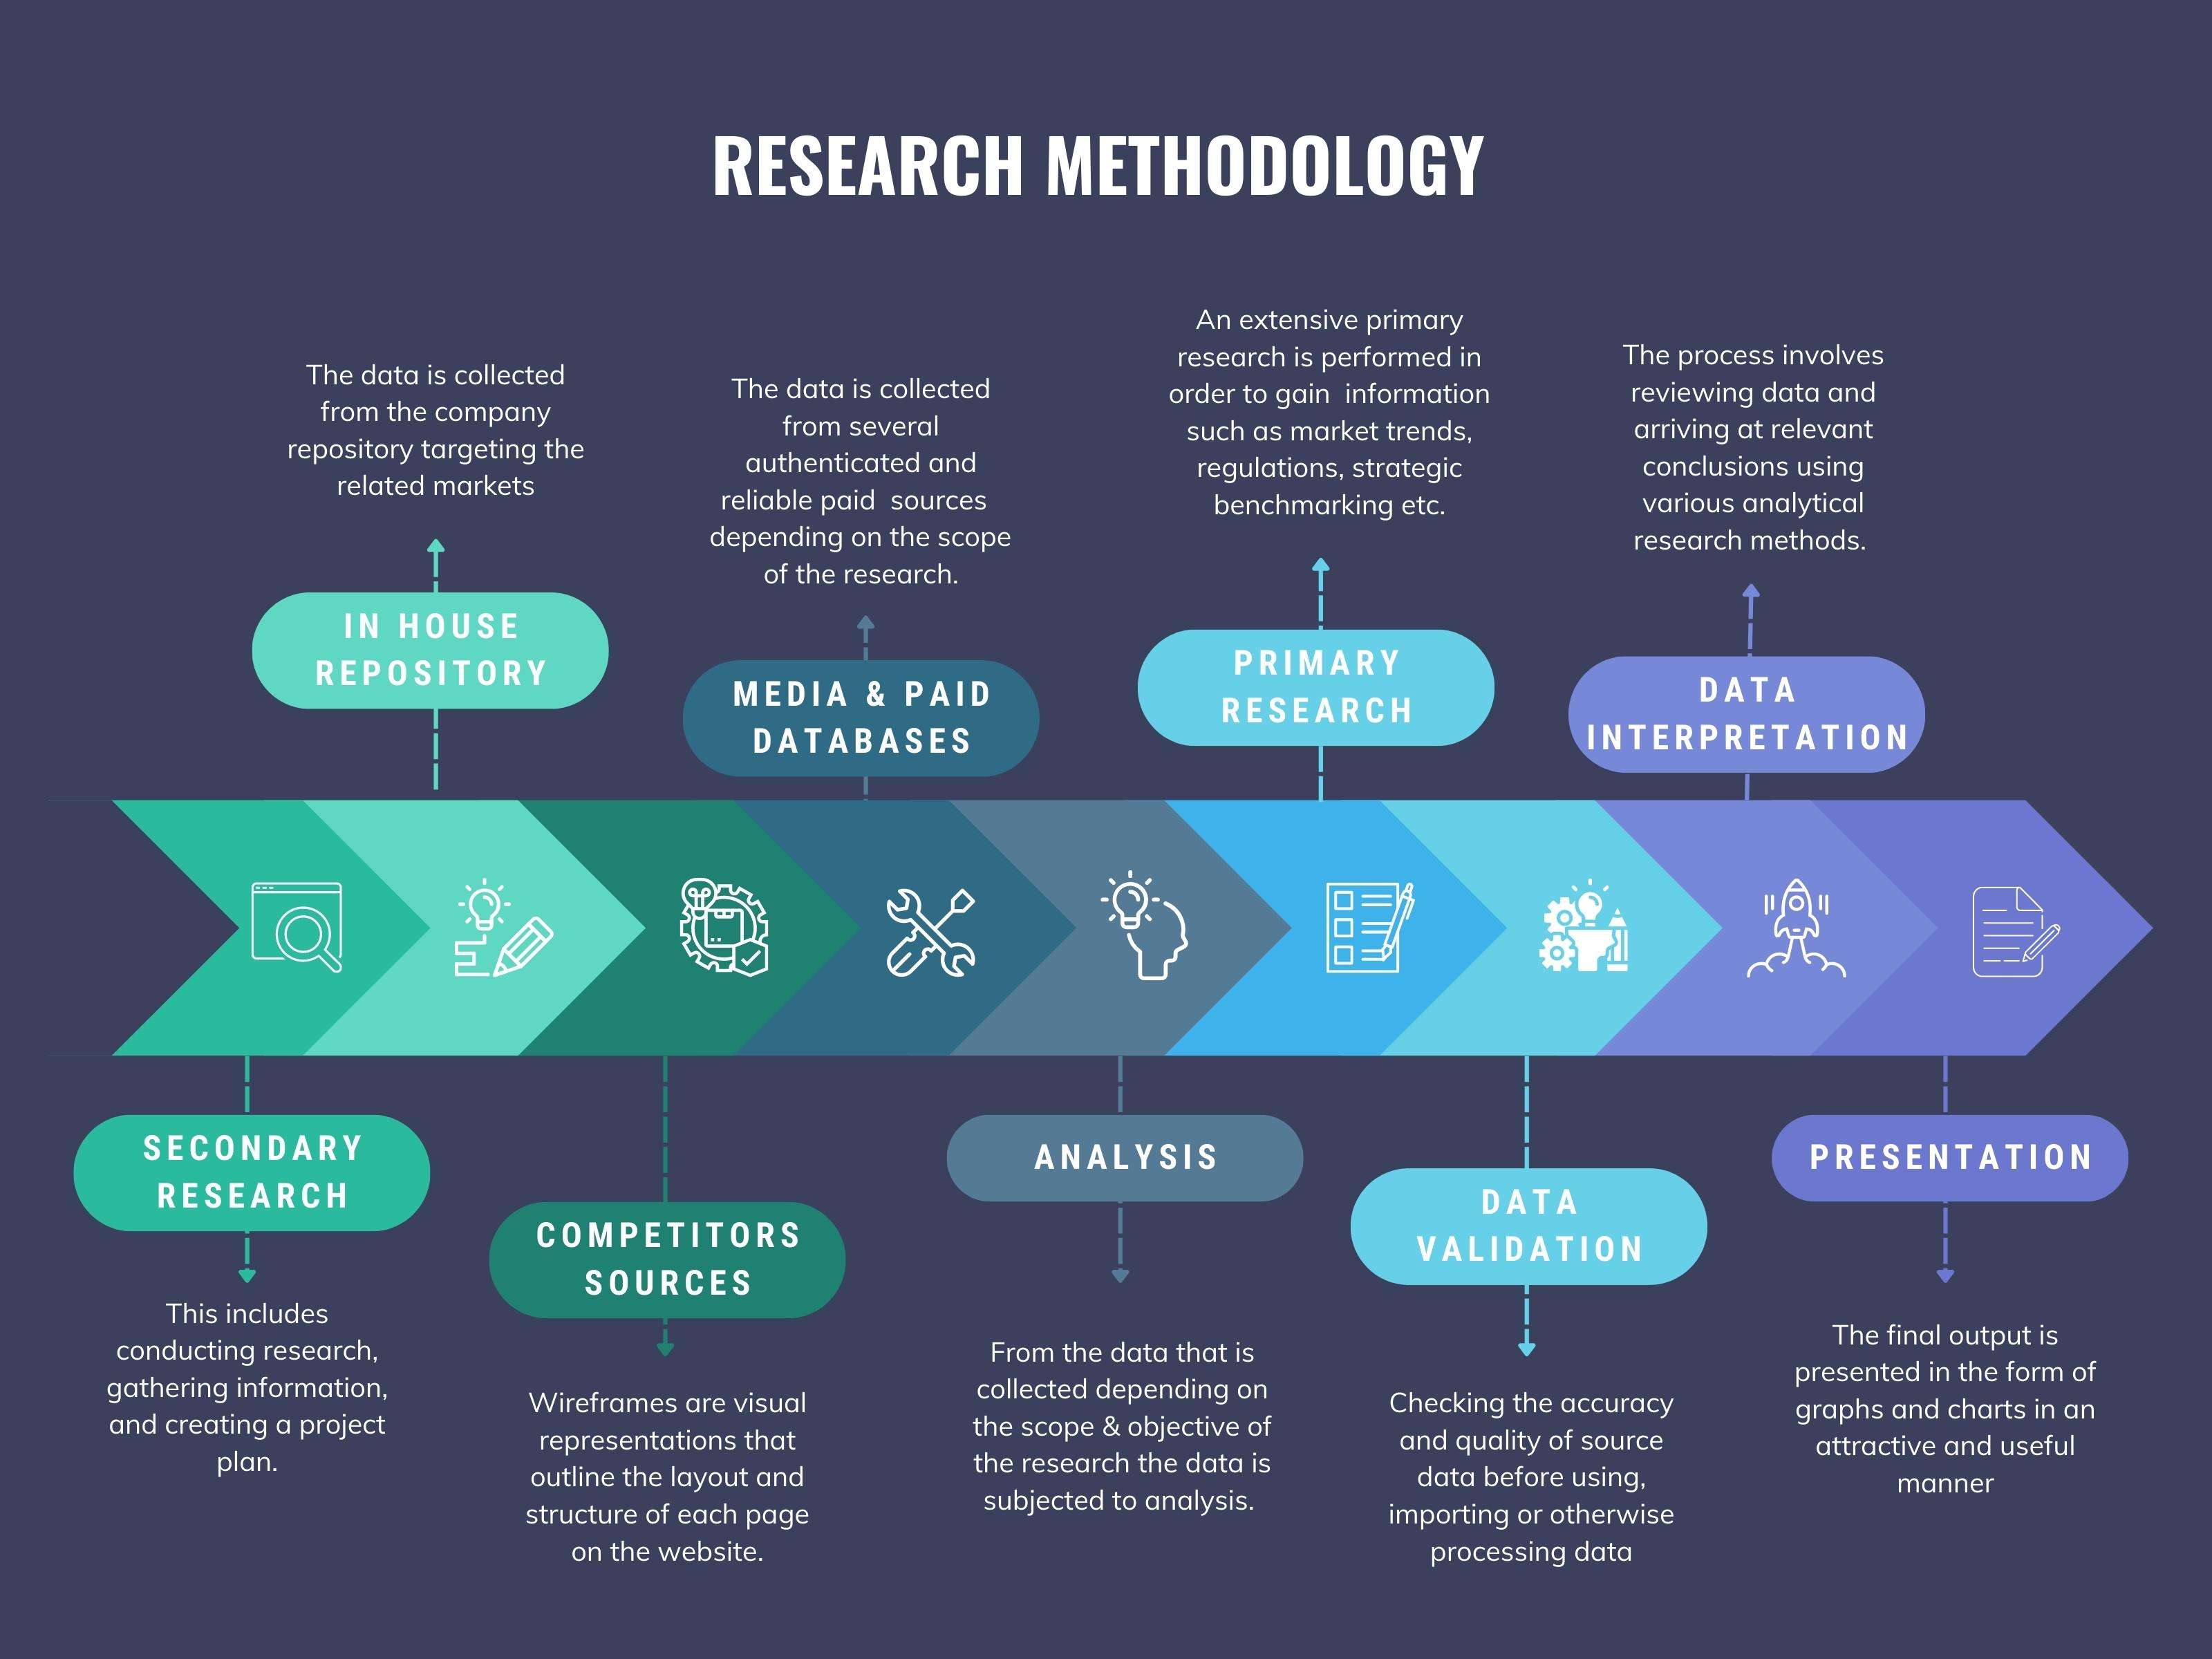
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.