Fluoropolymer Market
Fluoropolymer Market Forecasts to 2034 – Global Analysis By Product Type (Polytetrafluoroethylene (PTFE), Fluorinated Ethylene Propylene (FEP), Perfluoroalkoxy Alkane (PFA), Ethylene Tetrafluoroethylene (ETFE), Polyvinylidene Fluoride (PVDF), Ethylene Chlorotrifluoroethylene (ECTFE), Polychlorotrifluoroethylene (PCTFE), and Product Types), Form, Application, and By Geography
According to Stratistics MRC, the Global Fluoropolymer Market is accounted for $12.5 billion in 2026 and is expected to reach $24.0 billion by 2034 growing at a CAGR of 8.5% during the forecast period. Fluoropolymers are high-performance polymers containing fluorine atoms, offering exceptional chemical resistance, thermal stability, electrical insulation, and low friction properties. The market encompasses polytetrafluoroethylene (PTFE), fluorinated ethylene propylene (FEP), perfluoroalkoxy alkane (PFA), ethylene tetrafluoroethylene (ETFE), polyvinylidene fluoride (PVDF), ethylene chlorotrifluoroethylene (ECTFE), polychlorotrifluoroethylene (PCTFE), and other product types available in granules and pellets, powders, dispersions, films and sheets, tubes and pipes, and other forms. These materials serve automotive, electrical and electronics, chemical processing, aerospace and defense, medical and healthcare, semiconductor manufacturing, industrial equipment, and energy applications.
Market Dynamics:
Driver:
Growing demand for chemical-resistant and high-temperature materials
The increasing need for materials that can withstand aggressive chemicals and extreme temperatures in industrial applications is a primary driver for the fluoropolymer market. Chemical processing, semiconductor manufacturing, and automotive applications require materials with exceptional chemical resistance. Fluoropolymers offer superior performance in harsh environments where conventional materials fail. The expansion of semiconductor manufacturing is driving demand for high-purity fluoropolymers. As industrial requirements intensify, fluoropolymer demand expands across all major applications.
Restraint:
Environmental and regulatory concerns regarding PFAS
The growing environmental and regulatory concerns regarding per- and polyfluoroalkyl substances (PFAS) represent a major restraint for the fluoropolymer market. Regulatory scrutiny of PFAS chemicals is increasing globally. Potential restrictions on certain fluoropolymers may affect market access. Remediation costs and liability concerns create uncertainty. These environmental and regulatory challenges may constrain market growth, particularly for applications where alternative materials are available.
Opportunity:
Expansion of semiconductor and clean energy applications
The growing demand for semiconductors and clean energy applications presents significant opportunities for the fluoropolymer market. Semiconductor manufacturing requires high-purity fluoropolymers for chemical handling and contamination control. Clean energy applications including fuel cells and solar panels use fluoropolymers for durability and performance. The expansion of hydrogen infrastructure is creating demand for fluoropolymer components. As technology advances, fluoropolymers capture growing market share in emerging applications.
Threat:
Competition from alternative high-performance materials
Intense competition from alternative high-performance materials including PEEK, polyimides, and other specialty polymers poses significant threats to fluoropolymer market growth. Alternative materials offer competitive performance in specific applications. Regulatory pressures may drive substitution in some markets. Cost pressures may favor alternative materials. This competition may limit market share, particularly in applications where alternative materials provide adequate performance.
Covid-19 Impact:
The COVID-19 pandemic had a mixed impact on the fluoropolymer market. Initial disruptions included supply chain interruptions and reduced industrial production. However, demand for medical devices and semiconductor applications increased. Chemical processing and industrial applications remained resilient. Post-pandemic, continued industrial recovery and semiconductor investment have supported market growth across all major applications.
The Polytetrafluoroethylene (PTFE) segment is expected to be the largest during the forecast period
The Polytetrafluoroethylene (PTFE) segment is expected to account for the largest market share during the forecast period, driven by its exceptional chemical resistance, thermal stability, and low friction properties, making it the most widely used fluoropolymer. PTFE finds applications in chemical processing, automotive, electrical, and industrial equipment. The segment benefits from established manufacturing infrastructure and broad application scope. Growing industrial and automotive production supports demand. As the most widely used fluoropolymer, PTFE maintains the largest product type segment share.
The Semiconductor Manufacturing segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Semiconductor Manufacturing segment is predicted to witness the highest growth rate, fueled by the rapid expansion of global semiconductor production and the increasing demand for high-purity fluoropolymers in semiconductor fabrication. Fluoropolymers are essential for chemical handling, contamination control, and high-purity fluid handling in semiconductor manufacturing. The segment benefits from semiconductor capacity expansion and technology advancement. As semiconductor production grows, this application delivers the fastest segment growth.
Region with largest share:
During the forecast period, the Asia-Pacific region is expected to hold the largest market share, supported by concentrated manufacturing, expanding semiconductor production, and growing industrial activity across China, Japan, South Korea, and India. China leads global fluoropolymer production and consumption, driving substantial market volume. The region's large and growing semiconductor industry creates significant demand. Growing chemical processing and industrial applications support demand. With concentrated manufacturing and growing end-use markets, Asia Pacific maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by continued semiconductor manufacturing expansion, rising industrial production, and growing investment in advanced materials across the region. The region's large and growing semiconductor industry creates substantial demand for high-purity fluoropolymers. Government initiatives supporting semiconductor self-sufficiency are accelerating. Chemical processing and industrial expansion support demand. As industrial activity and technology adoption expand, Asia Pacific delivers the fastest fluoropolymer market growth globally.
Key players in the market
Some of the key players in Fluoropolymer Market include The Chemours Company, Daikin Industries, Ltd., AGC Inc., Arkema S.A., Solvay S.A., 3M Company, Honeywell International Inc., Dongyue Group Limited, Gujarat Fluorochemicals Limited, Kureha Corporation, Saint-Gobain Performance Plastics, Zeus Industrial Products, Inc., Fluorocarbon Company Ltd., HaloPolymer, and Mitsui Chemicals, Inc.
Key Developments:
In May 2026, Gujarat Fluorochemicals Limited committed ₹2.5 billion in capital expenditures to expand its specialty fluoropolymers portfolio to meet surging demand across electric vehicle batteries, energy storage systems, and semiconductor processing.
In March 2026, Honeywell expanded the application footprint of its Aclar® fluoropolymer films, focusing on moisture-barrier packaging formulations for advanced biologics and pharmaceutical injectables.
In February 2026, Daikin Industries advanced its regional compound operations via expanded integration of its European compounding facilities, scaling up tailored fluoro-compound solutions for medical devices and chemical handling.
In August 2025, The Chemours Company entered into multi-year strategic agreements with India-based SRF Limited to scale up the global production and supply of fluoropolymers and fluoroelastomers by 2026, bolstering manufacturing flexibility for the semiconductor and automotive sectors without upfront capital expenditure.
Product Types Covered:
• Polytetrafluoroethylene (PTFE)
• Fluorinated Ethylene Propylene (FEP)
• Perfluoroalkoxy Alkane (PFA)
• Ethylene Tetrafluoroethylene (ETFE)
• Polyvinylidene Fluoride (PVDF)
• Ethylene Chlorotrifluoroethylene (ECTFE)
• Polychlorotrifluoroethylene (PCTFE)
• Other Product Types
Forms Covered:
• Granules and Pellets
• Powders
• Dispersions
• Films and Sheets
• Tubes and Pipes
• Other Forms
Applications Covered:
• Automotive
• Electrical and Electronics
• Chemical Processing
• Aerospace and Defense
• Medical and Healthcare
• Semiconductor Manufacturing
• Industrial Equipment
• Energy
• Other Applications
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Fluoropolymer Market, By Product Type
5.1 Polytetrafluoroethylene (PTFE)
5.2 Fluorinated Ethylene Propylene (FEP)
5.3 Perfluoroalkoxy Alkane (PFA)
5.4 Ethylene Tetrafluoroethylene (ETFE)
5.5 Polyvinylidene Fluoride (PVDF)
5.6 Ethylene Chlorotrifluoroethylene (ECTFE)
5.7 Polychlorotrifluoroethylene (PCTFE)
5.8 Other Product Types
6 Global Fluoropolymer Market, By Form
6.1 Granules and Pellets
6.2 Powders
6.3 Dispersions
6.4 Films and Sheets
6.5 Tubes and Pipes
6.6 Other Forms
7 Global Fluoropolymer Market, By Application
7.1 Automotive
7.2 Electrical and Electronics
7.3 Chemical Processing
7.4 Aerospace and Defense
7.5 Medical and Healthcare
7.6 Semiconductor Manufacturing
7.7 Industrial Equipment
7.8 Energy
7.9 Other Applications
8 Global Fluoropolymer Market, By Geography
8.1 North America
8.1.1 United States
8.1.2 Canada
8.1.3 Mexico
8.2 Europe
8.2.1 United Kingdom
8.2.2 Germany
8.2.3 France
8.2.4 Italy
8.2.5 Spain
8.2.6 Netherlands
8.2.7 Belgium
8.2.8 Sweden
8.2.9 Switzerland
8.2.10 Poland
8.2.11 Rest of Europe
8.3 Asia Pacific
8.3.1 China
8.3.2 Japan
8.3.3 India
8.3.4 South Korea
8.3.5 Australia
8.3.6 Indonesia
8.3.7 Thailand
8.3.8 Malaysia
8.3.9 Singapore
8.3.10 Vietnam
8.3.11 Rest of Asia Pacific
8.4 South America
8.4.1 Brazil
8.4.2 Argentina
8.4.3 Colombia
8.4.4 Chile
8.4.5 Peru
8.4.6 Rest of South America
8.5 Rest of the World (RoW)
8.5.1 Middle East
8.5.1.1 Saudi Arabia
8.5.1.2 United Arab Emirates
8.5.1.3 Qatar
8.5.1.4 Israel
8.5.1.5 Rest of Middle East
8.5.2 Africa
8.5.2.1 South Africa
8.5.2.2 Egypt
8.5.2.3 Morocco
8.5.2.4 Rest of Africa
9 Strategic Market Intelligence
9.1 Industry Value Network and Supply Chain Assessment
9.2 White-Space and Opportunity Mapping
9.3 Product Evolution and Market Life Cycle Analysis
9.4 Channel, Distributor, and Go-to-Market Assessment
10 Industry Developments and Strategic Initiatives
10.1 Mergers and Acquisitions
10.2 Partnerships, Alliances, and Joint Ventures
10.3 New Product Launches and Certifications
10.4 Capacity Expansion and Investments
10.5 Other Strategic Initiatives
11 Company Profiles
11.1 The Chemours Company
11.2 Daikin Industries, Ltd.
11.3 AGC Inc.
11.4 Arkema S.A.
11.5 Solvay S.A.
11.6 3M Company
11.7 Honeywell International Inc.
11.8 Dongyue Group Limited
11.9 Gujarat Fluorochemicals Limited
11.10 Kureha Corporation
11.11 Saint-Gobain
11.12 Zeus Industrial Products, Inc.
11.13 Fluorocarbon Company Ltd.
11.14 HaloPolymer
11.15 Mitsui Chemicals, Inc.
List of Tables
1 Global Fluoropolymer Market Outlook, By Region (2023–2034) ($MN)
2 Global Fluoropolymer Market Outlook, By Product Type (2023–2034) ($MN)
3 Global Fluoropolymer Market Outlook, By Polytetrafluoroethylene (PTFE) (2023–2034) ($MN)
4 Global Fluoropolymer Market Outlook, By Fluorinated Ethylene Propylene (FEP) (2023–2034) ($MN)
5 Global Fluoropolymer Market Outlook, By Perfluoroalkoxy Alkane (PFA) (2023–2034) ($MN)
6 Global Fluoropolymer Market Outlook, By Ethylene Tetrafluoroethylene (ETFE) (2023–2034) ($MN)
7 Global Fluoropolymer Market Outlook, By Polyvinylidene Fluoride (PVDF) (2023–2034) ($MN)
8 Global Fluoropolymer Market Outlook, By Ethylene Chlorotrifluoroethylene (ECTFE) (2023–2034) ($MN)
9 Global Fluoropolymer Market Outlook, By Polychlorotrifluoroethylene (PCTFE) (2023–2034) ($MN)
10 Global Fluoropolymer Market Outlook, By Other Product Types (2023–2034) ($MN)
11 Global Fluoropolymer Market Outlook, By Form (2023–2034) ($MN)
12 Global Fluoropolymer Market Outlook, By Granules and Pellets (2023–2034) ($MN)
13 Global Fluoropolymer Market Outlook, By Powders (2023–2034) ($MN)
14 Global Fluoropolymer Market Outlook, By Dispersions (2023–2034) ($MN)
15 Global Fluoropolymer Market Outlook, By Films and Sheets (2023–2034) ($MN)
16 Global Fluoropolymer Market Outlook, By Tubes and Pipes (2023–2034) ($MN)
17 Global Fluoropolymer Market Outlook, By Other Forms (2023–2034) ($MN)
18 Global Fluoropolymer Market Outlook, By Application (2023–2034) ($MN)
19 Global Fluoropolymer Market Outlook, By Automotive (2023–2034) ($MN)
20 Global Fluoropolymer Market Outlook, By Electrical and Electronics (2023–2034) ($MN)
21 Global Fluoropolymer Market Outlook, By Chemical Processing (2023–2034) ($MN)
22 Global Fluoropolymer Market Outlook, By Aerospace and Defense (2023–2034) ($MN)
23 Global Fluoropolymer Market Outlook, By Medical and Healthcare (2023–2034) ($MN)
24 Global Fluoropolymer Market Outlook, By Semiconductor Manufacturing (2023–2034) ($MN)
25 Global Fluoropolymer Market Outlook, By Industrial Equipment (2023–2034) ($MN)
26 Global Fluoropolymer Market Outlook, By Energy (2023–2034) ($MN)
27 Global Fluoropolymer Market Outlook, By Other Applications (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
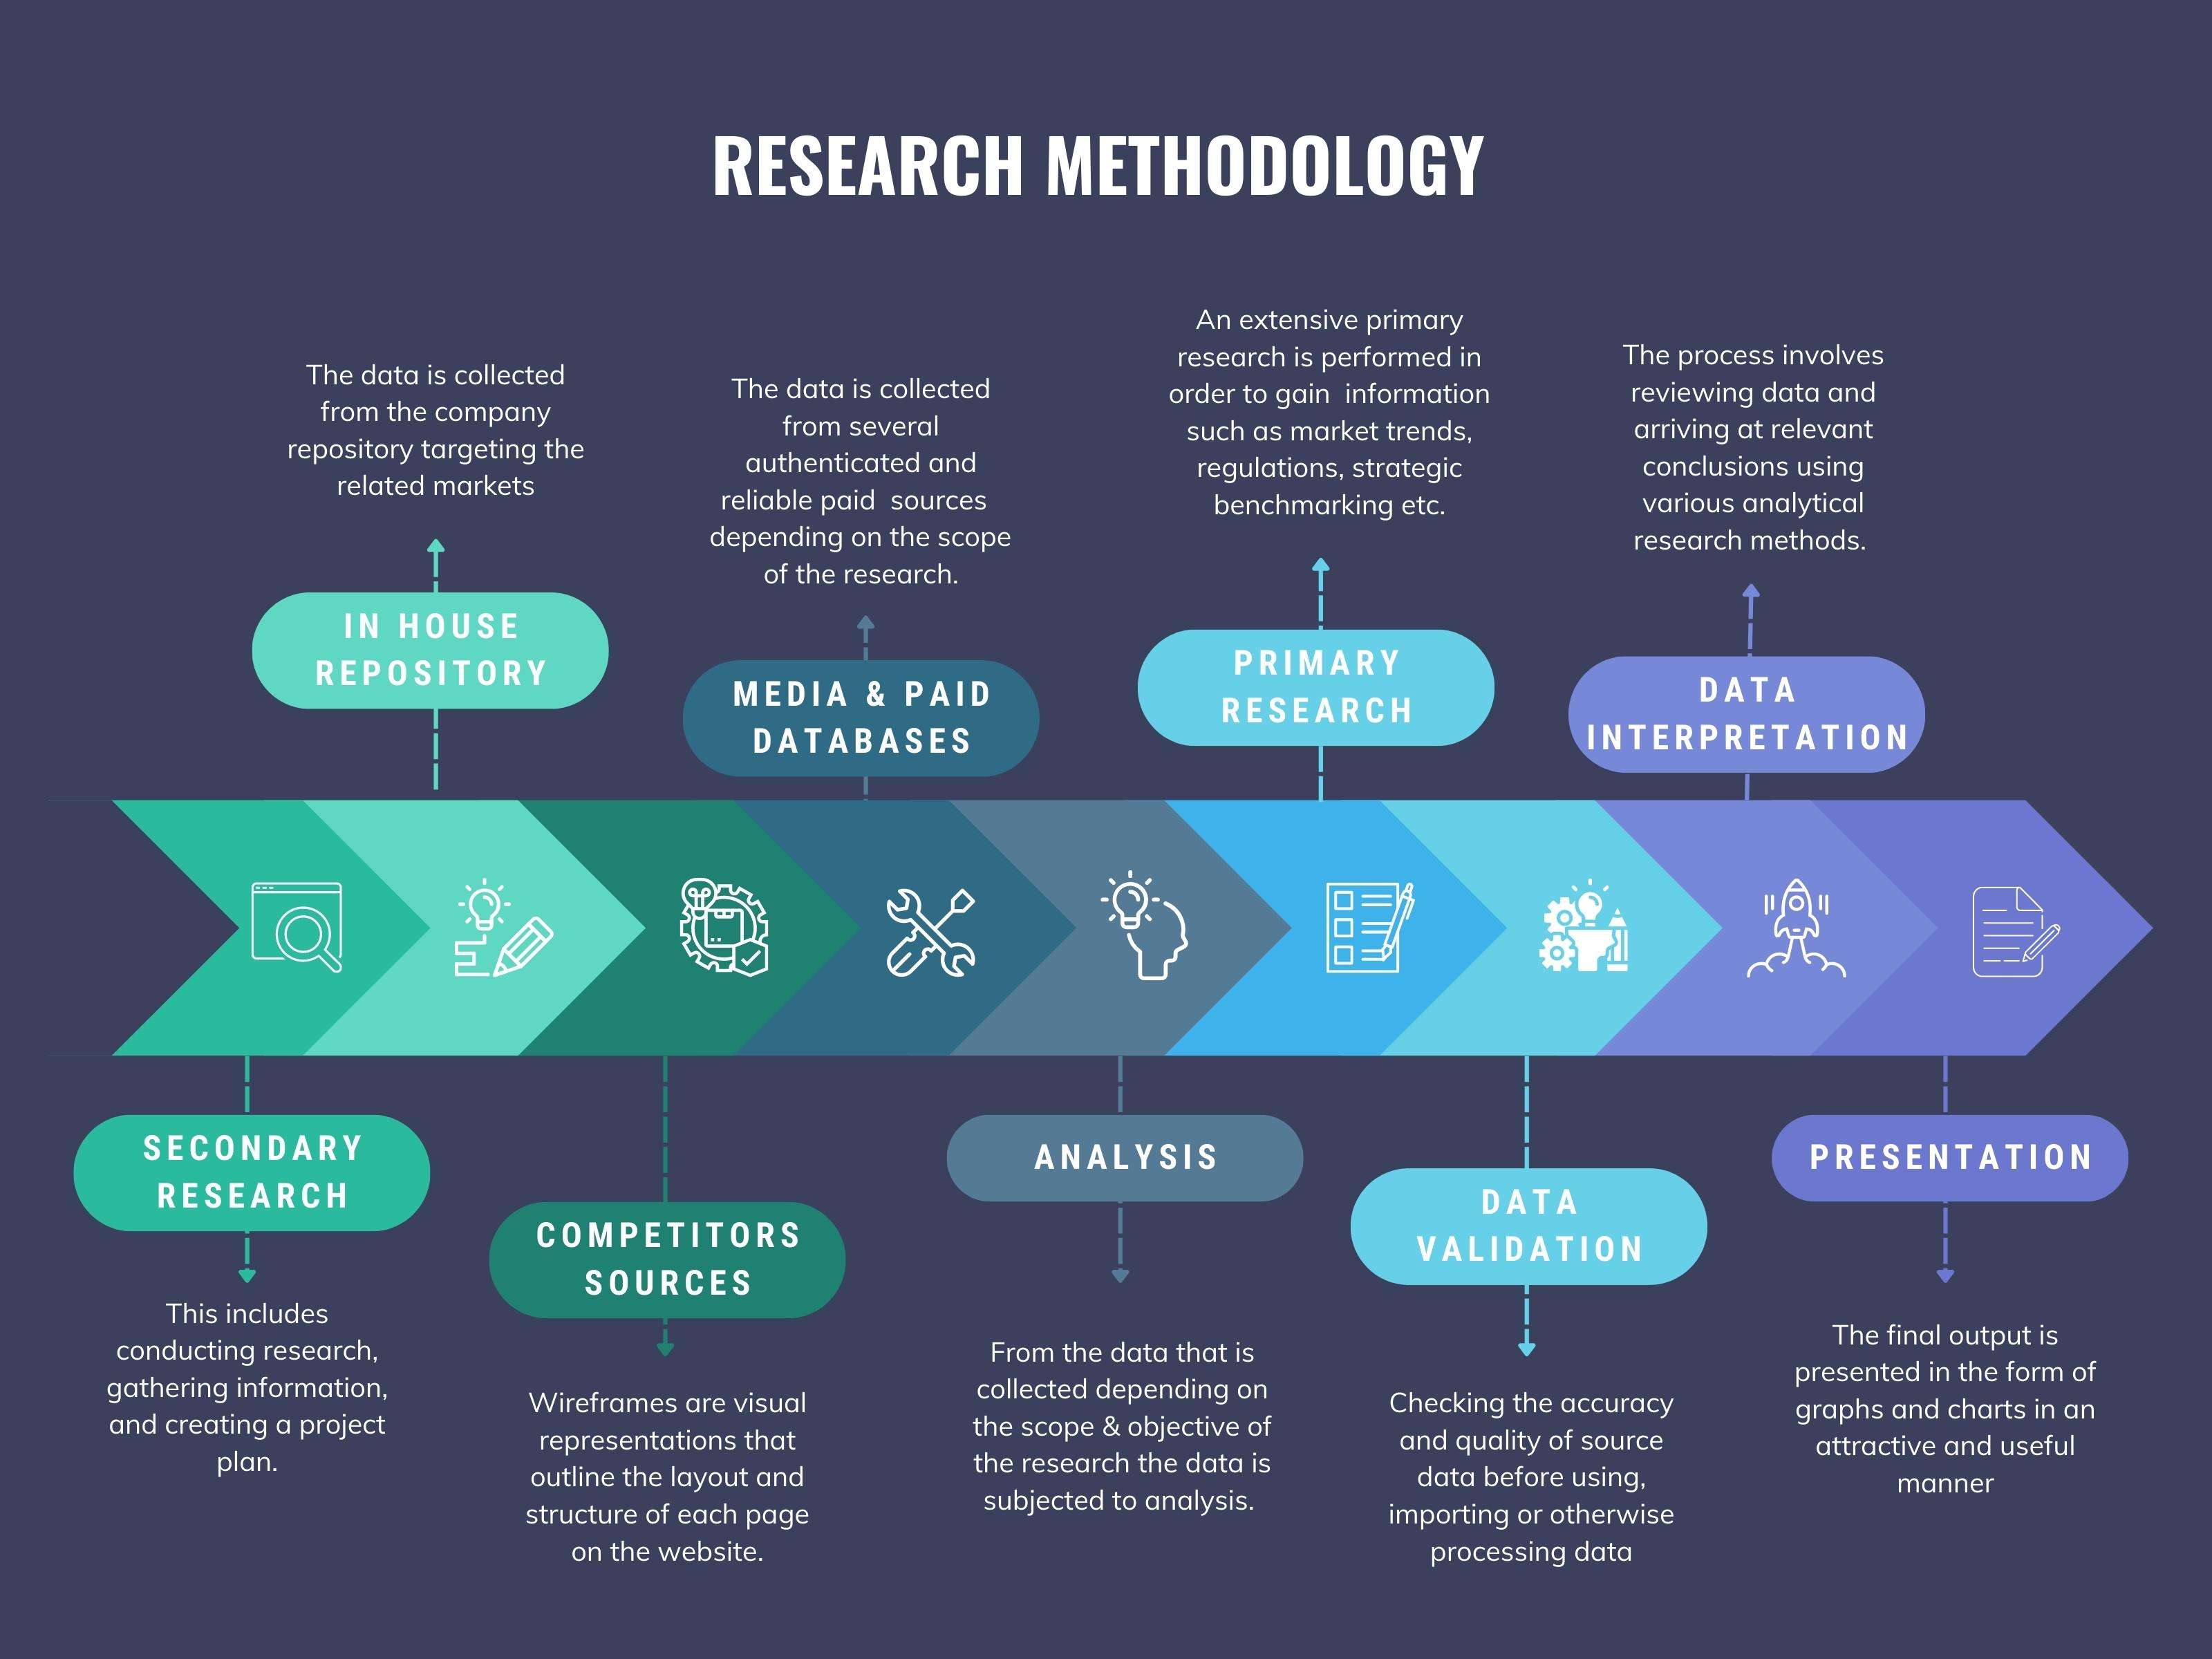
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.