Heart Failure Market
Heart Failure Market Forecasts to 2034 - Global Analysis By Heart Failure Type (Heart Failure with Reduced Ejection Fraction (HFrEF), Heart Failure with Preserved Ejection Fraction (HFpEF) and Heart Failure with Mildly Reduced Ejection Fraction (HFmrEF)), Disease Severity, Etiology, Drug Class, Route of Administration, Distribution Channel, End User and By Geography
Market Dynamics:
Driver:
Increasing prevalence of cardiovascular diseases and aging populations
The increasing prevalence of cardiovascular diseases and the growing geriatric population are major drivers of the heart failure market. Conditions such as coronary artery disease, hypertension, diabetes, and cardiomyopathy contribute significantly to heart failure development. Rising life expectancy and improved survival following cardiovascular events are increasing the number of individuals requiring long-term heart failure management. Greater awareness of early diagnosis, improved access to cardiac imaging, and expanding adoption of guideline-directed medical therapies are supporting treatment demand. Continued investment in cardiovascular healthcare infrastructure is further encouraging market growth.
Restraint:
High treatment costs and limited access to specialized cardiac care
High treatment costs and unequal access to specialized cardiac services are significant restraints on market expansion. Advanced medications, implantable cardiac devices, repeated hospitalizations, and long-term disease monitoring can create substantial financial burdens for patients and healthcare systems. Limited reimbursement coverage and inadequate specialist availability in developing regions may restrict access to effective treatment. Additionally, complex medication regimens, treatment-related adverse effects, and poor patient adherence can reduce therapeutic effectiveness. Differences in healthcare infrastructure and delayed diagnosis further complicate comprehensive heart failure management.
Opportunity:
Advancements in targeted therapies and remote cardiac monitoring technologies
Advancements in cardiovascular therapeutics and remote patient monitoring are creating significant opportunities for market participants. Increasing adoption of SGLT2 inhibitors, ARNIs, and other guideline-directed medications is improving treatment options across different heart failure categories. Wearable sensors, implantable monitoring devices, and digital health platforms enable more frequent assessment of patient status and may support earlier intervention. Pharmaceutical companies are also investigating novel mechanisms targeting cardiac function and disease progression. Expanding telecardiology services and personalized treatment strategies are further encouraging innovation and investment.
Threat:
Regulatory complexities and competitive pressure from generic medications
Stringent regulatory requirements, pricing pressures, and increasing competition from generic medications present significant market threats. Developers of new heart failure therapies and implantable devices must demonstrate clinical safety, effectiveness, and long-term outcomes through extensive evaluation. Patent expirations and generic competition may reduce revenues for established pharmaceutical products. Device-related complications, medication intolerance, and inconsistent reimbursement policies can also influence treatment adoption. Additionally, supply chain disruptions, healthcare budget constraints, and variations in clinical practice may create operational challenges for manufacturers and healthcare providers.
Covid-19 Impact:
The COVID-19 pandemic affected the heart failure market through disruptions in routine cardiovascular consultations, diagnostic procedures, and elective interventions. Patients with existing heart failure faced increased clinical risks from severe infection, while healthcare systems experienced pressure on hospital capacity and specialist services. Delayed medical evaluations and interruptions in disease monitoring complicated chronic heart failure management. However, telemedicine, remote cardiac monitoring, and home-based care gained importance during the pandemic. Subsequent recovery in cardiovascular services and continued adoption of digital healthcare solutions supported market stabilization and long-term development.
The heart failure with reduced ejection fraction (HFrEF) segment is expected to be the largest during the forecast period
The heart failure with reduced ejection fraction (HFrEF) segment is expected to account for the largest market share during the forecast period due to its substantial treatment requirements and established use of multiple evidence-based therapies. HFrEF management commonly involves ARNIs or other renin-angiotensin system inhibitors, beta blockers, mineralocorticoid receptor antagonists, and SGLT2 inhibitors. Patients with advanced disease may also require implantable cardiac devices and specialized interventions. Continued adoption of guideline-directed medical therapy, improved diagnostic capabilities, and increasing availability of advanced treatment options are supporting segment development.
The SGLT2 inhibitors segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the SGLT2 inhibitors segment is predicted to witness the highest growth rate due to expanding clinical use of these medications in heart failure management. Originally developed for type 2 diabetes, SGLT2 inhibitors have demonstrated cardiovascular benefits in appropriate patients with heart failure, including those with reduced or preserved ejection fraction. Their inclusion in major treatment guidelines is supporting broader physician adoption. Increasing awareness of cardiorenal benefits, growing treatment eligibility, and continued clinical research are encouraging demand. Pharmaceutical investment and expanding access to these therapies may further support segment growth.
Region with largest share:
During the forecast period, North America is expected to hold the largest market share, supported by advanced cardiovascular healthcare infrastructure, substantial healthcare expenditure, and widespread availability of innovative heart failure treatments. The United States represents a major market due to significant cardiovascular disease burden, established cardiac specialty centers, and strong pharmaceutical and medical device industries. Increasing adoption of guideline-directed therapies, implantable devices, and remote monitoring technologies is supporting market development. Continued clinical research activity and access to specialized cardiac care further strengthen regional performance.
Region with highest CAGR:
Over the forecast period, Asia Pacific is anticipated to exhibit the highest CAGR due to increasing cardiovascular disease prevalence, rapidly aging populations, and expanding healthcare infrastructure. China, India, Japan, South Korea, and Australia are important markets for heart failure diagnosis and treatment. Rising healthcare expenditure, improving access to cardiac specialists, and growing adoption of advanced pharmaceutical therapies are supporting demand. Government initiatives to strengthen cardiovascular healthcare services, increasing medical device availability, and expanding telemedicine capabilities are further encouraging regional market growth.
Key players in the market
Some of the key players in the Heart Failure Market include Novartis, AstraZeneca, Boehringer Ingelheim, Bayer, Merck & Co., Eli Lilly and Company, Cytokinetics, Amgen, Bristol-Myers Squibb, Abbott, Medtronic, Boston Scientific, Biotronik, Novo Nordisk, and Pfizer.
Key Developments:
In June 2026, the U.S. Food and Drug Administration approved a revised post-approval study protocol for Abbott's CardioMEMS HF System. The implantable pulmonary artery pressure monitoring system supports remote management of eligible heart failure patients by providing hemodynamic information to clinicians.
In November 2025, Bayer announced that Kerendia (finerenone) received approval in India for treating adults with heart failure with preserved or mildly reduced ejection fraction. The therapy is a non-steroidal, selective mineralocorticoid receptor antagonist supported by clinical evidence from the FINEARTS-HF study.
In July 2025, Bayer announced U.S. FDA approval of Kerendia (finerenone) for adults with heart failure and a left ventricular ejection fraction of at least 40%. The approval was based on the Phase III FINEARTS-HF study, which demonstrated reductions in cardiovascular death and total heart failure events.
Heart Failure Types Covered:
• Heart Failure with Reduced Ejection Fraction (HFrEF)
• Heart Failure with Preserved Ejection Fraction (HFpEF)
• Heart Failure with Mildly Reduced Ejection Fraction (HFmrEF)
Disease Severities Covered:
• NYHA Class I
• NYHA Class II
• NYHA Class III
• NYHA Class IV
Etiologies Covered:
• Ischemic Heart Failure
• Hypertensive Heart Failure
• Valvular Heart Failure
• Cardiomyopathy-Associated Heart Failure
• Congenital Heart Disease-Associated Heart Failure
• Other Etiologies
Drug Classes Covered:
• ACE Inhibitors
• Angiotensin II Receptor Blockers (ARBs)
• Angiotensin Receptor-Neprilysin Inhibitors (ARNIs)
• Beta Blockers
• Mineralocorticoid Receptor Antagonists (MRAs)
• SGLT2 Inhibitors
• Diuretics
• Vasodilators
• Inotropes
• Other Drug Classes
Routes of Administration Covered:
• Oral
• Injectable
Distribution Channels Covered:
• Hospital Pharmacies
• Retail Pharmacies
• Online Pharmacies
End Users Covered:
• Hospitals
• Cardiac Specialty Centers
• Ambulatory Surgical Centers
• Home Care Settings
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Heart Failure Market, By Heart Failure Type
5.1 Heart Failure with Reduced Ejection Fraction (HFrEF)
5.2 Heart Failure with Preserved Ejection Fraction (HFpEF)
5.3 Heart Failure with Mildly Reduced Ejection Fraction (HFmrEF)
6 Global Heart Failure Market, By Disease Severity
6.1 NYHA Class I
6.2 NYHA Class II
6.3 NYHA Class III
6.4 NYHA Class IV
7 Global Heart Failure Market, By Etiology
7.1 Ischemic Heart Failure
7.2 Hypertensive Heart Failure
7.3 Valvular Heart Failure
7.4 Cardiomyopathy-Associated Heart Failure
7.5 Congenital Heart Disease-Associated Heart Failure
7.6 Other Etiologies
8 Global Heart Failure Market, By Drug Class
8.1 ACE Inhibitors
8.2 Angiotensin II Receptor Blockers (ARBs)
8.3 Angiotensin Receptor-Neprilysin Inhibitors (ARNIs)
8.4 Beta Blockers
8.5 Mineralocorticoid Receptor Antagonists (MRAs)
8.6 SGLT2 Inhibitors
8.7 Diuretics
8.8 Vasodilators
8.9 Inotropes
8.10 Other Drug Classes
9 Global Heart Failure Market, By Route of Administration
9.1 Oral
9.2 Injectable
10 Global Heart Failure Market, By Distribution Channel
10.1 Hospital Pharmacies
10.2 Retail Pharmacies
10.3 Online Pharmacies
11 Global Heart Failure Market, By End User
11.1 Hospitals
11.2 Cardiac Specialty Centers
11.3 Ambulatory Surgical Centers
11.4 Home Care Settings
12 Global Heart Failure Market, By Geography
12.1 North America
12.1.1 United States
12.1.2 Canada
12.1.3 Mexico
12.2 Europe
12.2.1 United Kingdom
12.2.2 Germany
12.2.3 France
12.2.4 Italy
12.2.5 Spain
12.2.6 Netherlands
12.2.7 Belgium
12.2.8 Sweden
12.2.9 Switzerland
12.2.10 Poland
12.2.11 Rest of Europe
12.3 Asia Pacific
12.3.1 China
12.3.2 Japan
12.3.3 India
12.3.4 South Korea
12.3.5 Australia
12.3.6 Indonesia
12.3.7 Thailand
12.3.8 Malaysia
12.3.9 Singapore
12.3.10 Vietnam
12.3.11 Rest of Asia Pacific
12.4 South America
12.4.1 Brazil
12.4.2 Argentina
12.4.3 Colombia
12.4.4 Chile
12.4.5 Peru
12.4.6 Rest of South America
12.5 Rest of the World (RoW)
12.5.1 Middle East
12.5.1.1 Saudi Arabia
12.5.1.2 United Arab Emirates
12.5.1.3 Qatar
12.5.1.4 Israel
12.5.1.5 Rest of Middle East
12.5.2 Africa
12.5.2.1 South Africa
12.5.2.2 Egypt
12.5.2.3 Morocco
12.5.2.4 Rest of Africa
13 Strategic Market Intelligence
13.1 Industry Value Network and Supply Chain Assessment
13.2 White-Space and Opportunity Mapping
13.3 Product Evolution and Market Life Cycle Analysis
13.4 Channel, Distributor, and Go-to-Market Assessment
14 Industry Developments and Strategic Initiatives
14.1 Mergers and Acquisitions
14.2 Partnerships, Alliances, and Joint Ventures
14.3 New Product Launches and Certifications
14.4 Capacity Expansion and Investments
14.5 Other Strategic Initiatives
15 Company Profiles
15.1 Novartis
15.2 AstraZeneca
15.3 Boehringer Ingelheim
15.4 Bayer
15.5 Merck & Co.
15.6 Eli Lilly and Company
15.7 Cytokinetics
15.8 Amgen
15.9 Bristol-Myers Squibb
15.10 Abbott
15.11 Medtronic
15.12 Boston Scientific
15.13 Biotronik
15.14 Novo Nordisk
15.15 Pfizer
List of Tables
1 Global Heart Failure Market Outlook, By Region (2023-2034) ($MN)
2 Global Heart Failure Market Outlook, By Heart Failure Type (2023-2034) ($MN)
3 Global Heart Failure Market Outlook, By Heart Failure with Reduced Ejection Fraction (HFrEF) (2023-2034) ($MN)
4 Global Heart Failure Market Outlook, By Heart Failure with Preserved Ejection Fraction (HFpEF) (2023-2034) ($MN)
5 Global Heart Failure Market Outlook, By Heart Failure with Mildly Reduced Ejection Fraction (HFmrEF) (2023-2034) ($MN)
6 Global Heart Failure Market Outlook, By Disease Severity (2023-2034) ($MN)
7 Global Heart Failure Market Outlook, By NYHA Class I (2023-2034) ($MN)
8 Global Heart Failure Market Outlook, By NYHA Class II (2023-2034) ($MN)
9 Global Heart Failure Market Outlook, By NYHA Class III (2023-2034) ($MN)
10 Global Heart Failure Market Outlook, By NYHA Class IV (2023-2034) ($MN)
11 Global Heart Failure Market Outlook, By Etiology (2023-2034) ($MN)
12 Global Heart Failure Market Outlook, By Ischemic Heart Failure (2023-2034) ($MN)
13 Global Heart Failure Market Outlook, By Hypertensive Heart Failure (2023-2034) ($MN)
14 Global Heart Failure Market Outlook, By Valvular Heart Failure (2023-2034) ($MN)
15 Global Heart Failure Market Outlook, By Cardiomyopathy-Associated Heart Failure (2023-2034) ($MN)
16 Global Heart Failure Market Outlook, By Congenital Heart Disease-Associated Heart Failure (2023-2034) ($MN)
17 Global Heart Failure Market Outlook, By Other Etiologies (2023-2034) ($MN)
18 Global Heart Failure Market Outlook, By Drug Class (2023-2034) ($MN)
19 Global Heart Failure Market Outlook, By ACE Inhibitors (2023-2034) ($MN)
20 Global Heart Failure Market Outlook, By Angiotensin II Receptor Blockers (ARBs) (2023-2034) ($MN)
21 Global Heart Failure Market Outlook, By Angiotensin Receptor-Neprilysin Inhibitors (ARNIs) (2023-2034) ($MN)
22 Global Heart Failure Market Outlook, By Beta Blockers (2023-2034) ($MN)
23 Global Heart Failure Market Outlook, By Mineralocorticoid Receptor Antagonists (MRAs) (2023-2034) ($MN)
24 Global Heart Failure Market Outlook, By SGLT2 Inhibitors (2023-2034) ($MN)
25 Global Heart Failure Market Outlook, By Diuretics (2023-2034) ($MN)
26 Global Heart Failure Market Outlook, By Vasodilators (2023-2034) ($MN)
27 Global Heart Failure Market Outlook, By Inotropes (2023-2034) ($MN)
28 Global Heart Failure Market Outlook, By Other Drug Classes (2023-2034) ($MN)
29 Global Heart Failure Market Outlook, By Route of Administration (2023-2034) ($MN)
30 Global Heart Failure Market Outlook, By Oral (2023-2034) ($MN)
31 Global Heart Failure Market Outlook, By Injectable (2023-2034) ($MN)
32 Global Heart Failure Market Outlook, By Distribution Channel (2023-2034) ($MN)
33 Global Heart Failure Market Outlook, By Hospital Pharmacies (2023-2034) ($MN)
34 Global Heart Failure Market Outlook, By Retail Pharmacies (2023-2034) ($MN)
35 Global Heart Failure Market Outlook, By Online Pharmacies (2023-2034) ($MN)
36 Global Heart Failure Market Outlook, By End User (2023-2034) ($MN)
37 Global Heart Failure Market Outlook, By Hospitals (2023-2034) ($MN)
38 Global Heart Failure Market Outlook, By Cardiac Specialty Centers (2023-2034) ($MN)
39 Global Heart Failure Market Outlook, By Ambulatory Surgical Centers (2023-2034) ($MN)
40 Global Heart Failure Market Outlook, By Home Care Settings (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
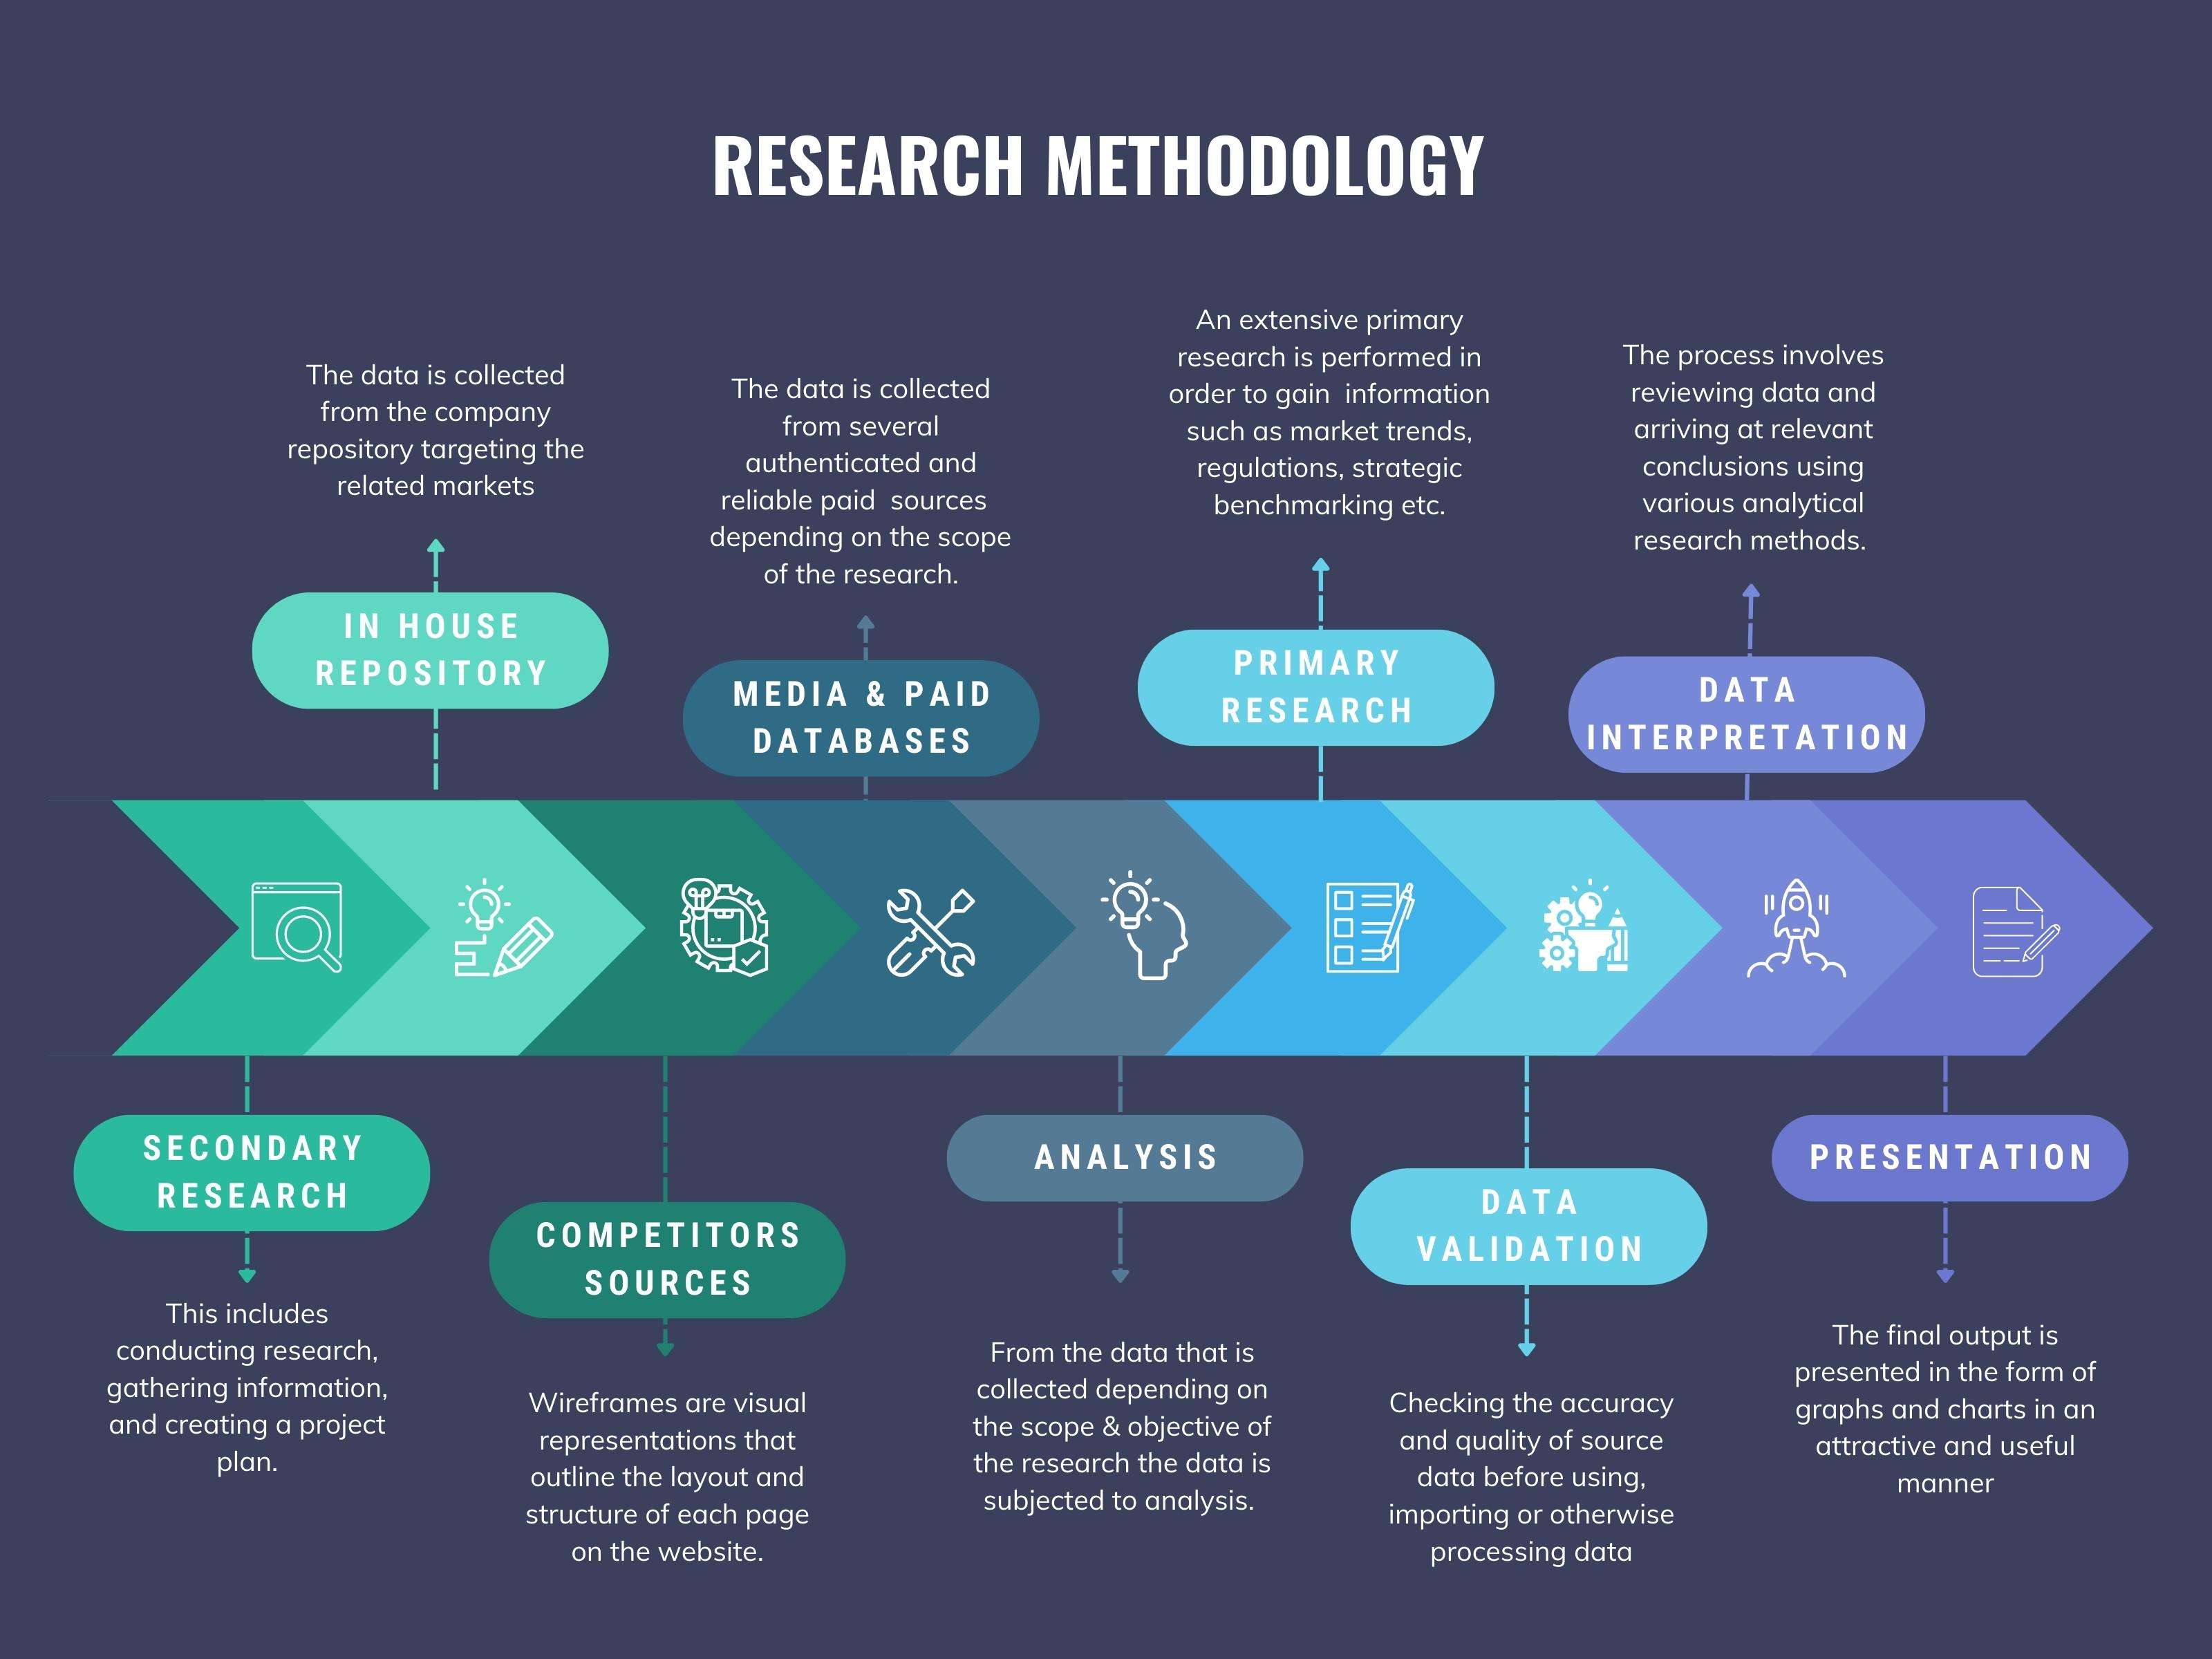
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.