Helicopter And Rotorcraft Civil And Para Public Market
Helicopter & Rotorcraft Civil & Para-Public Market Forecasts To 2034 - Global Analysis By Rotorcraft Type (Conventional Helicopters, Compound Helicopters, Tiltrotor Aircraft and Other Rotorcraft), Weight Class, Engine Configuration, Rotor Configuration, Propulsion Type, Sales Channel, Ownership Model, Application, End User and By Geography
According to Stratistics MRC, the Global Helicopter & Rotorcraft Civil & Para-Public Market is accounted for $8.7 billion in 2026 and is expected to reach $13.1 billion by 2034 growing at a CAGR of 5.2% during the forecast period. The Helicopter & Rotorcraft Civil & Para-Public Market covers the production, advancement, and utilization of rotorcraft serving civilian and government-related missions. Helicopters are increasingly used for emergency medical transportation, rescue operations, firefighting, policing, disaster management, passenger movement, offshore activities, utility services, and aerial inspection. Market expansion is supported by growing requirements for fast and flexible transportation, enhanced public safety infrastructure, replacement of older aircraft, and government spending on emergency and essential services. Innovations in avionics, propulsion technologies, lightweight structures, autonomous systems, and fuel-efficient designs are improving aircraft capabilities. These developments are enabling greater safety, efficiency, reliability, and versatility across civil and para-public rotorcraft operations.
Market Dynamics:
Driver:
Increasing Demand for Offshore and Utility Helicopter Operations
Growing utilization of helicopters for offshore and utility applications is contributing to the expansion of the civil and para-public rotorcraft market. Rotorcraft offer practical transportation solutions for offshore energy facilities, wind farms, construction projects, remote infrastructure, and locations where conventional vehicles cannot operate efficiently. Development of offshore energy installations and infrastructure is increasing the need for personnel transport, aerial logistics, equipment handling, inspection, and maintenance services. Helicopters are also widely used for power-line surveys, aerial construction, firefighting assistance, infrastructure inspection, and specialized surveying activities. Their vertical takeoff and landing capability, operational flexibility, and access to difficult locations make them particularly suitable for diverse civil and utility missions.
Restraint:
High Acquisition and Operating Costs
The substantial cost associated with purchasing and operating helicopters can constrain market development. Rotorcraft involve high initial investments due to advanced propulsion systems, avionics, transmissions, safety technologies, and specialized equipment. Operators must also manage recurring expenses involving fuel consumption, maintenance, inspections, insurance, replacement components, pilot training, and dedicated facilities. Such financial requirements can create difficulties for smaller operators and government organizations working with constrained budgets. Increasing labor and component costs may further raise total ownership expenses. As a result, operators may delay purchasing new aircraft, extend the service life of existing fleets, or reduce expansion plans, thereby restricting demand for newly manufactured civil and para-public rotorcraft.
Opportunity:
Expansion of Urban Air Mobility and Advanced Air Mobility
Emerging urban and advanced air mobility systems offer considerable growth potential for the civil and para-public rotorcraft industry. Increasing congestion in major cities and the need for quicker transportation are stimulating investment in aerial mobility solutions. Established helicopter manufacturers can apply their expertise in vertical takeoff and landing aircraft to developing mobility platforms. Innovations involving electric propulsion, autonomous operations, distributed propulsion, and sophisticated avionics are supporting the development of more efficient rotorcraft. Potential applications include airport transfers, urban transportation, emergency response, and regional connectivity. Increasing participation by governments and infrastructure providers in aerial mobility programs can generate new business opportunities for helicopter manufacturers, technology suppliers, and operators.
Threat:
Increasing Environmental Regulations and Operating Restrictions
Tightening environmental standards and operational restrictions may create challenges for the helicopter and rotorcraft market. Aviation regulators and governments are increasingly targeting aircraft emissions, noise levels, fuel consumption, and broader environmental impacts. Meeting stricter requirements can require manufacturers to invest significantly in low-emission propulsion, noise-reduction technologies, sustainable aviation fuels, and more efficient aircraft designs. At the operational level, cities and local authorities may restrict flight paths, operating schedules, landing areas, or helicopter activity near residential and environmentally sensitive locations. These requirements can raise compliance and operating costs. If regulatory changes advance faster than technological solutions, helicopter utilization could decline and expansion opportunities could become more limited.
Covid-19 Impact:
COVID-19 created substantial challenges for the civil and para-public rotorcraft industry, primarily through reduced aviation activity, lower passenger demand, and postponements of helicopter purchases and modernization projects. Restrictions on movement and declining tourism negatively affected sightseeing, charter, and corporate transportation services, while financial uncertainty limited capital expenditure by operators. Manufacturing interruptions and global supply-chain disruptions further contributed to delays in aircraft production, component availability, deliveries, and maintenance. Nevertheless, essential rotorcraft operations, particularly medical evacuation, rescue missions, policing, and emergency response, continued to generate demand. Following the relaxation of restrictions, recovering tourism, improving economic conditions, infrastructure investments, and fleet renewal initiatives helped the market progressively recover.
The Conventional Helicopters segment is expected to be the largest during the forecast period
The Conventional Helicopters segment is expected to account for the largest market share during the forecast period, supported by their widespread use in civil and para-public operations. These rotorcraft provide well-established performance, extensive maintenance support, and adaptable configurations for passenger transportation, medical evacuation, policing, firefighting, rescue activities, utility services, and offshore missions. Their ability to take off and land vertically allows operators to reach areas lacking conventional airport infrastructure. Mature certification processes, strong operator experience, and established support networks further reinforce their market position. Ongoing advancements in avionics, engine efficiency, safety technologies, and passenger cabin designs are expected to support sustained demand for conventional helicopters.
The On-Demand Operations segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the On-Demand Operations segment is predicted to witness the highest growth rate, driven by rising preference for flexible helicopter access without the costs and responsibilities associated with owning an aircraft. Customers can arrange rotorcraft services for specific requirements such as corporate transportation, sightseeing, medical evacuation, emergency missions, passenger travel, and specialized utility activities. Digital reservation platforms and advanced fleet-management technologies are improving service accessibility and operational coordination. Businesses and individual users are increasingly favoring asset-light mobility solutions, encouraging demand for shared and scheduled helicopter services. At the same time, operators can improve aircraft utilization by serving multiple customers, creating favorable conditions for continued expansion of on-demand rotorcraft operations.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by its mature rotorcraft industry, developed aviation infrastructure, and broad range of helicopter applications. Rotorcraft are extensively used throughout the region for medical evacuation, policing, firefighting, rescue missions, offshore activities, tourism, and utility services. A strong network of manufacturers, maintenance organizations, and specialized operators provides additional support for market development. Ongoing replacement of aging fleets, advancements in avionics and propulsion technologies, and continued investment in emergency services and public safety are expected to maintain strong regional demand for civil and para-public helicopter operations.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, driven by rapid urbanization, developing aviation infrastructure, and increasing requirements for emergency and public-service operations. Governments and commercial operators are expanding helicopter usage for medical transportation, disaster relief, firefighting, policing, offshore transportation, and passenger services. Growing tourism and infrastructure projects are creating additional demand for flexible rotorcraft capabilities in emerging markets. Fleet replacement programs and adoption of modern avionics, efficient propulsion systems, and advanced safety technologies are also contributing to regional expansion. Increasing investment in air mobility solutions and specialized helicopter applications is expected to further strengthen market growth.
Key players in the market
Some of the key players in Helicopter & Rotorcraft Civil & Para-Public Market include Airbus Helicopters SAS, Bell Textron Inc., Leonardo S.p.A., Sikorsky Aircraft Corporation, Russian Helicopters, Robinson Helicopter Company, MD Helicopters LLC, Enstrom Helicopter Corporation, Kaman Corporation, Kawasaki Heavy Industries, Ltd., Hindustan Aeronautics Limited, Korea Aerospace Industries, Ltd., Aviation Industry Corporation of China , Hélicoptères Guimbal SAS, Schweizer RSG, LLC, Erickson Incorporated, The Boeing Company and Subaru Corporation.
Key Developments:
In July 2026, Sikorsky and Safran Helicopter Engines signed an exploratory teaming agreement to jointly examine cooperation in existing and emerging vertical-lift platforms.
In May 2026:, MD Helicopters renewed a multi-year OEM support contract with Saudi Arabia’s Ministry of National Guard for its MD 530F fleet.
Rotorcraft Types Covered:
• Conventional Helicopters
• Compound Helicopters
• Tiltrotor Aircraft
• Other Rotorcraft
Weight Classes Covered:
• Light Helicopters
• Medium Helicopters
• Super-Medium Helicopters
• Heavy Helicopters
Engine Configurations Covered:
• Single-Engine
• Twin-Engine
• Three-Engine & Above
Rotor Configurations Covered:
• Single Main Rotor
• Coaxial Rotor
• Tandem Rotor
• Intermeshing Rotor
Propulsion Types Covered:
• Piston Engine
• Turboshaft Engine
• Hybrid-Electric Propulsion
• Electric Propulsion
• Other Propulsion Technologies
Sales Channels Covered:
• New Aircraft
• Pre-Owned Aircraft
• Upgraded Aircraft
Ownership Models Covered:
• Direct Ownership
• Leasing
• On-Demand Operations
• Managed Fleet Operations
• Government Ownership
• Public-Private Partnership
Applications Covered:
• Passenger Transport
• Corporate & Executive Transport
• Tourism & Sightseeing
• Emergency Medical Services
• Search & Rescue
• Law Enforcement & Public Safety
• Aerial Firefighting
• Disaster Relief & Emergency Response
• Offshore Energy Support
End Users Covered:
• Commercial Helicopter Operators
• Government & Public-Sector Agencies
• Law Enforcement Agencies
• Emergency Medical Service Providers
• Search & Rescue Organizations
• Firefighting & Disaster Management Agencies
• Energy Companies
• Corporate & Business Operators
• Private Owners
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Rotorcraft Type
5.1 Conventional Helicopters
5.2 Compound Helicopters
5.3 Tiltrotor Aircraft
5.4 Other Rotorcraft
6 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Weight Class
6.1 Light Helicopters
6.2 Medium Helicopters
6.3 Super-Medium Helicopters
6.4 Heavy Helicopters
7 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Engine Configuration
7.1 Single-Engine
7.2 Twin-Engine
7.3 Three-Engine & Above
8 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Rotor Configuration
8.1 Single Main Rotor
8.2 Coaxial Rotor
8.3 Tandem Rotor
8.4 Intermeshing Rotor
9 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Propulsion Type
9.1 Piston Engine
9.2 Turboshaft Engine
9.3 Hybrid-Electric Propulsion
9.4 Electric Propulsion
9.5 Other Propulsion Technologies
10 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Sales Channel
10.1 New Aircraft
10.2 Pre-Owned Aircraft
10.3 Upgraded Aircraft
11 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Ownership Model
11.1 Direct Ownership
11.2 Leasing
11.3 On-Demand Operations
11.4 Managed Fleet Operations
11.5 Government Ownership
11.6 Public-Private Partnership
12 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Application
12.1 Passenger Transport
12.2 Corporate & Executive Transport
12.3 Tourism & Sightseeing
12.4 Emergency Medical Services
12.5 Search & Rescue
12.6 Law Enforcement & Public Safety
12.7 Aerial Firefighting
12.8 Disaster Relief & Emergency Response
12.9 Offshore Energy Support
13 Global Helicopter & Rotorcraft Civil & Para-Public Market, By End User
13.1 Commercial Helicopter Operators
13.2 Government & Public-Sector Agencies
13.3 Law Enforcement Agencies
13.4 Emergency Medical Service Providers
13.5 Search & Rescue Organizations
13.6 Firefighting & Disaster Management Agencies
13.7 Energy Companies
13.8 Corporate & Business Operators
13.9 Private Owners
14 Global Helicopter & Rotorcraft Civil & Para-Public Market, By Geography
14.1 North America
14.1.1 United States
14.1.2 Canada
14.1.3 Mexico
14.2 Europe
14.2.1 United Kingdom
14.2.2 Germany
14.2.3 France
14.2.4 Italy
14.2.5 Spain
14.2.6 Netherlands
14.2.7 Belgium
14.2.8 Sweden
14.2.9 Switzerland
14.2.10 Poland
14.2.11 Rest of Europe
14.3 Asia Pacific
14.3.1 China
14.3.2 Japan
14.3.3 India
14.3.4 South Korea
14.3.5 Australia
14.3.6 Indonesia
14.3.7 Thailand
14.3.8 Malaysia
14.3.9 Singapore
14.3.10 Vietnam
14.3.11 Rest of Asia Pacific
14.4 South America
14.4.1 Brazil
14.4.2 Argentina
14.4.3 Colombia
14.4.4 Chile
14.4.5 Peru
14.4.6 Rest of South America
14.5 Rest of the World (RoW)
14.5.1 Middle East
14.5.1.1 Saudi Arabia
14.5.1.2 United Arab Emirates
14.5.1.3 Qatar
14.5.1.4 Israel
14.5.1.5 Rest of Middle East
14.5.2 Africa
14.5.2.1 South Africa
14.5.2.2 Egypt
14.5.2.3 Morocco
14.5.2.4 Rest of Africa
15 Strategic Market Intelligence
15.1 Industry Value Network and Supply Chain Assessment
15.2 White-Space and Opportunity Mapping
15.3 Product Evolution and Market Life Cycle Analysis
15.4 Channel, Distributor, and Go-to-Market Assessment
16 Industry Developments and Strategic Initiatives
16.1 Mergers and Acquisitions
16.2 Partnerships, Alliances, and Joint Ventures
16.3 New Product Launches and Certifications
16.4 Capacity Expansion and Investments
16.5 Other Strategic Initiatives
17 Company Profiles
17.1 Airbus Helicopters SAS
17.2 Bell Textron Inc.
17.3 Leonardo S.p.A.
17.4 Sikorsky Aircraft Corporation
17.5 Russian Helicopters
17.6 Robinson Helicopter Company
17.7 MD Helicopters LLC
17.8 Enstrom Helicopter Corporation
17.9 Kaman Corporation
17.10 Kawasaki Heavy Industries, Ltd.
17.11 Hindustan Aeronautics Limited
17.12 Korea Aerospace Industries, Ltd.
17.13 Aviation Industry Corporation of China
17.14 Hélicoptères Guimbal SAS
17.15 Schweizer RSG, LLC
17.16 Erickson Incorporated
17.17 The Boeing Company
17.18 Subaru Corporation
List of Tables
1 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Region (2023-2034) ($MN)
2 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Rotorcraft Type (2023-2034) ($MN)
3 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Conventional Helicopters (2023-2034) ($MN)
4 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Compound Helicopters (2023-2034) ($MN)
5 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Tiltrotor Aircraft (2023-2034) ($MN)
6 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Other Rotorcraft (2023-2034) ($MN)
7 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Weight Class (2023-2034) ($MN)
8 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Light Helicopters (2023-2034) ($MN)
9 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Medium Helicopters (2023-2034) ($MN)
10 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Super-Medium Helicopters (2023-2034) ($MN)
11 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Heavy Helicopters (2023-2034) ($MN)
12 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Engine Configuration (2023-2034) ($MN)
13 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Single-Engine (2023-2034) ($MN)
14 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Twin-Engine (2023-2034) ($MN)
15 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Three-Engine & Above (2023-2034) ($MN)
16 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Rotor Configuration (2023-2034) ($MN)
17 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Single Main Rotor (2023-2034) ($MN)
18 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Coaxial Rotor (2023-2034) ($MN)
19 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Tandem Rotor (2023-2034) ($MN)
20 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Intermeshing Rotor (2023-2034) ($MN)
21 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Propulsion Type (2023-2034) ($MN)
22 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Piston Engine (2023-2034) ($MN)
23 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Turboshaft Engine (2023-2034) ($MN)
24 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Hybrid-Electric Propulsion (2023-2034) ($MN)
25 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Electric Propulsion (2023-2034) ($MN)
26 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Other Propulsion Technologies (2023-2034) ($MN)
27 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Sales Channel (2023-2034) ($MN)
28 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By New Aircraft (2023-2034) ($MN)
29 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Pre-Owned Aircraft (2023-2034) ($MN)
30 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Upgraded Aircraft (2023-2034) ($MN)
31 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Ownership Model (2023-2034) ($MN)
32 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Direct Ownership (2023-2034) ($MN)
33 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Leasing (2023-2034) ($MN)
34 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By On-Demand Operations (2023-2034) ($MN)
35 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Managed Fleet Operations (2023-2034) ($MN)
36 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Government Ownership (2023-2034) ($MN)
37 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Public-Private Partnership (2023-2034) ($MN)
38 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Application (2023-2034) ($MN)
39 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Passenger Transport (2023-2034) ($MN)
40 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Corporate & Executive Transport (2023-2034) ($MN)
41 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Tourism & Sightseeing (2023-2034) ($MN)
42 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Emergency Medical Services (2023-2034) ($MN)
43 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Search & Rescue (2023-2034) ($MN)
44 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Law Enforcement & Public Safety (2023-2034) ($MN)
45 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Aerial Firefighting (2023-2034) ($MN)
46 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Disaster Relief & Emergency Response (2023-2034) ($MN)
47 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Offshore Energy Support (2023-2034) ($MN)
48 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By End User (2023-2034) ($MN)
49 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Commercial Helicopter Operators (2023-2034) ($MN)
50 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Government & Public-Sector Agencies (2023-2034) ($MN)
51 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Law Enforcement Agencies (2023-2034) ($MN)
52 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Emergency Medical Service Providers (2023-2034) ($MN)
53 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Search & Rescue Organizations (2023-2034) ($MN)
54 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Firefighting & Disaster Management Agencies (2023-2034) ($MN)
55 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Energy Companies (2023-2034) ($MN)
56 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Corporate & Business Operators (2023-2034) ($MN)
57 Global Helicopter & Rotorcraft Civil & Para-Public Market Outlook, By Private Owners (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
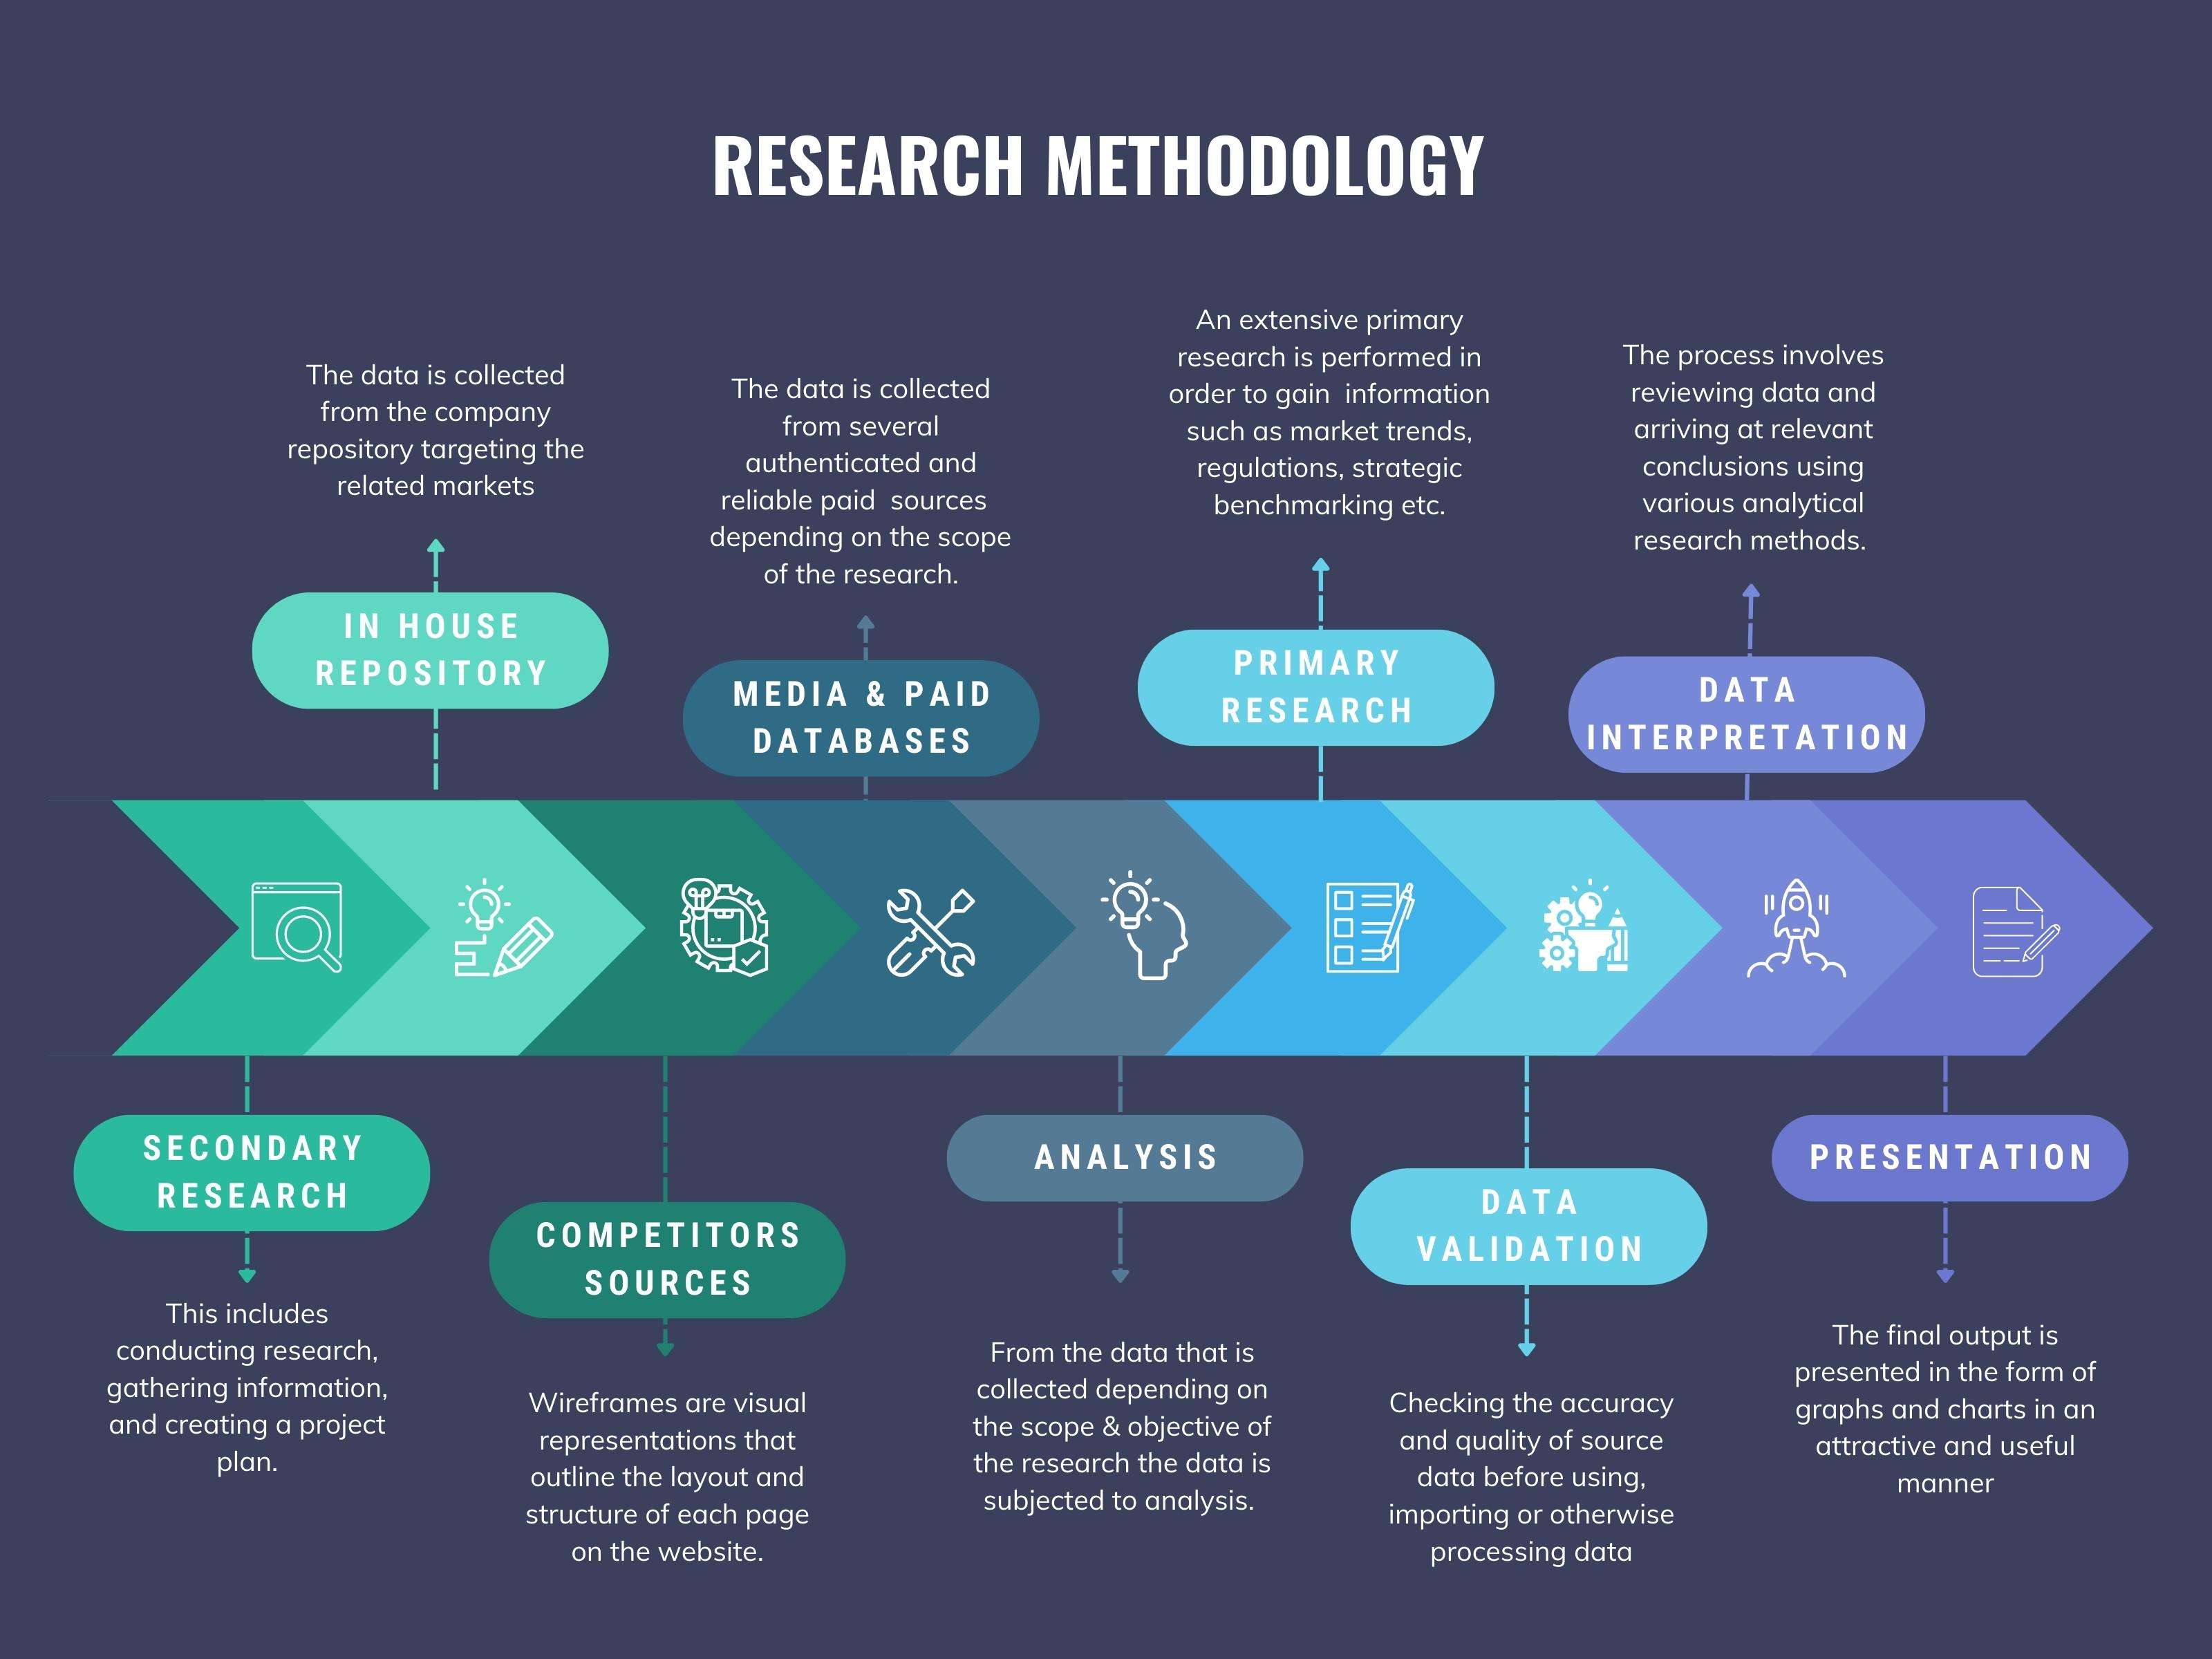
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.