Inductor Market
Inductor Market Forecasts to 2034 – Global Analysis By Inductance (Fixed Inductors and Variable Inductors), Construction Type, Core Type, Shield Type, Mounting Technique, Application, End User, and By Geography
According to Stratistics MRC, the Global Inductor Market is accounted for $5.0 billion in 2026 and is expected to reach $7.0 billion by 2034 growing at a CAGR of 4.3% during the forecast period. Inductors are passive electronic components that store energy in a magnetic field when electric current flows through them, playing a critical role in power regulation, signal filtering, and energy storage across a wide range of electronic devices. The market encompasses various core types including air core, ferrite core, iron core, and other core types, as well as shielded and unshielded inductors. Inductors are essential components in consumer electronics, automotive systems, telecommunications infrastructure, industrial automation, and renewable energy applications.
Market Dynamics:
Driver:
Increasing adoption of electric vehicles and automotive electronics
The rapid growth of the electric vehicle market and increasing electronic content in modern vehicles is a primary driver for the inductor market. EVs rely on inductors for managing power conversion, battery efficiency, and DC-DC conversion stages. Each EV battery pack contains multiple cells requiring their own power stages, multiplying the number of inductors per vehicle ten-fold. Additionally, the rising adoption of advanced driver assistance systems, infotainment, and other automotive electronics is accelerating inductor demand. As global EV sales continue growing and automotive electronics become more sophisticated, inductor consumption in the automotive sector expands significantly, supporting sustained market growth.
Restraint:
Intense price competition and commoditization
Intense competition among inductor manufacturers and the commoditization of standard inductor products represent a major restraint for the market. Multilayer chip inductors and other commodity products face significant price pressure from Asian manufacturers with lower production costs. Price-sensitive consumers and OEMs may prioritize cost over performance for non-critical applications. The fragmentation of the market across numerous suppliers and regions creates margin pressure. These competitive dynamics may limit profitability and R&D investment, particularly for smaller manufacturers.
Opportunity:
Growing demand for high-performance and miniaturized inductors
The increasing demand for high-performance, miniaturized inductors for advanced applications presents significant opportunities for market expansion. The proliferation of 5G technology requires inductors that ensure high-speed signal processing and electromagnetic interference control. Miniaturization trends in consumer electronics and wearables demand smaller, more efficient inductors without compromising performance. Emerging applications including AI servers, automotive-grade power inductors, and thin-film RF inductors are growing at accelerated rates. As technology advances and performance requirements intensify, premium inductor segments capture growing market share.
Threat:
Supply chain disruptions and raw material availability
Supply chain vulnerabilities and raw material availability constraints pose significant threats to the inductor market. Inductor production requires various materials including ferrite, iron, copper, and other metals, with geographically concentrated mining and processing creating supply vulnerabilities. Geopolitical tensions and trade policies can disrupt material flows and affect production costs. Supply chain disruptions including logistics bottlenecks and raw material shortages can affect production and distribution. These uncertainties may impact production planning, cost stability, and market growth.
Covid-19 Impact:
The COVID-19 pandemic had a significant impact on the inductor market. Initial disruptions included factory shutdowns, supply chain interruptions, and reduced consumer electronics production. However, the pandemic accelerated digital transformation and demand for electronic devices including laptops, tablets, and communication equipment. The shift toward remote work and online services increased demand for telecommunications infrastructure. Post-pandemic, consumer electronics and automotive production recovery have supported market growth, with continued demand for inductors across all application segments.
The Ferrite Core segment is expected to be the largest during the forecast period
The Ferrite Core segment is expected to account for the largest market share during the forecast period, driven by the superior magnetic properties, efficiency, and cost-effectiveness of ferrite materials for inductor applications. Ferrite cores offer high magnetic permeability, enabling efficient energy storage and low losses in power supplies and RF circuits. The segment benefits from wide adoption across consumer electronics, automotive, and telecommunications applications. Ferrite cores are the preferred choice for power inductors, which represent a significant portion of the inductor market. With established manufacturing infrastructure and broad applicability, ferrite core inductors maintain the largest core type segment share throughout the forecast period.
The Shielded Inductors segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Shielded Inductors segment is predicted to witness the highest growth rate, fueled by rising electromagnetic interference concerns in compact electronics and tightening EMI suppression standards across automotive, telecommunications, and consumer device applications. Shielded inductors effectively reduce power supply noise and electromagnetic interference, making them essential for smartphones, automotive ECUs, and other sensitive electronic systems. The segment benefits from increasing device density and miniaturization, where EMI management becomes increasingly critical. As EMI regulations tighten and electronic devices become more compact, shielded inductors deliver the fastest segment growth.
Region with largest share:
During the forecast period, the Asia-Pacific region is expected to hold the largest market share, supported by its robust electronics manufacturing sector, concentrated inductor production, and large consumer electronics and automotive markets. Asia-Pacific dominates the inductor market due to its dense electronics manufacturing base and government-backed electric vehicle incentives. The region accounts for a substantial share of global inductor production and consumption, with China, Japan, South Korea, and Southeast Asian countries serving as major manufacturing hubs. With the world's largest electronics production base and growing automotive sector, Asia Pacific maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by continued electronics manufacturing expansion, rising electric vehicle adoption, and increasing consumer electronics demand across the region. The region's large and growing electronics manufacturing base creates sustained inductor demand. Government policies supporting EV adoption and renewable energy are accelerating. Growing middle-class populations and increasing consumer electronics consumption expand the addressable market. As electronics production continues expanding and technology adoption accelerates, Asia Pacific delivers the fastest inductor market growth globally.
Key players in the market
Some of the key players in Inductor Market include TDK Corporation, Murata Manufacturing Co., Ltd., Vishay Intertechnology, Inc., Taiyo Yuden Co., Ltd., Panasonic Industry Co., Ltd., Coilcraft, Inc., Würth Elektronik eiSos GmbH & Co. KG, Sumida Corporation, Bourns, Inc., Chilisin Electronics Corp., Samsung Electro-Mechanics Co., Ltd., KYOCERA AVX Components Corporation, Littelfuse, Inc., Eaton Corporation plc, Bel Fuse Inc., Pulse Electronics Corporation, Delta Electronics, Inc., and Mitsumi Electric Co., Ltd.
Key Developments:
In August 2026, Würth Elektronik introduced the WE-MCRI 1090HL coupled inductor, incorporating controlled leakage inductance to optimize electromagnetic compatibility (EMC) and reduce component count in SEPIC, ZETA, and Ćuk DC-DC converter designs.
In July 2026, Bourns released its SRP2010PA, SRP2510PA, and SRP2512PA series of AEC-Q200 compliant shielded power inductors featuring metal-alloy powder cores for high-current automotive DC-DC conversion circuits.
In April 2026, TAIYO YUDEN commenced mass production of nine new multilayer metal power inductors in its MCOIL™ LSCN series, achieving up to 40% footprint reductions for high-density power supply circuits in smartphones and wearable devices.
In July 2025, TDK Corporation expanded its TFM201612BLEA series of thin-film power inductors for automotive power circuits to handle rated currents up to 5.6 A and operating temperatures up to +150°C.
Inductances Covered:
• Fixed Inductors
• Variable Inductors
Construction Types Covered:
• Wire-Wound Inductors
• Multilayer Inductors
• Film Inductors
• Molded Inductors
• Other Construction Types
Core Types Covered:
• Air Core
• Ferrite Core
• Iron Core
• Other Core Types
Shield Types Covered:
• Shielded Inductors
• Unshielded Inductors
Mounting Techniques Covered:
• Surface-Mount Inductors
• Through-Hole Inductors
Applications Covered:
• Power Applications
• Signal Filtering
• High-Frequency Applications
• General Circuits
• EMI and EMC Suppression
• Wireless Charging
• Other Applications
End Users Covered:
• Automotive
• Consumer Electronics
• Industrial
• RF and Telecommunications
• Computing and Data Centers
• Healthcare
• Aerospace and Defense
• Energy and Power
• Transmission and Distribution
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Inductor Market, By Inductance
5.1 Fixed Inductors
5.2 Variable Inductors
6 Global Inductor Market, By Construction Type
6.1 Wire-Wound Inductors
6.2 Multilayer Inductors
6.3 Film Inductors
6.4 Molded Inductors
6.5 Other Construction Types
7 Global Inductor Market, By Core Type
7.1 Air Core
7.2 Ferrite Core
7.3 Iron Core
7.4 Other Core Types
8 Global Inductor Market, By Shield Type
8.1 Shielded Inductors
8.2 Unshielded Inductors
9 Global Inductor Market, By Mounting Technique
9.1 Surface-Mount Inductors
9.2 Through-Hole Inductors
10 Global Inductor Market, By Application
10.1 Power Applications
10.1.1 Power Conversion
10.1.2 Power Management
10.1.3 Voltage Regulation
10.1.4 Power Factor Correction
10.2 Signal Filtering
10.2.1 Low-Pass Filtering
10.2.2 Band-Pass Filtering
10.2.3 Noise Filtering
10.3 High-Frequency Applications
10.3.1 RF Circuits
10.3.2 Impedance Matching
10.3.3 Oscillators and Tuned Circuits
10.4 General Circuits
10.5 EMI and EMC Suppression
10.6 Wireless Charging
10.7 Other Applications
11 Global Inductor Market, By End User
11.1 Automotive
11.2 Consumer Electronics
11.3 Industrial
11.4 RF and Telecommunications
11.5 Computing and Data Centers
11.6 Healthcare
11.7 Aerospace and Defense
11.8 Energy and Power
11.9 Transmission and Distribution
11.10 Other End Users
12 Global Inductor Market, By Geography
12.1 North America
12.1.1 United States
12.1.2 Canada
12.1.3 Mexico
12.2 Europe
12.2.1 United Kingdom
12.2.2 Germany
12.2.3 France
12.2.4 Italy
12.2.5 Spain
12.2.6 Netherlands
12.2.7 Belgium
12.2.8 Sweden
12.2.9 Switzerland
12.2.10 Poland
12.2.11 Rest of Europe
12.3 Asia Pacific
12.3.1 China
12.3.2 Japan
12.3.3 India
12.3.4 South Korea
12.3.5 Australia
12.3.6 Indonesia
12.3.7 Thailand
12.3.8 Malaysia
12.3.9 Singapore
12.3.10 Vietnam
12.3.11 Rest of Asia Pacific
12.4 South America
12.4.1 Brazil
12.4.2 Argentina
12.4.3 Colombia
12.4.4 Chile
12.4.5 Peru
12.4.6 Rest of South America
12.5 Rest of the World (RoW)
12.5.1 Middle East
12.5.1.1 Saudi Arabia
12.5.1.2 United Arab Emirates
12.5.1.3 Qatar
12.5.1.4 Israel
12.5.1.5 Rest of Middle East
12.5.2 Africa
12.5.2.1 South Africa
12.5.2.2 Egypt
12.5.2.3 Morocco
12.5.2.4 Rest of Africa
13 Strategic Market Intelligence
13.1 Industry Value Network and Supply Chain Assessment
13.2 White-Space and Opportunity Mapping
13.3 Product Evolution and Market Life Cycle Analysis
13.4 Channel, Distributor, and Go-to-Market Assessment
14 Industry Developments and Strategic Initiatives
14.1 Mergers and Acquisitions
14.2 Partnerships, Alliances, and Joint Ventures
14.3 New Product Launches and Certifications
14.4 Capacity Expansion and Investments
14.5 Other Strategic Initiatives
15 Company Profiles
15.1 TDK Corporation
15.2 Murata Manufacturing Co., Ltd.
15.3 Vishay Intertechnology, Inc.
15.4 Taiyo Yuden Co., Ltd.
15.5 Panasonic Industry Co., Ltd.
15.6 Coilcraft, Inc.
15.7 Würth Elektronik eiSos GmbH & Co. KG
15.8 Sumida Corporation
15.9 Bourns, Inc.
15.10 Chilisin Electronics Corp.
15.11 Samsung Electro-Mechanics Co., Ltd.
15.12 KYOCERA AVX Components Corporation
15.13 Littelfuse, Inc.
15.14 Eaton Corporation plc
15.15 Bel Fuse Inc.
15.16 Pulse Electronics Corporation
15.17 Delta Electronics, Inc.
15.18 Mitsumi Electric Co., Ltd.
List of Tables
1 Global Inductor Market Outlook, By Region (2023–2034) ($MN)
2 Global Inductor Market Outlook, By Inductance (2023–2034) ($MN)
3 Global Inductor Market Outlook, By Fixed Inductors (2023–2034) ($MN)
4 Global Inductor Market Outlook, By Variable Inductors (2023–2034) ($MN)
5 Global Inductor Market Outlook, By Construction Type (2023–2034) ($MN)
6 Global Inductor Market Outlook, By Wire-Wound Inductors (2023–2034) ($MN)
7 Global Inductor Market Outlook, By Multilayer Inductors (2023–2034) ($MN)
8 Global Inductor Market Outlook, By Film Inductors (2023–2034) ($MN)
9 Global Inductor Market Outlook, By Molded Inductors (2023–2034) ($MN)
10 Global Inductor Market Outlook, By Other Construction Types (2023–2034) ($MN)
11 Global Inductor Market Outlook, By Core Type (2023–2034) ($MN)
12 Global Inductor Market Outlook, By Air Core (2023–2034) ($MN)
13 Global Inductor Market Outlook, By Ferrite Core (2023–2034) ($MN)
14 Global Inductor Market Outlook, By Iron Core (2023–2034) ($MN)
15 Global Inductor Market Outlook, By Other Core Types (2023–2034) ($MN)
16 Global Inductor Market Outlook, By Shield Type (2023–2034) ($MN)
17 Global Inductor Market Outlook, By Shielded Inductors (2023–2034) ($MN)
18 Global Inductor Market Outlook, By Unshielded Inductors (2023–2034) ($MN)
19 Global Inductor Market Outlook, By Mounting Technique (2023–2034) ($MN)
20 Global Inductor Market Outlook, By Surface-Mount Inductors (2023–2034) ($MN)
21 Global Inductor Market Outlook, By Through-Hole Inductors (2023–2034) ($MN)
22 Global Inductor Market Outlook, By Application (2023–2034) ($MN)
23 Global Inductor Market Outlook, By Power Applications (2023–2034) ($MN)
24 Global Inductor Market Outlook, By Power Conversion (2023–2034) ($MN)
25 Global Inductor Market Outlook, By Power Management (2023–2034) ($MN)
26 Global Inductor Market Outlook, By Voltage Regulation (2023–2034) ($MN)
27 Global Inductor Market Outlook, By Power Factor Correction (2023–2034) ($MN)
28 Global Inductor Market Outlook, By Signal Filtering (2023–2034) ($MN)
29 Global Inductor Market Outlook, By Low-Pass Filtering (2023–2034) ($MN)
30 Global Inductor Market Outlook, By Band-Pass Filtering (2023–2034) ($MN)
31 Global Inductor Market Outlook, By Noise Filtering (2023–2034) ($MN)
32 Global Inductor Market Outlook, By High-Frequency Applications (2023–2034) ($MN)
33 Global Inductor Market Outlook, By RF Circuits (2023–2034) ($MN)
34 Global Inductor Market Outlook, By Impedance Matching (2023–2034) ($MN)
35 Global Inductor Market Outlook, By Oscillators and Tuned Circuits (2023–2034) ($MN)
36 Global Inductor Market Outlook, By General Circuits (2023–2034) ($MN)
37 Global Inductor Market Outlook, By EMI and EMC Suppression (2023–2034) ($MN)
38 Global Inductor Market Outlook, By Wireless Charging (2023–2034) ($MN)
39 Global Inductor Market Outlook, By Other Applications (2023–2034) ($MN)
40 Global Inductor Market Outlook, By End User (2023–2034) ($MN)
41 Global Inductor Market Outlook, By Automotive (2023–2034) ($MN)
42 Global Inductor Market Outlook, By Consumer Electronics (2023–2034) ($MN)
43 Global Inductor Market Outlook, By Industrial (2023–2034) ($MN)
44 Global Inductor Market Outlook, By RF and Telecommunications (2023–2034) ($MN)
45 Global Inductor Market Outlook, By Computing and Data Centers (2023–2034) ($MN)
46 Global Inductor Market Outlook, By Healthcare (2023–2034) ($MN)
47 Global Inductor Market Outlook, By Aerospace and Defense (2023–2034) ($MN)
48 Global Inductor Market Outlook, By Energy and Power (2023–2034) ($MN)
49 Global Inductor Market Outlook, By Transmission and Distribution (2023–2034) ($MN)
50 Global Inductor Market Outlook, By Other End Users (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
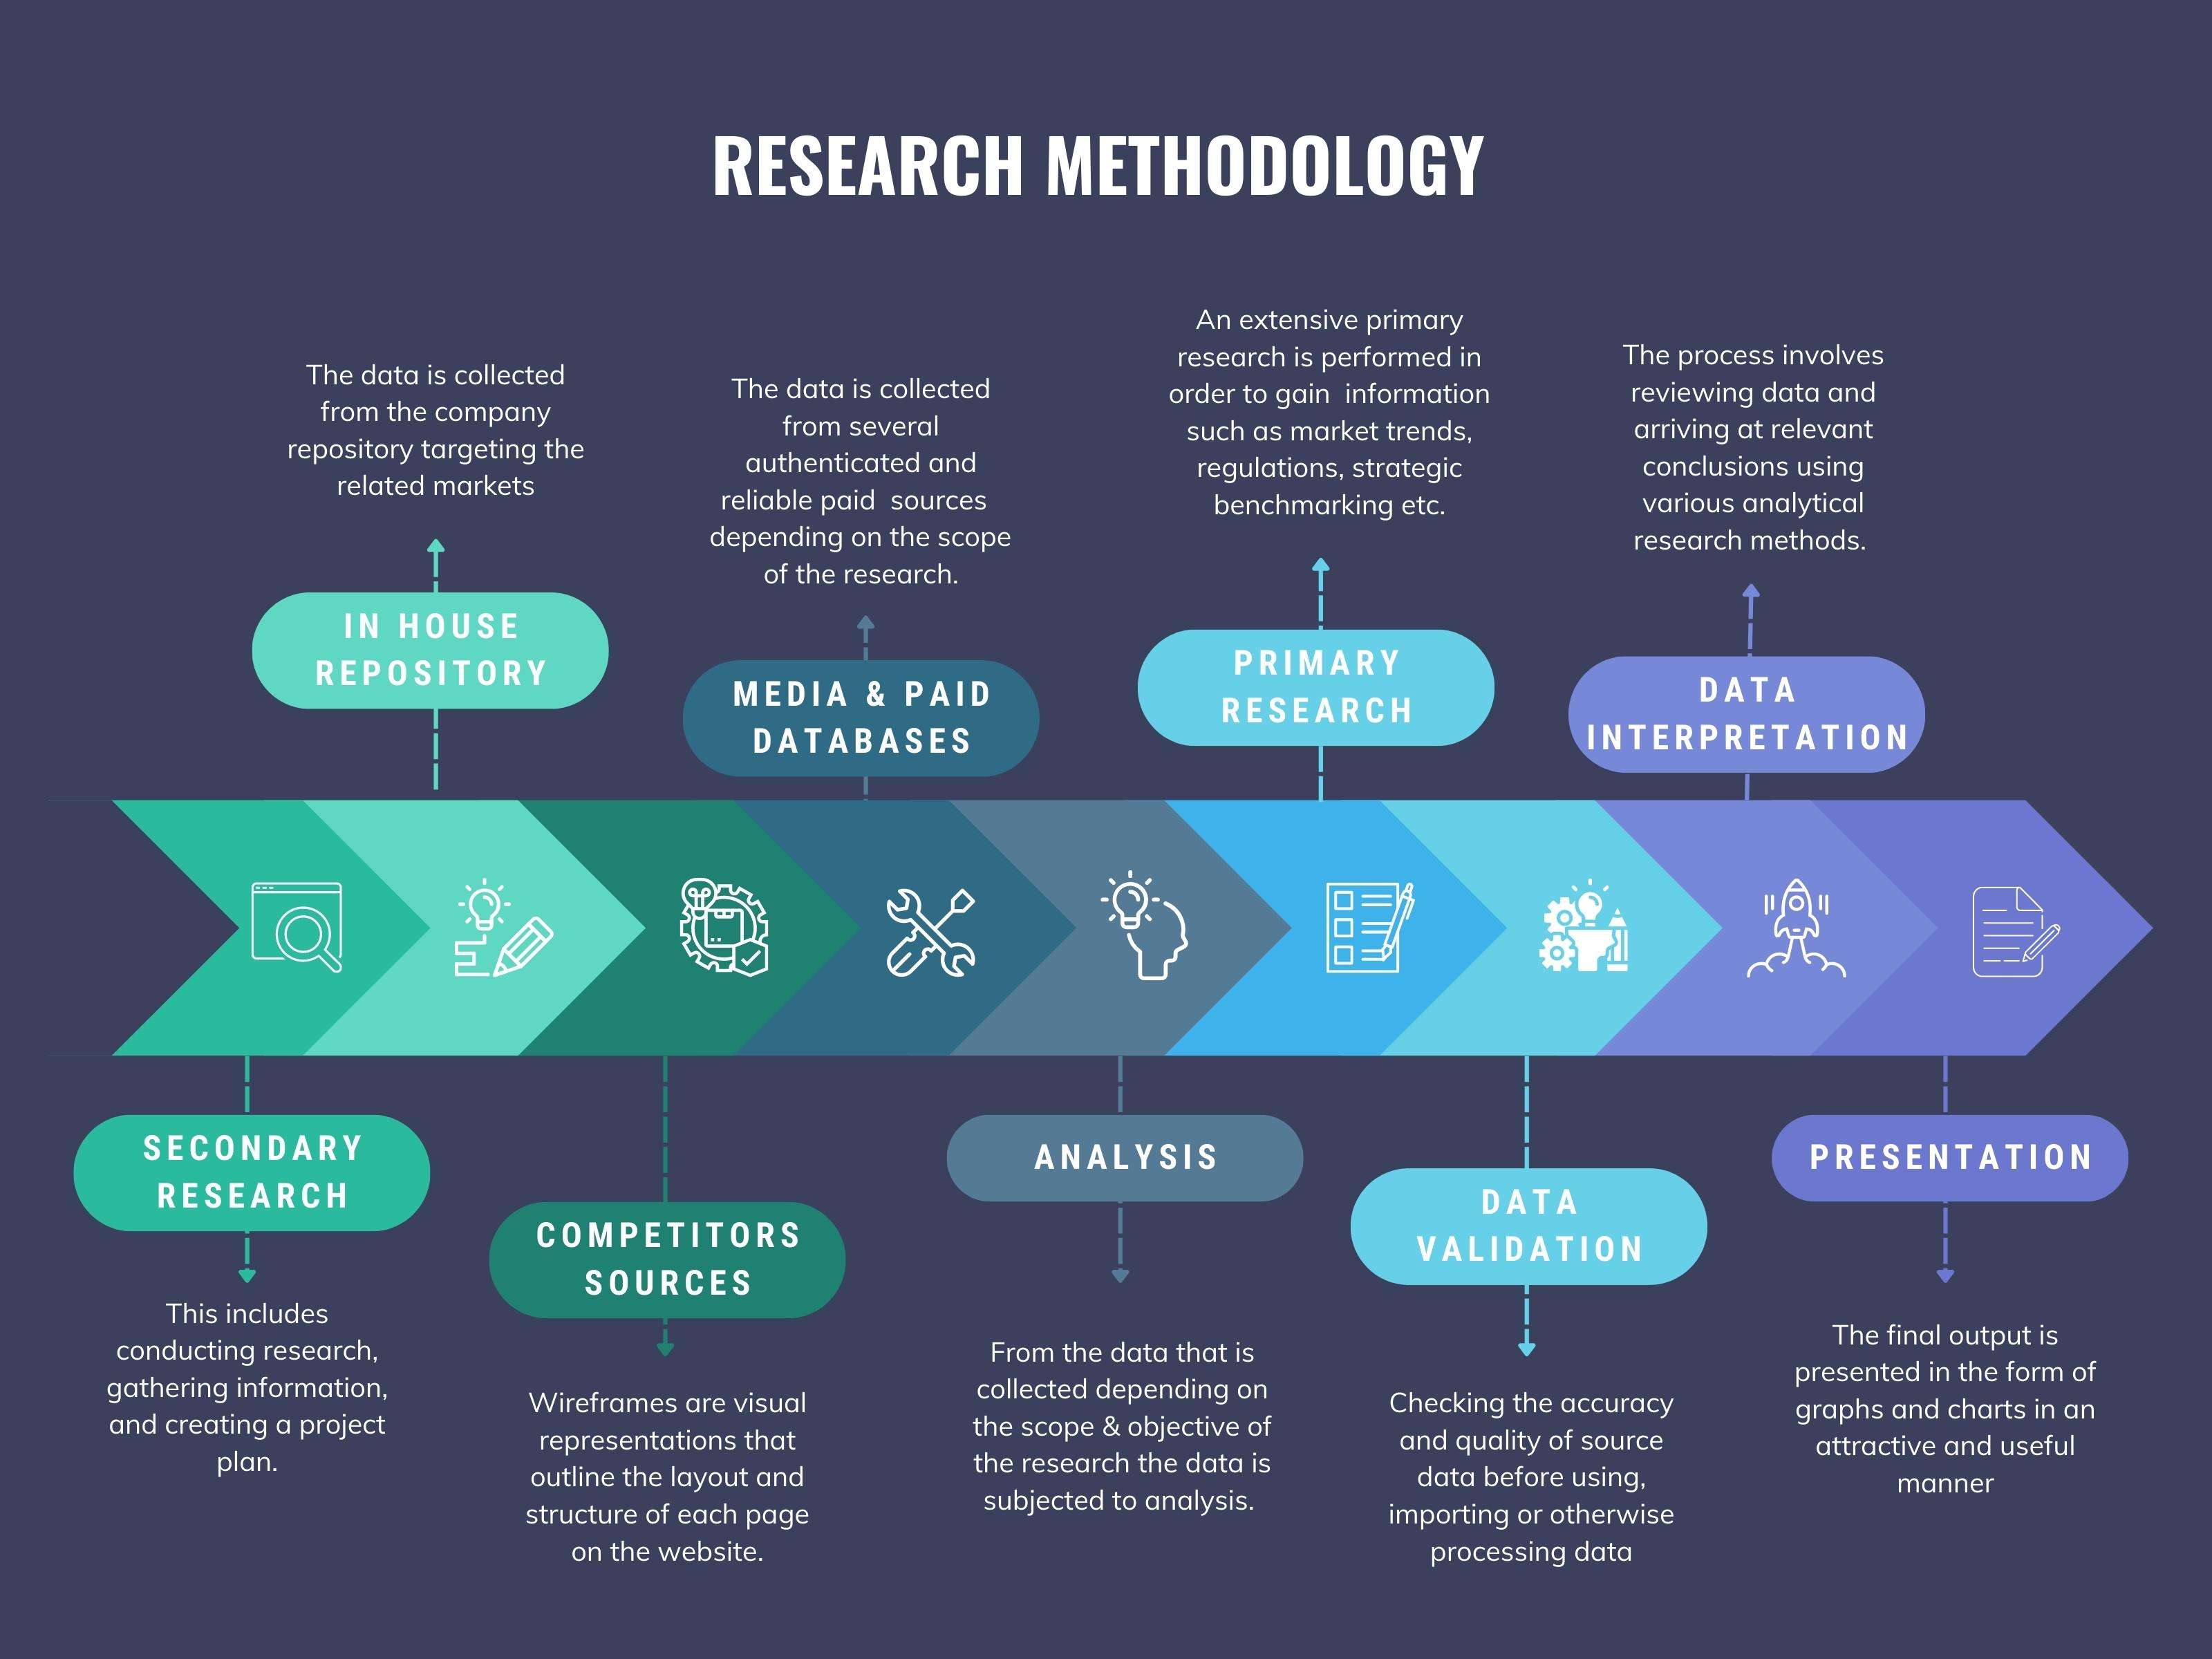
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.