Lead Carbon Battery Market
Lead-Carbon Battery Market Forecasts to 2034 – Global Analysis By Battery Type (Flooded Lead-Carbon Batteries, Valve-Regulated Lead-Carbon Batteries, Absorbent Glass Mat Lead-Carbon Batteries, and Carbon-Enhanced Bipolar Lead-Acid Batteries), Power and Energy Rating, Application, End User, and By Geography
Market Dynamics:
Driver:
Partial charging creates a practical role for carbon-enhanced electrodes
Solar-assisted telecommunications sites and hybrid power systems may operate for long periods without returning their batteries to a fully charged condition. Conventional lead-acid negative plates can suffer from persistent sulfation under such duty, reducing useful performance. Carbon-enhanced designs aim to improve charge acceptance and tolerance of repeated partial charging, making them relevant where generation arrives in short or variable periods. Buyers familiar with lead-based equipment may also find these products easier to evaluate within existing maintenance practices. Demand depends on demonstrating that the improved cycling behavior offsets any additional purchase cost in the actual site operating pattern.
Restraint:
Carbon enhancement does not remove lead-based operating constraints
Lead-carbon batteries remain heavy relative to many lithium-ion alternatives, which limits their appeal where transport, floor loading or installation space is expensive. Temperature, charging strategy and depth of discharge continue to influence service life. Depending on formulation, increased carbon can also introduce competing effects such as hydrogen evolution, requiring careful electrode and electrolyte design. Buyers cannot assume that all products carrying the lead-carbon label deliver comparable benefits. Responsible collection and recycling remain essential throughout the value chain. These practical requirements can reduce the attractiveness of projects that lack reliable servicing, suitable charging controls or an established return channel.
Opportunity:
Existing backup networks offer a route to targeted upgrades
Operators with established lead-acid installations can evaluate lead-carbon replacements when their duty cycle has become more demanding through added solar generation or more frequent outages. The opportunity is strongest where existing racks, electrical interfaces and maintenance skills reduce conversion costs, although charging compatibility still requires verification. Suppliers can differentiate through clear application guidance, documented cycling tests and take-back arrangements. Combining replacement programs with remote monitoring could help operators identify undercharging and temperature problems before premature failure occurs. This approach creates value through longer useful service and better asset management rather than a simple change in battery labeling.
Threat:
Lithium-ion competition challenges the lifetime cost proposition
Lithium iron phosphate batteries increasingly compete for renewable storage and telecommunications projects where frequent cycling, weight and usable capacity matter. Established lithium-ion suppliers can offer integrated controls and operating references that make switching more attractive to customers. Lead-carbon products must therefore justify their position using delivered energy, replacement intervals and conversion costs across the intended service period. Poor-quality products or exaggerated cycle-life claims could damage confidence in the broader category. Environmental performance also depends on effective collection and controlled recycling, so weaknesses in local recovery practices can undermine an otherwise familiar and accessible supply chain.
Covid-19 Impact:
COVID-19 disrupted battery manufacturing, logistics and access to installation sites, affecting replacement schedules for telecommunications, industrial backup and distributed power systems. Lead-carbon suppliers were exposed to these broader lead-acid supply-chain pressures rather than to a separate pandemic-specific demand cycle. Networks and critical facilities still needed reliable backup, while restricted site visits increased the value of monitoring and longer replacement intervals. As normal activity resumed, customers placed renewed emphasis on stock availability and dependable servicing. The experience also encouraged closer attention to whether batteries were correctly charged during prolonged changes in facility use or maintenance routines.
The Valve-Regulated Lead-Carbon Batteries segment is expected to be the largest during the forecast period
Valve-Regulated Lead-Carbon Batteries are expected to hold the largest share because their packaging fits many established stationary backup and telecommunications installations. Reduced routine electrolyte maintenance can be valuable at dispersed sites, while carbon enhancement addresses charging patterns that are more demanding than continuous float service. Purchasers can draw on familiar installation practices, provided they verify product-specific charging requirements and ventilation provisions. The segment's breadth includes different internal constructions, so performance should be assessed using comparable test conditions. Its commercial position rests on a combination of practical deployment, accessible servicing and demonstrated durability in the intended duty cycle.
The Renewable Energy Storage segment is expected to have the highest CAGR during the forecast period
Renewable Energy Storage is anticipated to post the highest growth rate as variable solar and wind output increases the number of applications involving repeated partial charging. Lead-carbon systems can be considered where existing infrastructure, local service capability and initial budget constraints influence technology selection. Hybrid sites that combine renewables with generators may offer a particularly relevant operating pattern. However, growth depends on realistic sizing and charge management, since carbon additives do not eliminate the need for appropriate operating limits. Products with transparent cycling data and credible replacement economics should be better placed to compete for these installations.
Region with largest share:
Asia Pacific is expected to account for the largest regional share, supported by established lead-based battery manufacturing and extensive telecommunications, industrial and distributed-power requirements. Chinese suppliers provide commercial lead-carbon products, while the wider region offers applications where familiar equipment and accessible service networks influence purchasing decisions. Solar-assisted backup and off-grid facilities can create demand for improved partial-charge performance. Competition from lithium-ion batteries is also particularly strong, so scale alone does not assure continued leadership. Regional suppliers need consistent quality, clear application limits and reliable collection arrangements to sustain confidence as customers compare complete operating costs.
Region with highest CAGR:
Rest of the World (RoW) is anticipated to achieve the highest CAGR, with selected African and Middle Eastern markets offering opportunities in telecommunications, remote power and solar-assisted backup. Expensive site visits and variable grid availability can make improved cycling tolerance valuable, especially where operators already maintain lead-acid equipment. Adoption will vary substantially between countries and applications rather than following one uniform regional pattern. Charging control, heat exposure and access to responsible recycling need to be addressed in each project. Suppliers that combine suitable battery sizing with local technical support may be better positioned to secure repeat installations.
Key players in the market
Some of the key players in the Lead-Carbon Battery Market include Narada Power Source Co., Ltd., Stryten Energy LLC, GS Yuasa Corporation, East Penn Manufacturing Co., Exide Technologies, EnerSys, Leoch International Technology Limited, Sacred Sun Power Sources Co., Ltd., Shuangdeng Group Co., Ltd., Coslight Technology International Group, Chilwee Group Co., Ltd., HBL Power Systems Limited, Trojan Battery Company, LLC, HOPPECKE Batterien GmbH & Co. KG, and Furukawa Battery Co., Ltd.
Key Developments:
In September 2026, the Journal of Energy Storage published research on a hybrid simulation and learning model for predicting lead-carbon battery degradation. The study combined experimental cycling information with physics-based modeling to assess capacity behavior. It represents a research development relevant to service-life estimation, rather than a new commercial battery launch.
In July 2026, Exide Technologies introduced Marathon Pure Energy and Pure Energy FT batteries for critical backup applications. These TPPL AGM products belong to the parent advanced lead-acid battery market and should not be relabeled as lead-carbon. Their launch illustrates continued product competition around replacement compatibility, servicing and lifetime cost in shared customer segments.
In May 2026, Clarios provided a progress update on its U.S. energy manufacturing strategy, including investment across production facilities and advances in critical-minerals recycling. This parent advanced lead-acid battery market development is relevant to lead-carbon suppliers through the wider manufacturing and recovery infrastructure, without constituting a dedicated lead-carbon product announcement.
Battery Types Covered:
• Flooded Lead-Carbon Batteries
• Valve-Regulated Lead-Carbon Batteries
• Absorbent Glass Mat Lead-Carbon Batteries
• Carbon-Enhanced Bipolar Lead-Acid Batteries
Power and Energy Ratings Covered:
• Below 100 Ah
• 100 to 500 Ah
• Above 500 Ah
Applications Covered:
• Renewable Energy Storage
• Telecommunications Backup
• Microgrid and Off-Grid Power
• Automotive Start-Stop and Auxiliary Power
• Uninterruptible Power Supply
End Users Covered:
• Utilities and Renewable Energy Operators
• Telecommunications
• Automotive
• Industrial and Commercial
• Residential and Off-Grid Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
Saudi Arabia
United Arab Emirates
Qatar
Israel
Rest of Middle East
o Africa
South Africa
Egypt
Morocco
Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Lead-Carbon Battery Market, By Battery Type
5.1 Flooded Lead-Carbon Batteries
5.2 Valve-Regulated Lead-Carbon Batteries
5.3 Absorbent Glass Mat Lead-Carbon Batteries
5.4 Carbon-Enhanced Bipolar Lead-Acid Batteries
6 Global Lead-Carbon Battery Market, By Power and Energy Rating
6.1 Below 100 Ah
6.2 100 to 500 Ah
6.3 Above 500 Ah
7 Global Lead-Carbon Battery Market, By Application
7.1 Renewable Energy Storage
7.2 Telecommunications Backup
7.3 Microgrid and Off-Grid Power
7.4 Automotive Start-Stop and Auxiliary Power
7.5 Uninterruptible Power Supply
8 Global Lead-Carbon Battery Market, By End User
8.1 Utilities and Renewable Energy Operators
8.2 Telecommunications
8.3 Automotive
8.4 Industrial and Commercial
8.5 Residential and Off-Grid Users
9 Global Lead-Carbon Battery Market, By Geography
9.1 North America
9.1.1 United States
9.1.2 Canada
9.1.3 Mexico
9.2 Europe
9.2.1 United Kingdom
9.2.2 Germany
9.2.3 France
9.2.4 Italy
9.2.5 Spain
9.2.6 Netherlands
9.2.7 Belgium
9.2.8 Sweden
9.2.9 Switzerland
9.2.10 Poland
9.2.11 Rest of Europe
9.3 Asia Pacific
9.3.1 China
9.3.2 Japan
9.3.3 India
9.3.4 South Korea
9.3.5 Australia
9.3.6 Indonesia
9.3.7 Thailand
9.3.8 Malaysia
9.3.9 Singapore
9.3.10 Vietnam
9.3.11 Rest of Asia Pacific
9.4 South America
9.4.1 Brazil
9.4.2 Argentina
9.4.3 Colombia
9.4.4 Chile
9.4.5 Peru
9.4.6 Rest of South America
9.5 Rest of the World (RoW)
9.5.1 Middle East
9.5.1.1 Saudi Arabia
9.5.1.2 United Arab Emirates
9.5.1.3 Qatar
9.5.1.4 Israel
9.5.1.5 Rest of Middle East
9.5.2 Africa
9.5.2.1 South Africa
9.5.2.2 Egypt
9.5.2.3 Morocco
9.5.2.4 Rest of Africa
10 Strategic Market Intelligence
10.1 Industry Value Network and Supply Chain Assessment
10.2 White-Space and Opportunity Mapping
10.3 Product Evolution and Market Life Cycle Analysis
10.4 Channel, Distributor, and Go-to-Market Assessment
11 Industry Developments and Strategic Initiatives
11.1 Mergers and Acquisitions
11.2 Partnerships, Alliances, and Joint Ventures
11.3 New Product Launches and Certifications
11.4 Capacity Expansion and Investments
11.5 Other Strategic Initiatives
12 Company Profiles
12.1 Narada Power Source Co., Ltd.
12.2 Stryten Energy LLC
12.3 GS Yuasa Corporation
12.4 East Penn Manufacturing Co.
12.5 Exide Technologies
12.6 EnerSys
12.7 Leoch International Technology Limited
12.8 Sacred Sun Power Sources Co., Ltd.
12.9 Shuangdeng Group Co., Ltd.
12.10 Coslight Technology International Group
12.11 Chilwee Group Co., Ltd.
12.12 HBL Power Systems Limited
12.13 Trojan Battery Company, LLC
12.14 HOPPECKE Batterien GmbH & Co. KG
12.15 Furukawa Battery Co., Ltd.
List of Tables
1 Global Lead-Carbon Battery Market Outlook, By Region (2023–2034) ($MN)
2 Global Lead-Carbon Battery Market Outlook, By Battery Type (2023–2034) ($MN)
3 Global Lead-Carbon Battery Market Outlook, By Flooded Lead-Carbon Batteries (2023–2034) ($MN)
4 Global Lead-Carbon Battery Market Outlook, By Valve-Regulated Lead-Carbon Batteries (2023–2034) ($MN)
5 Global Lead-Carbon Battery Market Outlook, By Absorbent Glass Mat Lead-Carbon Batteries (2023–2034) ($MN)
6 Global Lead-Carbon Battery Market Outlook, By Carbon-Enhanced Bipolar Lead-Acid Batteries (2023–2034) ($MN)
7 Global Lead-Carbon Battery Market Outlook, By Power and Energy Rating (2023–2034) ($MN)
8 Global Lead-Carbon Battery Market Outlook, By Below 100 Ah (2023–2034) ($MN)
9 Global Lead-Carbon Battery Market Outlook, By 100 to 500 Ah (2023–2034) ($MN)
10 Global Lead-Carbon Battery Market Outlook, By Above 500 Ah (2023–2034) ($MN)
11 Global Lead-Carbon Battery Market Outlook, By Application (2023–2034) ($MN)
12 Global Lead-Carbon Battery Market Outlook, By Renewable Energy Storage (2023–2034) ($MN)
13 Global Lead-Carbon Battery Market Outlook, By Telecommunications Backup (2023–2034) ($MN)
14 Global Lead-Carbon Battery Market Outlook, By Microgrid and Off-Grid Power (2023–2034) ($MN)
15 Global Lead-Carbon Battery Market Outlook, By Automotive Start-Stop and Auxiliary Power (2023–2034) ($MN)
16 Global Lead-Carbon Battery Market Outlook, By Uninterruptible Power Supply (2023–2034) ($MN)
17 Global Lead-Carbon Battery Market Outlook, By End User (2023–2034) ($MN)
18 Global Lead-Carbon Battery Market Outlook, By Utilities and Renewable Energy Operators (2023–2034) ($MN)
19 Global Lead-Carbon Battery Market Outlook, By Telecommunications (2023–2034) ($MN)
20 Global Lead-Carbon Battery Market Outlook, By Automotive (2023–2034) ($MN)
21 Global Lead-Carbon Battery Market Outlook, By Industrial and Commercial (2023–2034) ($MN)
22 Global Lead-Carbon Battery Market Outlook, By Residential and Off-Grid Users (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
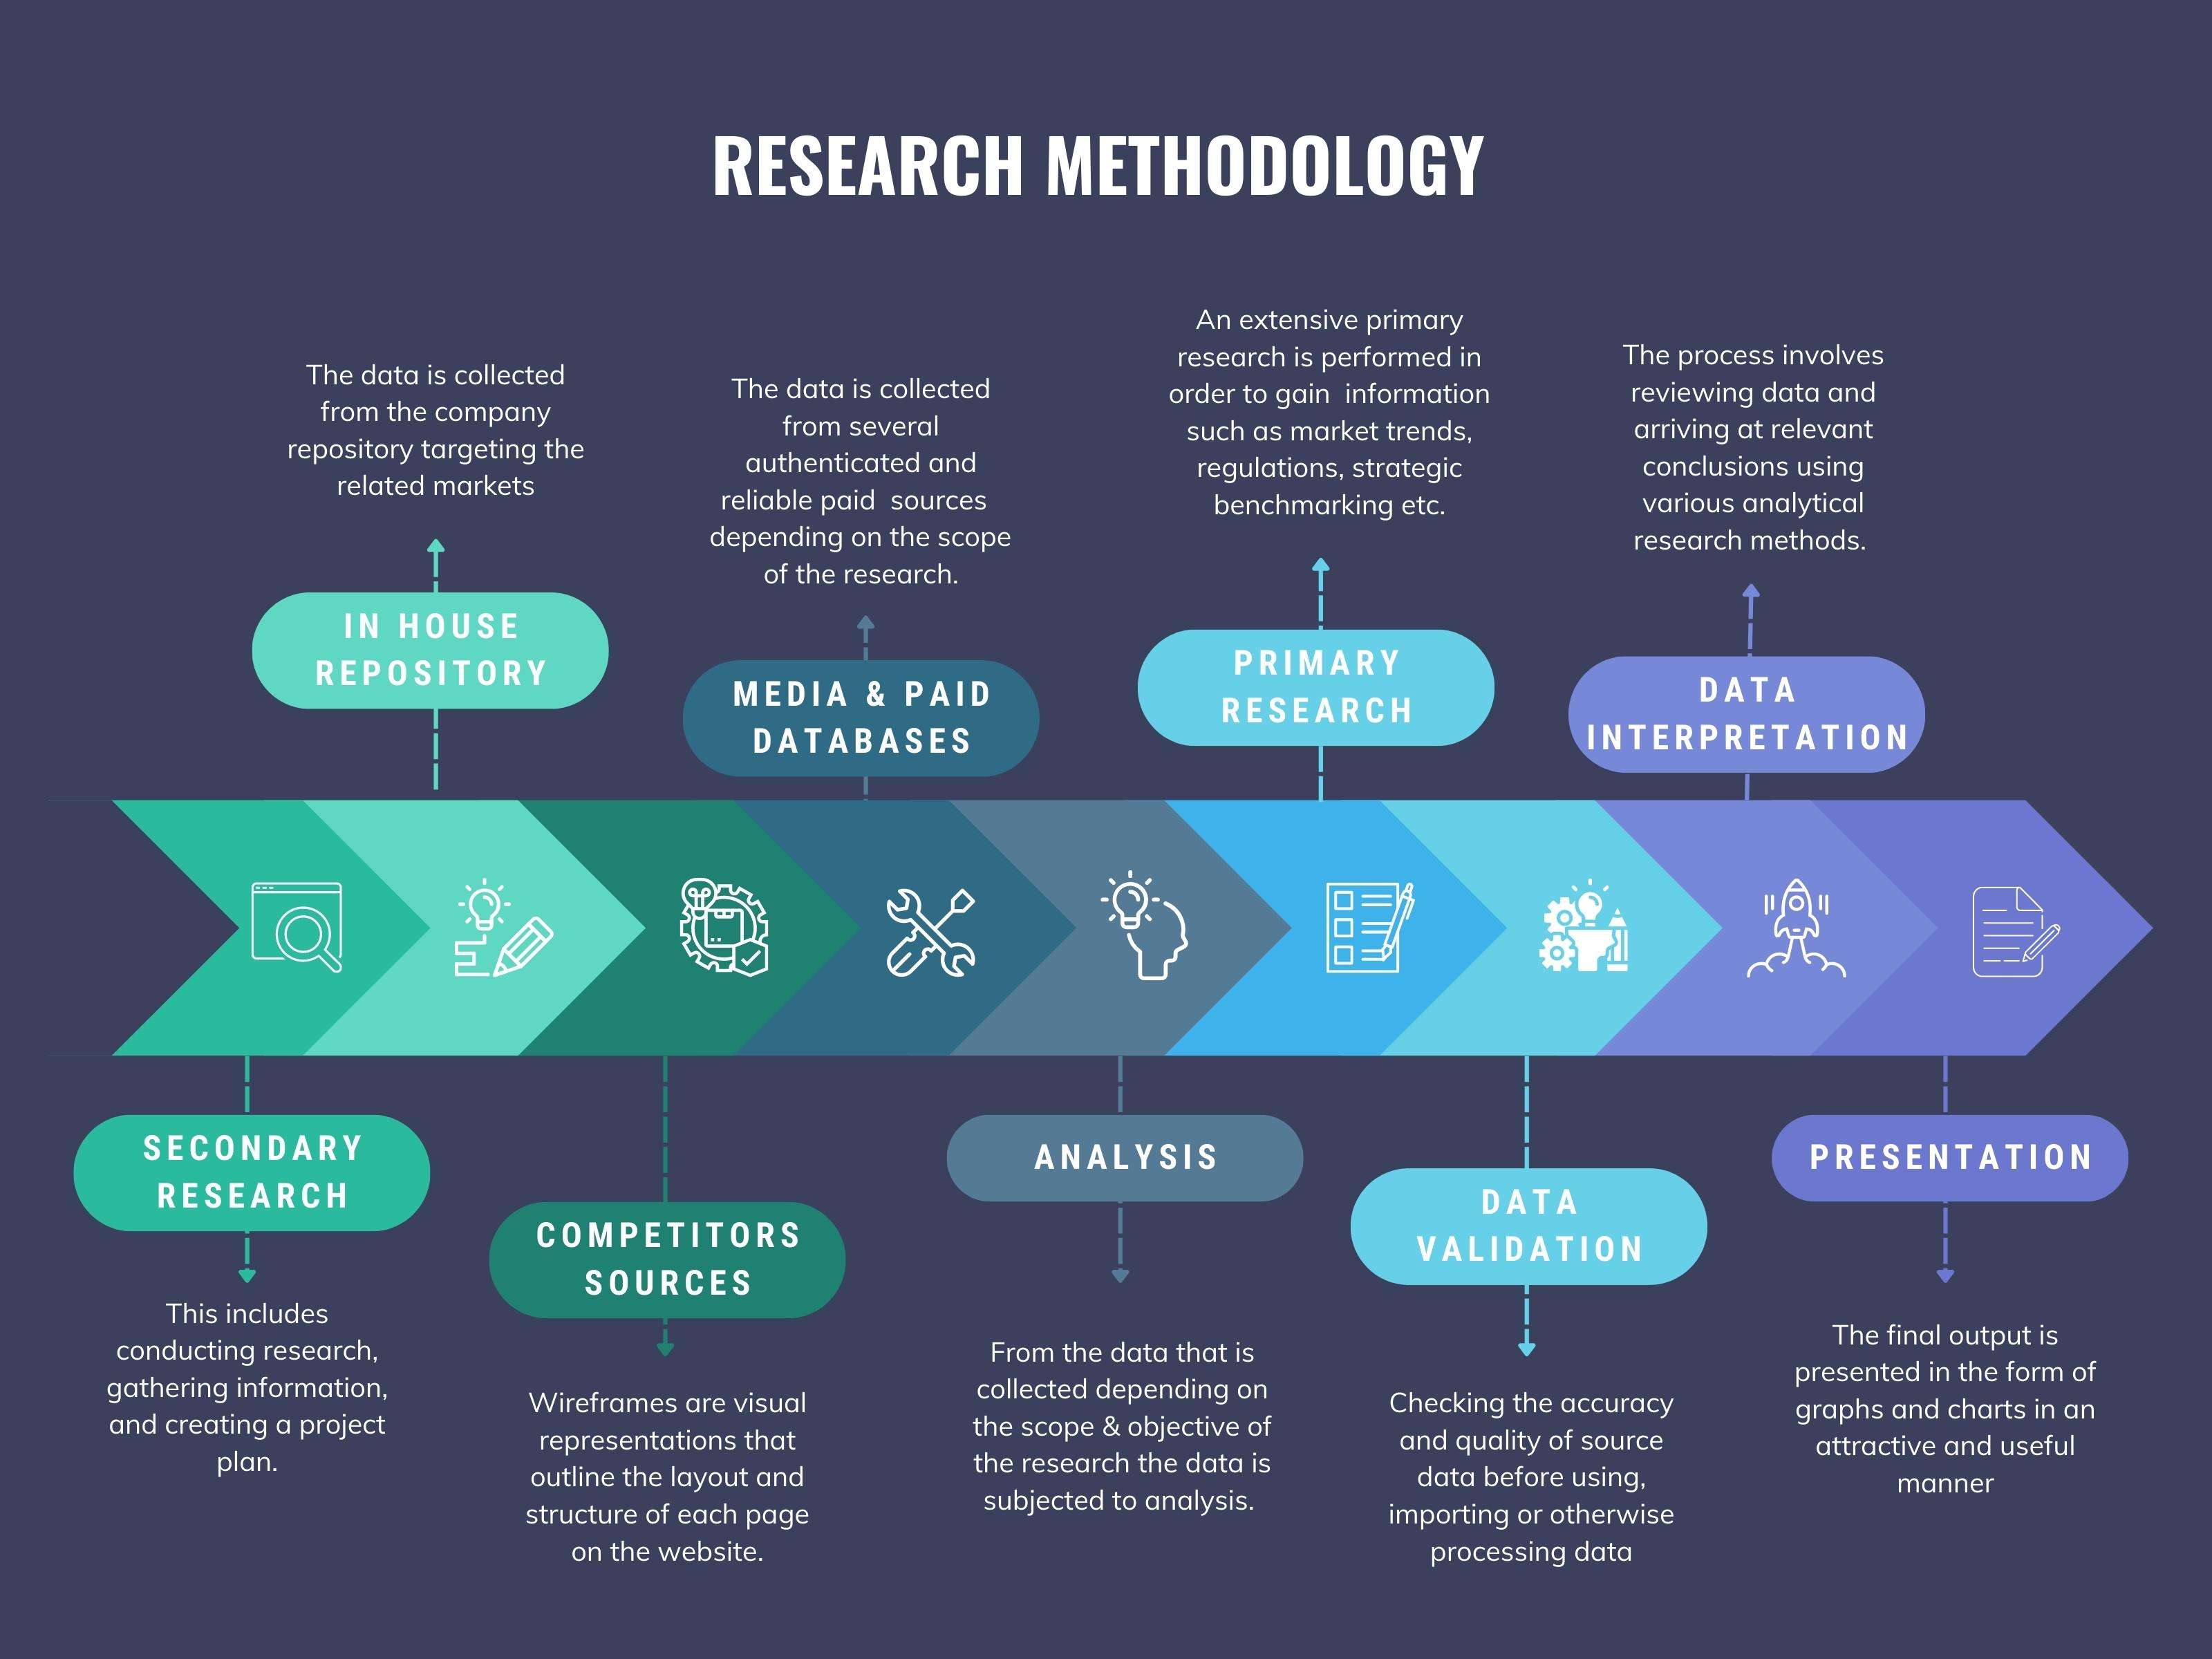
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.