Pet Retail Market
Pet Retail Market Forecasts to 2034 – Global Analysis By Product Category (Pet Food & Nutrition (Dry Food, Wet Food, Treats & Snacks, and Pet Supplements & Nutraceuticals), Pet Accessories & Supplies (Collars, Harnesses & Leashes, Beds & Bedding, Bowls & Feeders, Toys & Enrichment Products, Crates, Cages & Carriers, and Pet Apparel & Footwear), Pet Grooming & Hygiene Products (Shampoos & Conditioners, Brushes, Combs & Grooming Tools, Dental Care Products, Nail Care Products, Waste Management Products, and Cat Litter & Litter Accessories), Pet Healthcare Products (Flea & Tick Products, Preventive Healthcare Products, First-Aid Products, Skin & Coat Health Products, and Joint & Mobility Products), Training & Behavioral Products (Training Pads, Training Aids, and Calming & Behavioral Products), and Other Pet Products), Pet Type, Store Format, Sales Channel, and By Geography
According to Stratistics MRC, the Global Pet Retail Market is accounted for $33.0 billion in 2026 and is expected to reach $53.4 billion by 2034 growing at a CAGR of 6.2% during the forecast period. Pet retail encompasses the sale of pet food, supplies, accessories, grooming products, healthcare items, and other pet-related merchandise through various retail channels. The market serves diverse pet types including dogs, cats, birds, fish, small mammals, reptiles, horses, and other pets through store formats including standalone specialty pet stores, pet store chains and franchise outlets, supermarkets and hypermarkets, mass merchandisers, warehouse clubs, farm and ranch stores, veterinary clinic-integrated retail stores, pet boutique and lifestyle stores, and other formats. Market Dynamics: Driver: Increasing pet ownership and humanization of pets The rising global pet population and the growing trend of treating pets as family members are primary drivers for the pet retail market. Pet owners are increasingly investing in premium nutrition, healthcare products, grooming supplies, accessories, and services for their companion animals, mirroring human consumer trends. The humanization of pets has led to greater willingness to spend on high-quality products. As pet ownership increases across developed and developing regions, the addressable market for pet retail expands. Millennial and Gen Z pet owners, in particular, prioritize pet wellness and are willing to spend on premium products, sustaining strong demand across retail channels. Restraint: Intense price competition and margin pressure The highly competitive nature of the pet retail market and ongoing margin pressure represent a major restraint for the market. The rise of e-commerce and discount retailers has intensified price competition across pet product categories. Supermarkets, mass merchandisers, and online platforms offer competitive pricing, pressuring specialty retailers. Private label products offer lower-priced alternatives to branded products. Price transparency from online comparison shopping affects pricing strategies. These competitive pressures may limit profitability and market growth, particularly for smaller retailers with limited purchasing power and brand recognition. Opportunity: Expansion of premium and specialized product categories The growing demand for premium, natural, and specialized pet products presents significant opportunities for pet retail market expansion. Premium pet food with natural ingredients, grain-free formulas, and functional benefits is gaining market share. Specialized products including eco-friendly accessories, organic grooming products, and health supplements are expanding. Pet owners are increasingly seeking products that address specific health conditions, dietary needs, and lifestyle preferences. As product innovation continues and consumer preferences evolve, premium and specialized categories capture growing market share, expanding retail opportunities. Threat: Competition from e-commerce and direct-to-consumer brands The rapid growth of e-commerc
According to Stratistics MRC, the Global Pet Retail Market is accounted for $33.0 billion in 2026 and is expected to reach $53.4 billion by 2034 growing at a CAGR of 6.2% during the forecast period. Pet retail encompasses the sale of pet food, supplies, accessories, grooming products, healthcare items, and other pet-related merchandise through various retail channels. The market serves diverse pet types including dogs, cats, birds, fish, small mammals, reptiles, horses, and other pets through store formats including standalone specialty pet stores, pet store chains and franchise outlets, supermarkets and hypermarkets, mass merchandisers, warehouse clubs, farm and ranch stores, veterinary clinic-integrated retail stores, pet boutique and lifestyle stores, and other formats.
Market Dynamics:
Driver:
Increasing pet ownership and humanization of pets
The rising global pet population and the growing trend of treating pets as family members are primary drivers for the pet retail market. Pet owners are increasingly investing in premium nutrition, healthcare products, grooming supplies, accessories, and services for their companion animals, mirroring human consumer trends. The humanization of pets has led to greater willingness to spend on high-quality products. As pet ownership increases across developed and developing regions, the addressable market for pet retail expands. Millennial and Gen Z pet owners, in particular, prioritize pet wellness and are willing to spend on premium products, sustaining strong demand across retail channels.
Restraint:
Intense price competition and margin pressure
The highly competitive nature of the pet retail market and ongoing margin pressure represent a major restraint for the market. The rise of e-commerce and discount retailers has intensified price competition across pet product categories. Supermarkets, mass merchandisers, and online platforms offer competitive pricing, pressuring specialty retailers. Private label products offer lower-priced alternatives to branded products. Price transparency from online comparison shopping affects pricing strategies. These competitive pressures may limit profitability and market growth, particularly for smaller retailers with limited purchasing power and brand recognition.
Opportunity:
Expansion of premium and specialized product categories
The growing demand for premium, natural, and specialized pet products presents significant opportunities for pet retail market expansion. Premium pet food with natural ingredients, grain-free formulas, and functional benefits is gaining market share. Specialized products including eco-friendly accessories, organic grooming products, and health supplements are expanding. Pet owners are increasingly seeking products that address specific health conditions, dietary needs, and lifestyle preferences. As product innovation continues and consumer preferences evolve, premium and specialized categories capture growing market share, expanding retail opportunities.
Threat:
Competition from e-commerce and direct-to-consumer brands
The rapid growth of e-commerce platforms and direct-to-consumer pet brands poses significant threats to traditional brick-and-mortar pet retail. Online retailers offer convenience, competitive pricing, subscription services, and home delivery that appeal to consumers. Direct-to-consumer brands are building customer loyalty through subscription models and personalized experiences. The convenience of online shopping for bulky pet products including food and litter is driving channel shift. Traditional retailers must invest in omnichannel capabilities and unique in-store experiences to remain competitive. This competition may accelerate consolidation in the pet retail sector.
Covid-19 Impact:
The COVID-19 pandemic had a significant impact on the pet retail market. Pet adoption surged during lockdowns, expanding the pet-owning population and creating new customers. Consumers increased spending on pet products during stay-at-home periods. E-commerce pet retail sales grew dramatically as consumers shifted to online purchasing. Essential pet retail remained operational during lockdowns. Post-pandemic, elevated pet ownership levels and continued spending on pet products have sustained demand, with omnichannel retail becoming standard. The crisis accelerated pet retail digital transformation and reinforced the essential nature of pet products.
The Dogs segment is expected to be the largest during the forecast period
The Dogs segment is expected to account for the largest market share during the forecast period, driven by the high dog ownership rates globally, extensive product categories for dogs, and high per-pet spending on dog products. Dogs are the most common companion animals in most regions, creating substantial demand for dog food, accessories, grooming products, healthcare items, and other merchandise. The segment benefits from extensive product innovation and established retail infrastructure. Dog owners consistently invest in premium nutrition, grooming, and accessories for their pets. As dog ownership continues growing, dogs maintain the largest pet type segment share throughout the forecast period.
The Pet Boutique and Lifestyle Stores segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Pet Boutique and Lifestyle Stores segment is predicted to witness the highest growth rate, fueled by increasing consumer demand for unique, premium, and specialized pet products, the growth of pet lifestyle culture, and expanding boutique retail concepts. Pet boutique stores offer curated selections, exclusive brands, personalized service, and aesthetically pleasing shopping environments. The segment benefits from the premiumization trend and consumer willingness to pay for distinctive products. Growing pet humanization and lifestyle branding support boutique store growth. As pet owners seek unique products and experiences, pet boutique stores deliver the fastest store format growth.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, supported by high pet ownership rates, strong spending on pet products, and established retail infrastructure. The United States has one of the highest pet ownership rates globally, with substantial household spending on pet care and products. High awareness of pet health, wellness, and premium products drives spending. Established pet retail chains, specialty stores, and e-commerce channels provide extensive product accessibility. Premiumization trend and pet humanization continue supporting market growth. With high pet spending and established retail infrastructure, North America maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by rising pet ownership, increasing disposable incomes, growing urbanization, and expanding modern retail infrastructure across countries including China, India, Japan, and Southeast Asia. The region's rapidly growing pet population and expanding middle class create substantial demand for pet products. Modern retail formats including pet specialty stores and e-commerce platforms are expanding. Growing awareness of pet health, wellness, and premium products supports adoption. As pet ownership grows and retail infrastructure develops, Asia Pacific delivers the fastest pet retail market growth globally.
Key players in the market
Some of the key players in Pet Retail Market include PetSmart LLC, Petco Health and Wellness Company, Inc., Chewy, Inc., Pet Supplies Plus, Pet Supermarket, Tractor Supply Company, Pet Valu Holdings Ltd., Fressnapf Tiernahrungs GmbH, Musti Group Oyj, Jollyes Retail Group Limited, Petland, Inc., Pet Lovers Centre Pte. Ltd., Arcaplanet S.p.A., Maxi Zoo, Zooplus SE, Pets at Home Group Plc, Walmart Inc., and Amazon.com, Inc.
Key Developments:
In June 2026, Chewy finalized its strategic acquisition of veterinary care provider Modern Animal, expanding its Chewy Vet Care (CVC) brick-and-mortar footprint while integrating AI-driven customer service tools into its mobile application.
In April 2026, Chewy signed a definitive agreement to acquire Modern Animal to bolster its physical clinic footprint and complement its existing digital telehealth and pharmacy segments.
In February 2026, Petco expanded its proprietary "Well & Good" health brand into functional wellness categories, introducing hip-and-joint and liver-care product lines to capture growing demand for preventive pet healthcare.
Product Categories Covered:
• Pet Food and Nutrition
• Pet Accessories and Supplies
• Pet Grooming and Hygiene Products
• Pet Healthcare Products
• Training and Behavioral Products
• Other Pet Products
Pet Types Covered:
• Dogs
• Cats
• Birds
• Fish
• Small Mammals
• Reptiles
• Horses
• Other Pets
Store Formats Covered:
• Standalone Specialty Pet Stores
• Pet Store Chains and Franchise Outlets
• Supermarkets and Hypermarkets
• Mass Merchandisers
• Warehouse Clubs
• Farm and Ranch Stores
• Veterinary Clinic-Integrated Retail Stores
• Pet Boutique and Lifestyle Stores
• Other Store Formats
Sales Channels Covered:
• Offline Retail
• Online Retail
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
e platforms and direct-to-consumer pet brands poses significant threats to traditional brick-and-mortar pet retail. Online retailers offer convenience, competitive pricing, subscription services, and home delivery that appeal to consumers. Direct-to-consumer brands are building customer loyalty through subscription models and personalized experiences. The convenience of online shopping for bulky pet products including food and litter is driving channel shift. Traditional retailers must invest in omnichannel capabilities and unique in-store experiences to remain competitive. This competition may accelerate consolidation in the pet retail sector. Covid-19 Impact: The COVID-19 pandemic had a significant impact on the pet retail market. Pet adoption surged during lockdowns, expanding the pet-owning population and creating new customers. Consumers increased spending on pet products during stay-at-home periods. E-commerce pet retail sales grew dramatically as consumers shifted to online purchasing. Essential pet retail remained operational during lockdowns. Post-pandemic, elevated pet ownership levels and continued spending on pet products have sustained demand, with omnichannel retail becoming standard. The crisis accelerated pet retail digital transformation and reinforced the essential nature of pet products. The Dogs segment is expected to be the largest during the forecast period The Dogs segment is expected to account for the largest market share during the forecast period, driven by the high dog ownership rates globally, extensive product categories for dogs, and high per-pet spending on dog products. Dogs are the most common companion animals in most regions, creating substantial demand for dog food, accessories, grooming products, healthcare items, and other merchandise. The segment benefits from extensive product innovation and established retail infrastructure. Dog owners consistently invest in premium nutrition, grooming, and accessories for their pets. As dog ownership continues growing, dogs maintain the largest pet type segment share throughout the forecast period. The Pet Boutique and Lifestyle Stores segment is expected to have the highest CAGR during the forecast period Over the forecast period, the Pet Boutique and Lifestyle Stores segment is predicted to witness the highest growth rate, fueled by increasing consumer demand for unique, premium, and specialized pet products, the growth of pet lifestyle culture, and expanding boutique retail concepts. Pet boutique stores offer curated selections, exclusive brands, personalized service, and aesthetically pleasing shopping environments. The segment benefits from the premiumization trend and consumer willingness to pay for distinctive products. Growing pet humanization and lifestyle branding support boutique store growth. As pet owners seek unique products and experiences, pet boutique stores deliver the fastest store format growth. Region with largest share: During the forecast period, the North America region is expected to hold the largest market share, supported by high pet ownership rates, strong spending on pet products, and established retail infrastructure. The United States has one of the highest pet ownership rates globally, with substantial household spending on pet care and products. High awareness of pet health, wellness, and premium products drives spending. Established pet retail chains, specialty stores, and e-commerce channels provide extensive product accessibility. Premiumization trend and pet humanization continue supporting market growth. With high pet spending and established retail infrastructure, North America maintains its dominant market position. Region with highest CAGR: Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by rising pet ownership, increasing disposable incomes, growing urbanization, and expanding modern retail infrastructure across countries including China, India, Japan, and Southeast Asia. The region's rapidly growing pet population and expanding middle class create substantial demand for pet products. Modern retail formats including pet specialty stores and e-commerce platforms are expanding. Growing awareness of pet health, wellness, and premium products supports adoption. As pet ownership grows and retail infrastructure develops, Asia Pacific delivers the fastest pet retail market growth globally. Key players in the market Some of the key players in Pet Retail Market include PetSmart LLC, Petco Health and Wellness Company, Inc., Chewy, Inc., Pet Supplies Plus, Pet Supermarket, Tractor Supply Company, Pet Valu Holdings Ltd., Fressnapf Tiernahrungs GmbH, Musti Group Oyj, Jollyes Retail Group Limited, Petland, Inc., Pet Lovers Centre Pte. Ltd., Arcaplanet S.p.A., Maxi Zoo, Zooplus SE, Pets at Home Group Plc, Walmart Inc., and Amazon.com, Inc. Key Developments: In June 2026, Chewy finalized its strategic acquisition of veterinary care provider Modern Animal, expanding its Chewy Vet Care (CVC) brick-and-mortar footprint while integrating AI-driven customer service tools into its mobile application. In April 2026, Chewy signed a definitive agreement to acquire Modern Animal to bolster its physical clinic footprint and complement its existing digital telehealth and pharmacy segments. In February 2026, Petco expanded its proprietary Well & Good health brand into functional wellness categories, introducing hip-and-joint and liver-care product lines to capture growing demand for preventive pet healthcare. Product Categories Covered: • Pet Food and Nutrition • Pet Accessories and Supplies • Pet Grooming and Hygiene Products • Pet Healthcare Products • Training and Behavioral Products • Other Pet Products Pet Types Covered: • Dogs • Cats • Birds • Fish • Small Mammals • Reptiles • Horses • Other Pets Store Formats Covered: • Standalone Specialty Pet Stores • Pet Store Chains and Franchise Outlets • Supermarkets and Hypermarkets • Mass Merchandisers • Warehouse Clubs • Farm and Ranch Stores • Veterinary Clinic-Integrated Retail Stores • Pet Boutique and Lifestyle Stores • Other Store Formats Sales Channels Covered: • Offline Retail • Online Retail Regions Covered: • North America o United States o Canada o Mexico • Europe o United Kingdom o Germany o France o Italy o Spain o Netherlands o Belgium o Sweden o Switzerland o Poland o Rest of Europe • Asia Pacific o China o Japan o India o South Korea o Australia o Indonesia o Thailand o Malaysia o Singapore o Vietnam o Rest of Asia Pacific • South America o Brazil o Argentina o Colombia o Chile o Peru o Rest of South America • Rest of the World (RoW) o Middle East ? Saudi Arabia ? United Arab Emirates ? Qatar ? Israel ? Rest of Middle East o Africa ? South Africa ? Egypt ? Morocco ? Rest of Africa What our report offers: - Market share assessments for the regional and country-level segments - Strategic recommendations for the new entrants - Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034 - Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations) - Strategic recommendations in key business segments based on the market estimations - Competitive landscaping mapping the key common trends - Company profiling with detailed strategies, financials, and recent developments - Supply chain trends mapping the latest technological advancements Free Customization Offerings: All the customers of this report will be entitled to receive one of the following free customization options: • Company Profiling o Comprehensive profiling of additional market players (up to 3) o SWOT Analysis of key players (up to 3) • Regional Segmentation o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check) • Competitive Benchmarking o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Pet Retail Market, By Product Category
5.1 Pet Food and Nutrition
5.1.1 Dry Food
5.1.2 Wet Food
5.1.3 Treats and Snacks
5.1.4 Pet Supplements and Nutraceuticals
5.2 Pet Accessories and Supplies
5.2.1 Collars, Harnesses, and Leashes
5.2.2 Beds and Bedding
5.2.3 Bowls and Feeders
5.2.4 Toys and Enrichment Products
5.2.5 Crates, Cages, and Carriers
5.2.6 Pet Apparel and Footwear
5.3 Pet Grooming and Hygiene Products
5.3.1 Shampoos and Conditioners
5.3.2 Brushes, Combs, and Grooming Tools
5.3.3 Dental Care Products
5.3.4 Nail Care Products
5.3.5 Waste Management Products
5.3.6 Cat Litter and Litter Accessories
5.4 Pet Healthcare Products
5.4.1 Flea and Tick Products
5.4.2 Preventive Healthcare Products
5.4.3 First-Aid Products
5.4.4 Skin and Coat Health Products
5.4.5 Joint and Mobility Products
5.5 Training and Behavioral Products
5.5.1 Training Pads
5.5.2 Training Aids
5.5.3 Calming and Behavioral Products
5.6 Other Pet Products
6 Global Pet Retail Market, By Pet Type
6.1 Dogs
6.2 Cats
6.3 Birds
6.4 Fish
6.5 Small Mammals
6.6 Reptiles
6.7 Horses
6.8 Other Pets
7 Global Pet Retail Market, By Store Format
7.1 Standalone Specialty Pet Stores
7.2 Pet Store Chains and Franchise Outlets
7.3 Supermarkets and Hypermarkets
7.4 Mass Merchandisers
7.5 Warehouse Clubs
7.6 Farm and Ranch Stores
7.7 Veterinary Clinic-Integrated Retail Stores
7.8 Pet Boutique and Lifestyle Stores
7.9 Other Store Formats
8 Global Pet Retail Market, By Sales Channel
8.1 Offline Retail
8.2 Online Retail
8.2.1 Online Marketplaces
8.2.2 Brand-Owned E-Commerce Websites
8.2.3 Online Specialty Pet Stores
9 Global Pet Retail Market, By Geography
9.1 North America
9.1.1 United States
9.1.2 Canada
9.1.3 Mexico
9.2 Europe
9.2.1 United Kingdom
9.2.2 Germany
9.2.3 France
9.2.4 Italy
9.2.5 Spain
9.2.6 Netherlands
9.2.7 Belgium
9.2.8 Sweden
9.2.9 Switzerland
9.2.10 Poland
9.2.11 Rest of Europe
9.3 Asia Pacific
9.3.1 China
9.3.2 Japan
9.3.3 India
9.3.4 South Korea
9.3.5 Australia
9.3.6 Indonesia
9.3.7 Thailand
9.3.8 Malaysia
9.3.9 Singapore
9.3.10 Vietnam
9.3.11 Rest of Asia Pacific
9.4 South America
9.4.1 Brazil
9.4.2 Argentina
9.4.3 Colombia
9.4.4 Chile
9.4.5 Peru
9.4.6 Rest of South America
9.5 Rest of the World (RoW)
9.5.1 Middle East
9.5.1.1 Saudi Arabia
9.5.1.2 United Arab Emirates
9.5.1.3 Qatar
9.5.1.4 Israel
9.5.1.5 Rest of Middle East
9.5.2 Africa
9.5.2.1 South Africa
9.5.2.2 Egypt
9.5.2.3 Morocco
9.5.2.4 Rest of Africa
10 Strategic Market Intelligence
10.1 Industry Value Network and Supply Chain Assessment
10.2 White-Space and Opportunity Mapping
10.3 Product Evolution and Market Life Cycle Analysis
10.4 Channel, Distributor, and Go-to-Market Assessment
11 Industry Developments and Strategic Initiatives
11.1 Mergers and Acquisitions
11.2 Partnerships, Alliances, and Joint Ventures
11.3 New Product Launches and Certifications
11.4 Capacity Expansion and Investments
11.5 Other Strategic Initiatives
12 Company Profiles
12.1 PetSmart LLC
12.2 Petco Health and Wellness Company, Inc.
12.3 Chewy, Inc.
12.4 Pet Supplies Plus
12.5 Pet Supermarket
12.6 Tractor Supply Company
12.7 Pet Valu Holdings Ltd.
12.8 Fressnapf Tiernahrungs GmbH
12.9 Musti Group Oyj
12.10 Jollyes Retail Group Limited
12.11 Petland, Inc.
12.12 Pet Lovers Centre Pte. Ltd.
12.13 Arcaplanet S.p.A.
12.14 Maxi Zoo
12.15 Zooplus SE
12.16 Pets at Home Group Plc
12.17 Walmart Inc.
12.18 Amazon.com, Inc.
List of Tables
1 Global Pet Retail Market Outlook, By Region (2023–2034) ($MN)
2 Global Pet Retail Market Outlook, By Product Category (2023–2034) ($MN)
3 Global Pet Retail Market Outlook, By Pet Food and Nutrition (2023–2034) ($MN)
4 Global Pet Retail Market Outlook, By Dry Food (2023–2034) ($MN)
5 Global Pet Retail Market Outlook, By Wet Food (2023–2034) ($MN)
6 Global Pet Retail Market Outlook, By Treats and Snacks (2023–2034) ($MN)
7 Global Pet Retail Market Outlook, By Pet Supplements and Nutraceuticals (2023–2034) ($MN)
8 Global Pet Retail Market Outlook, By Pet Accessories and Supplies (2023–2034) ($MN)
9 Global Pet Retail Market Outlook, By Collars, Harnesses, and Leashes (2023–2034) ($MN)
10 Global Pet Retail Market Outlook, By Beds and Bedding (2023–2034) ($MN)
11 Global Pet Retail Market Outlook, By Bowls and Feeders (2023–2034) ($MN)
12 Global Pet Retail Market Outlook, By Toys and Enrichment Products (2023–2034) ($MN)
13 Global Pet Retail Market Outlook, By Crates, Cages, and Carriers (2023–2034) ($MN)
14 Global Pet Retail Market Outlook, By Pet Apparel and Footwear (2023–2034) ($MN)
15 Global Pet Retail Market Outlook, By Pet Grooming and Hygiene Products (2023–2034) ($MN)
16 Global Pet Retail Market Outlook, By Shampoos and Conditioners (2023–2034) ($MN)
17 Global Pet Retail Market Outlook, By Brushes, Combs, and Grooming Tools (2023–2034) ($MN)
18 Global Pet Retail Market Outlook, By Dental Care Products (2023–2034) ($MN)
19 Global Pet Retail Market Outlook, By Nail Care Products (2023–2034) ($MN)
20 Global Pet Retail Market Outlook, By Waste Management Products (2023–2034) ($MN)
21 Global Pet Retail Market Outlook, By Cat Litter and Litter Accessories (2023–2034) ($MN)
22 Global Pet Retail Market Outlook, By Pet Healthcare Products (2023–2034) ($MN)
23 Global Pet Retail Market Outlook, By Flea and Tick Products (2023–2034) ($MN)
24 Global Pet Retail Market Outlook, By Preventive Healthcare Products (2023–2034) ($MN)
25 Global Pet Retail Market Outlook, By First-Aid Products (2023–2034) ($MN)
26 Global Pet Retail Market Outlook, By Skin and Coat Health Products (2023–2034) ($MN)
27 Global Pet Retail Market Outlook, By Joint and Mobility Products (2023–2034) ($MN)
28 Global Pet Retail Market Outlook, By Training and Behavioral Products (2023–2034) ($MN)
29 Global Pet Retail Market Outlook, By Training Pads (2023–2034) ($MN)
30 Global Pet Retail Market Outlook, By Training Aids (2023–2034) ($MN)
31 Global Pet Retail Market Outlook, By Calming and Behavioral Products (2023–2034) ($MN)
32 Global Pet Retail Market Outlook, By Other Pet Products (2023–2034) ($MN)
33 Global Pet Retail Market Outlook, By Pet Type (2023–2034) ($MN)
34 Global Pet Retail Market Outlook, By Dogs (2023–2034) ($MN)
35 Global Pet Retail Market Outlook, By Cats (2023–2034) ($MN)
36 Global Pet Retail Market Outlook, By Birds (2023–2034) ($MN)
37 Global Pet Retail Market Outlook, By Fish (2023–2034) ($MN)
38 Global Pet Retail Market Outlook, By Small Mammals (2023–2034) ($MN)
39 Global Pet Retail Market Outlook, By Reptiles (2023–2034) ($MN)
40 Global Pet Retail Market Outlook, By Horses (2023–2034) ($MN)
41 Global Pet Retail Market Outlook, By Other Pets (2023–2034) ($MN)
42 Global Pet Retail Market Outlook, By Store Format (2023–2034) ($MN)
43 Global Pet Retail Market Outlook, By Standalone Specialty Pet Stores (2023–2034) ($MN)
44 Global Pet Retail Market Outlook, By Pet Store Chains and Franchise Outlets (2023–2034) ($MN)
45 Global Pet Retail Market Outlook, By Supermarkets and Hypermarkets (2023–2034) ($MN)
46 Global Pet Retail Market Outlook, By Mass Merchandisers (2023–2034) ($MN)
47 Global Pet Retail Market Outlook, By Warehouse Clubs (2023–2034) ($MN)
48 Global Pet Retail Market Outlook, By Farm and Ranch Stores (2023–2034) ($MN)
49 Global Pet Retail Market Outlook, By Veterinary Clinic-Integrated Retail Stores (2023–2034) ($MN)
50 Global Pet Retail Market Outlook, By Pet Boutique and Lifestyle Stores (2023–2034) ($MN)
51 Global Pet Retail Market Outlook, By Other Store Formats (2023–2034) ($MN)
52 Global Pet Retail Market Outlook, By Sales Channel (2023–2034) ($MN)
53 Global Pet Retail Market Outlook, By Offline Retail (2023–2034) ($MN)
54 Global Pet Retail Market Outlook, By Online Retail (2023–2034) ($MN)
55 Global Pet Retail Market Outlook, By Online Marketplaces (2023–2034) ($MN)
56 Global Pet Retail Market Outlook, By Brand-Owned E-Commerce Websites (2023–2034) ($MN)
57 Global Pet Retail Market Outlook, By Online Specialty Pet Stores (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
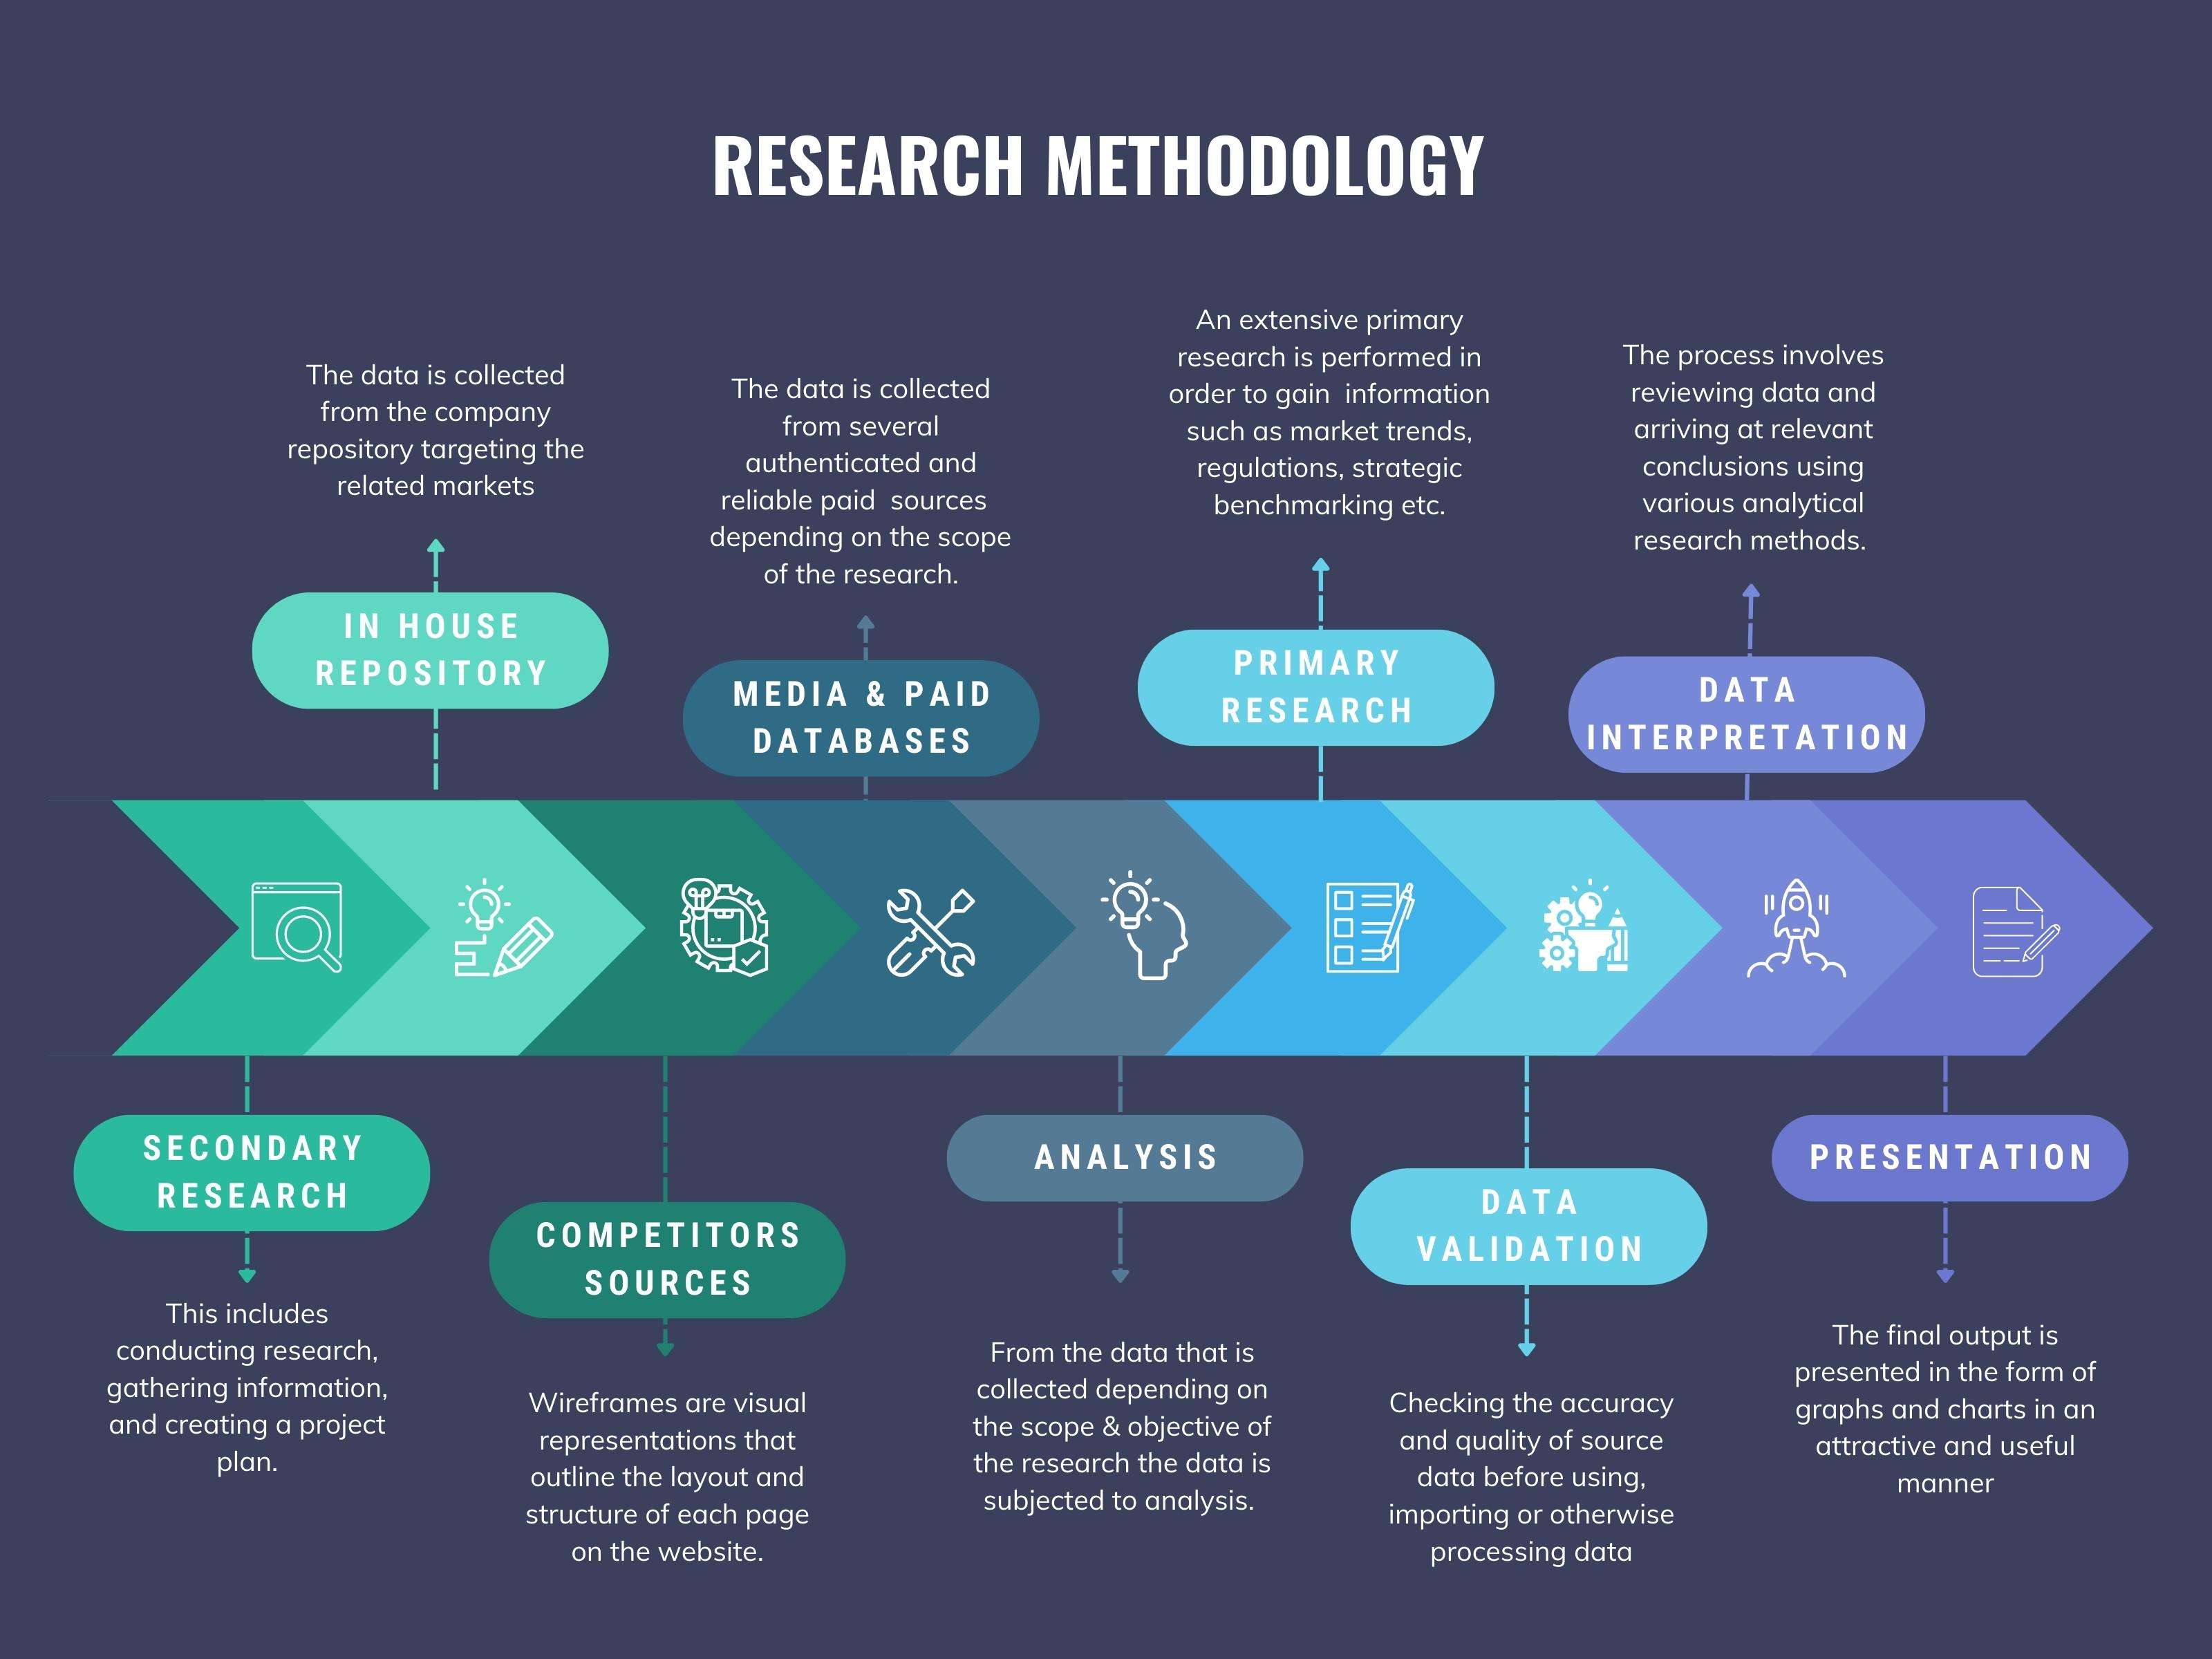
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.