Semiconductor Thermal Management Materials Market
Semiconductor Thermal Management Materials Market Forecasts to 2034 – Global Analysis By Material Type (Thermal Interface Materials, Thermal Adhesives, Thermal Greases, Thermal Pads, Phase Change Materials and Other Material Types), Component, Packaging Type, Thermal Management Function, End User and Geography
According to Stratistics MRC, the Global Semiconductor Thermal Management Materials Market is accounted for $2.6 billion in 2026 and is expected to reach $5.2 billion by 2034 growing at a CAGR of 9.1% during the forecast period. Semiconductor Thermal Management Materials are advanced materials used to dissipate, spread, insulate, and control heat generated by semiconductor devices and integrated circuits. These materials include thermal interface materials, heat spreaders, thermal adhesives, phase-change materials, graphite-based materials, ceramics, metal-based thermal solutions, and advanced composites. They are used across processors, GPUs, AI accelerators, power semiconductors, memory devices, and advanced semiconductor packages where increasing power density creates significant thermal challenges. Effective thermal management helps maintain device performance, reliability, and operating stability while reducing temperature-related degradation. Demand is supported by high-performance computing, artificial intelligence, 5G infrastructure, electric vehicles, and increasingly compact electronic architectures. Advanced materials increasingly focus on higher thermal conductivity, lower thermal resistance, electrical insulation where required, lightweight construction, and compatibility with advanced packaging. Emerging developments include diamond-based thermal materials, graphene-enhanced composites, advanced ceramic substrates, and next-generation interface materials.
Market Dynamics
Driver:
Growing semiconductor power densities and thermal challenges
Rapidly increasing power densities in advanced processors, AI accelerators, and high-performance computing devices are creating severe thermal management challenges that demand increasingly sophisticated thermal management materials with superior conductivity and reliability. Continued scaling at advanced nodes has pushed thermal design power beyond 500 watts for flagship processors, requiring thermal interface materials with thermal conductivity exceeding 10 W/mK to maintain operating temperatures within safe limits. The proliferation of AI accelerators, high-bandwidth memory stacks, and 2.5D/3D packaging architectures is concentrating heat generation in smaller footprints, driving demand for advanced thermal solutions. Growing adoption of wide-bandgap power semiconductors in electric vehicles and industrial applications creates additional thermal management requirements. Regulatory and reliability requirements across automotive and data center applications demand thermal materials with proven long-term stability.
Restraint:
High material costs and application complexity
High costs of advanced thermal interface materials, particularly those incorporating silver, diamond, or other high-performance fillers, present significant barriers to widespread adoption in cost-sensitive applications. Application complexity of thermal management materials, including precise dispensing, controlled bond line thickness, and void-free interfaces, demands specialized equipment and process expertise that increases total cost of ownership. Thermal cycling reliability challenges and pump-out phenomena in high-power applications limit material longevity and require ongoing formulation innovation. Limited availability of qualified suppliers for critical thermal materials constrains supply chain flexibility. Trade-offs between thermal performance, mechanical properties, and manufacturing compatibility complicate material selection decisions.
Opportunity:
Advanced packaging and heterogeneous integration
Growth in advanced packaging including 2.5D interposers, 3D stacking, and chiplet architectures creates substantial opportunities for thermal management materials designed for these emerging form factors. Development of materials compatible with hybrid bonding and TSV processes enables new thermal management approaches. Expansion of AI data center infrastructure drives demand for high-performance thermal solutions at both chip and system levels. Growing electrification of automotive powertrains creates significant opportunities for thermal materials in power semiconductor packaging. Sustainable thermal materials with reduced environmental impact present differentiation opportunities.
Threat:
Competition from alternative cooling technologies
Competition from alternative cooling technologies including direct liquid cooling, immersion cooling, and microfluidic cooling may limit growth in certain high-power applications. Economic cyclicality in semiconductor markets affects thermal material demand and investment. Technology transitions may render existing formulations obsolete, requiring continuous innovation investment. Geopolitical tensions and trade restrictions may disrupt supply chains for critical thermal material ingredients. Consolidation among semiconductor manufacturers increases buyer concentration and pricing pressure.
Covid-19 Impact:
The COVID-19 pandemic disrupted semiconductor supply chains and highlighted the critical importance of thermal management in maintaining device reliability and performance. Demand for computing and communications equipment surged during the pandemic, driving increased thermal material consumption. The post-pandemic period has witnessed sustained investment in advanced packaging and high-performance computing, supporting thermal material demand growth. Supply chain resilience initiatives have increased focus on regional thermal material production. Growing focus on AI and data center infrastructure continues driving market expansion.
The thermal interface materials segment is expected to be the largest during the forecast period
The thermal interface materials segment is expected to account for the largest market share during the forecast period as TIMs represent the most critical material category for managing heat transfer between semiconductor dies and heat spreaders. Growing power densities across processors, GPUs, and AI accelerators drive sustained demand for high-performance thermal interface materials. Advances in TIM formulations enable improved thermal conductivity while maintaining processability and reliability. Established supply relationships and application expertise support segment leadership. Thermal interface materials are essential for all high-power semiconductor packaging applications.
The advanced 2.5D and 3D packages segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the advanced 2.5D and 3D packages segment is predicted to witness the highest growth rate driven by increasing adoption of heterogeneous integration for AI, high-performance computing, and high-bandwidth memory applications. These advanced packages create unique thermal challenges requiring innovative materials with superior conductivity and compatibility with new packaging processes. Growing investment in chiplet architectures and hybrid bonding accelerates demand for thermal materials optimized for these applications. Development of materials compatible with fine-pitch and high-density interconnect requirements supports segment growth. Advanced packaging is increasingly central to semiconductor performance scaling.
Region with largest share:
During the forecast period, the Asia Pacific region is expected to hold the largest market share owing to the dominant semiconductor manufacturing and packaging base in Taiwan, South Korea, Japan, and China. The region hosts the world's largest foundries, memory manufacturers, and OSAT providers with extensive thermal material consumption. Major semiconductor manufacturers drive substantial demand for advanced thermal management solutions. Government support for semiconductor manufacturing reinforces regional market leadership. Continued capacity expansion across the region drives thermal material demand growth.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR driven by continued semiconductor capacity expansion and advanced packaging adoption across the region. Taiwan and South Korea are expanding advanced packaging capacity for AI and HPC applications, driving demand for high-performance thermal materials. China is investing in domestic semiconductor capabilities, creating substantial new demand. Growing investment in automotive and industrial semiconductors accelerates thermal material consumption. Regional supply chain development supports market growth.
Key players in the market
Some of the key players in the Semiconductor Thermal Management Materials Market include Henkel AG & Co. KGaA, Dow Inc., Momentive Performance Materials Inc., 3M Company, Laird Performance Materials, Parker Hannifin Corporation, H.B. Fuller Company, Henry Company, Indium Corporation, Shin-Etsu Chemical Co., Ltd., Fujipoly, Denka Company Limited, Panasonic Industry Co., Ltd., AI Technology, Inc., and LORD Corporation.
Key Developments:
In September 2026, Henkel AG & Co. KGaA introduced a new generation of thermal interface materials featuring thermal conductivity exceeding 15 W/mK for advanced AI accelerator packaging. The new formulations are specifically engineered to address the extreme thermal challenges of 2.5D and 3D packages used in data center AI infrastructure.
In June 2026, Indium Corporation launched a novel phase change material designed for high-power processor applications requiring stable thermal performance across wide temperature ranges. The material incorporates a proprietary formulation that maintains consistent thermal conductivity through multiple thermal cycles without pump-out degradation.
In December 2025, Laird Performance Materials introduced a comprehensive thermal management solution combining thermal interface materials with integrated heat spreading components for AI accelerator modules. The solution features a co-designed approach that optimizes thermal performance across the entire package stack from die to heat sink.
In September 2025, Shin-Etsu Chemical Co., Ltd. launched a new line of high-performance thermal greases featuring improved thermal conductivity and reduced pump-out characteristics for high-power semiconductor applications. The products incorporate advanced filler technology that maintains stable thermal performance under repeated thermal cycling.
Material Types Covered:
• Thermal Interface Materials
• Thermal Adhesives
• Thermal Greases
• Thermal Pads
• Phase Change Materials
• Other Material Types
Components Covered:
• Processors
• Memory Devices
• Power Semiconductors
• RF Semiconductors
• Optoelectronic Devices
• Other Components
Packaging Types Covered:
• Flip-Chip Packages
• Ball Grid Array Packages
• Chip-Scale Packages
• Multi-Chip Packages
• Advanced 2.5D & 3D Packages
• Other Packaging Types
Thermal Management Functions Covered:
• Heat Spreading
• Heat Dissipation
• Thermal Insulation
• Temperature Stabilization
• Thermal Shock Protection
• Other Thermal Management Functions
End Users Covered:
• Semiconductor Foundries
• Integrated Device Manufacturers
• Outsourced Semiconductor Assembly & Test Providers
• Electronics Manufacturers
• Automotive Semiconductor Suppliers
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Semiconductor Thermal Management Materials Market, By Material Type
5.1 Thermal Interface Materials
5.2 Thermal Adhesives
5.3 Thermal Greases
5.4 Thermal Pads
5.5 Phase Change Materials
5.6 Other Material Types
6 Global Semiconductor Thermal Management Materials Market, By Component
6.1 Processors
6.2 Memory Devices
6.3 Power Semiconductors
6.4 RF Semiconductors
6.5 Optoelectronic Devices
6.6 Other Components
7 Global Semiconductor Thermal Management Materials Market, By Packaging Type
7.1 Flip-Chip Packages
7.2 Ball Grid Array Packages
7.3 Chip-Scale Packages
7.4 Multi-Chip Packages
7.5 Advanced 2.5D & 3D Packages
7.6 Other Packaging Types
8 Global Semiconductor Thermal Management Materials Market, By Thermal Management Function
8.1 Heat Spreading
8.2 Heat Dissipation
8.3 Thermal Insulation
8.4 Temperature Stabilization
8.5 Thermal Shock Protection
8.6 Other Thermal Management Functions
9 Global Semiconductor Thermal Management Materials Market, By End User
9.1 Semiconductor Foundries
9.2 Integrated Device Manufacturers
9.3 Outsourced Semiconductor Assembly & Test Providers
9.4 Electronics Manufacturers
9.5 Automotive Semiconductor Suppliers
9.6 Other End Users
10 Global Semiconductor Thermal Management Materials Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Henkel AG & Co. KGaA
13.2 Dow Inc.
13.3 Momentive Performance Materials Inc.
13.4 3M Company
13.5 Laird Performance Materials
13.6 Parker Hannifin Corporation
13.7 H.B. Fuller Company
13.8 Henry Company
13.9 Indium Corporation
13.10 Shin-Etsu Chemical Co., Ltd.
13.11 Fujipoly
13.12 Denka Company Limited
13.13 Panasonic Industry Co., Ltd.
13.14 AI Technology, Inc.
13.15 LORD Corporation
List of Tables
1 Global Semiconductor Thermal Management Materials Market Outlook, By Region (2023-2034) ($MN)
2 Global Semiconductor Thermal Management Materials Market, By Material Type (2023–2034) ($MN)
3 Global Semiconductor Thermal Management Materials Market, By Thermal Interface Materials (2023–2034) ($MN)
4 Global Semiconductor Thermal Management Materials Market, By Thermal Adhesives (2023–2034) ($MN)
5 Global Semiconductor Thermal Management Materials Market, By Thermal Greases (2023–2034) ($MN)
6 Global Semiconductor Thermal Management Materials Market, By Thermal Pads (2023–2034) ($MN)
7 Global Semiconductor Thermal Management Materials Market, By Phase Change Materials (2023–2034) ($MN)
8 Global Semiconductor Thermal Management Materials Market, By Other Material Types (2023–2034) ($MN)
9 Global Semiconductor Thermal Management Materials Market, By Component (2023–2034) ($MN)
10 Global Semiconductor Thermal Management Materials Market, By Processors (2023–2034) ($MN)
11 Global Semiconductor Thermal Management Materials Market, By Memory Devices (2023–2034) ($MN)
12 Global Semiconductor Thermal Management Materials Market, By Power Semiconductors (2023–2034) ($MN)
13 Global Semiconductor Thermal Management Materials Market, By RF Semiconductors (2023–2034) ($MN)
14 Global Semiconductor Thermal Management Materials Market, By Optoelectronic Devices (2023–2034) ($MN)
15 Global Semiconductor Thermal Management Materials Market, By Other Components (2023–2034) ($MN)
16 Global Semiconductor Thermal Management Materials Market, By Packaging Type (2023–2034) ($MN)
17 Global Semiconductor Thermal Management Materials Market, By Flip-Chip Packages (2023–2034) ($MN)
18 Global Semiconductor Thermal Management Materials Market, By Ball Grid Array Packages (2023–2034) ($MN)
19 Global Semiconductor Thermal Management Materials Market, By Chip-Scale Packages (2023–2034) ($MN)
20 Global Semiconductor Thermal Management Materials Market, By Multi-Chip Packages (2023–2034) ($MN)
21 Global Semiconductor Thermal Management Materials Market, By Advanced 2.5D & 3D Packages (2023–2034) ($MN)
22 Global Semiconductor Thermal Management Materials Market, By Other Packaging Types (2023–2034) ($MN)
23 Global Semiconductor Thermal Management Materials Market, By Thermal Management Function (2023–2034) ($MN)
24 Global Semiconductor Thermal Management Materials Market, By Heat Spreading (2023–2034) ($MN)
25 Global Semiconductor Thermal Management Materials Market, By Heat Dissipation (2023–2034) ($MN)
26 Global Semiconductor Thermal Management Materials Market, By Thermal Insulation (2023–2034) ($MN)
27 Global Semiconductor Thermal Management Materials Market, By Temperature Stabilization (2023–2034) ($MN)
28 Global Semiconductor Thermal Management Materials Market, By Thermal Shock Protection (2023–2034) ($MN)
29 Global Semiconductor Thermal Management Materials Market, By Other Thermal Management Functions (2023–2034) ($MN)
30 Global Semiconductor Thermal Management Materials Market, By End User (2023–2034) ($MN)
31 Global Semiconductor Thermal Management Materials Market, By Semiconductor Foundries (2023–2034) ($MN)
32 Global Semiconductor Thermal Management Materials Market, By Integrated Device Manufacturers (2023–2034) ($MN)
33 Global Semiconductor Thermal Management Materials Market, By Outsourced Semiconductor Assembly & Test Providers (2023–2034) ($MN)
34 Global Semiconductor Thermal Management Materials Market, By Electronics Manufacturers (2023–2034) ($MN)
35 Global Semiconductor Thermal Management Materials Market, By Automotive Semiconductor Suppliers (2023–2034) ($MN)
36 Global Semiconductor Thermal Management Materials Market, By Other End Users (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
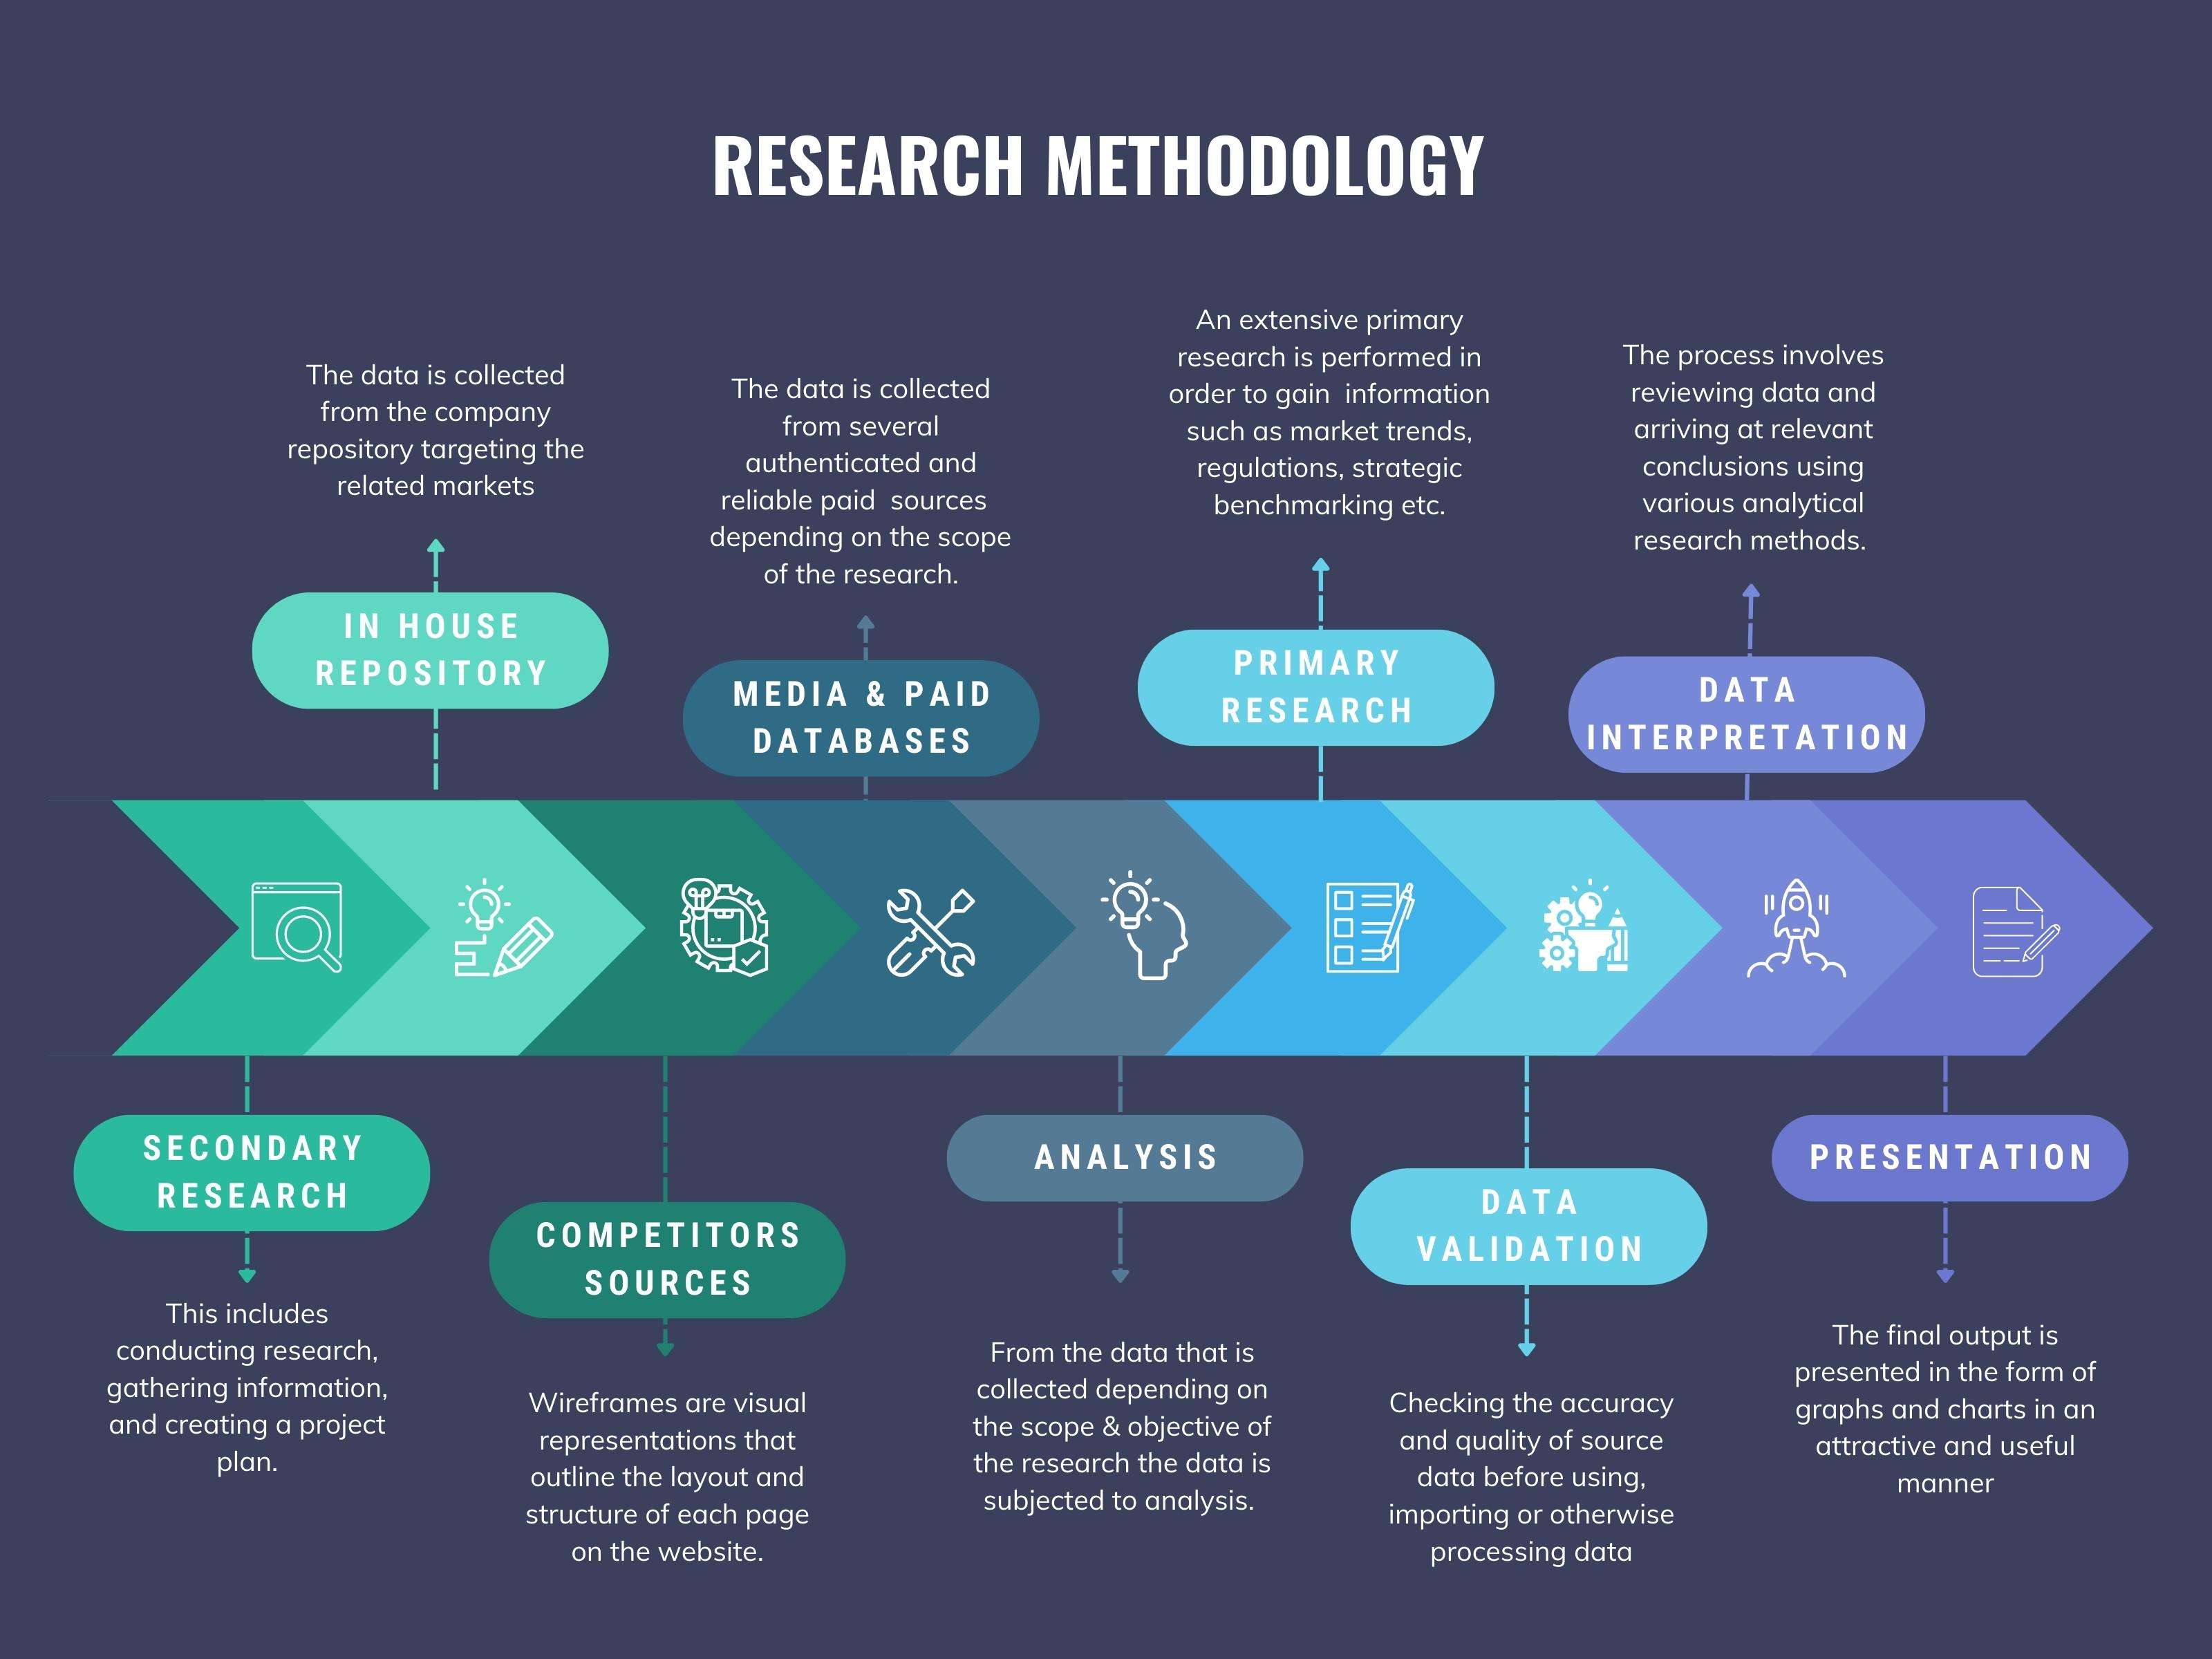
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.