Technical Ceramics Market
Technical Ceramics Market Forecasts To 2034 - Global Analysis By Material Type (Alumina (Al-O-), Zirconia (ZrO-), Silicon Carbide (SiC), Silicon Nitride (Si-N-), Aluminum Nitride (AlN), Boron Nitride (BN), Ferrite Ceramics, Titanate Ceramics, Mullite, Cordierite and Steatite), Product Type, Manufacturing Process, Function, Application, End-User and By Geography
According to Stratistics MRC, the Global Technical Ceramics Market is accounted for $20.3 billion in 2026 and is expected to reach $40.1 billion by 2034 growing at a CAGR of 8.9% during the forecast period. The Technical Ceramics Market encompasses the production and commercialization of advanced ceramic materials engineered to deliver superior mechanical strength, thermal stability, electrical insulation, corrosion resistance, and wear resistance. Unlike conventional ceramics, these materials are designed for high-performance applications across industries such as electronics, automotive, aerospace, healthcare, energy, industrial manufacturing, and defense. Common materials include alumina, zirconia, silicon carbide, silicon nitride, and aluminum nitride, each selected for specialized operational requirements. Growing demand for lightweight, durable, and high-temperature-resistant components, combined with continuous technological advancements and expanding industrial automation, is driving the adoption of technical ceramics worldwide.
Market Dynamics:
Driver:
Increasing Adoption in Automotive and Electric Vehicles
Growing production of automobiles, especially electric vehicles, is creating significant opportunities for the Technical Ceramics Market by increasing the need for durable and heat-resistant engineering materials. Technical ceramics are utilized in battery modules, electronic systems, braking assemblies, bearings, sensors, and ignition components because they deliver excellent mechanical strength and insulation properties. Automotive manufacturers are adopting these materials to improve vehicle efficiency, reduce overall weight, and ensure reliable operation in high-temperature environments. Rising investments in electric transportation, connected vehicles, and advanced automotive technologies continue to strengthen worldwide demand for technical ceramic solutions.
Restraint:
High Manufacturing and Processing Costs
Elevated production expenses remain a major challenge for the Technical Ceramics Market because advanced ceramic manufacturing involves costly materials, sophisticated processing technologies, controlled sintering conditions, and specialized fabrication techniques. Additional machining requirements increase overall production costs due to the exceptional hardness of technical ceramics. As a result, finished ceramic components typically carry higher prices than traditional engineering materials such as metals and plastics. Budget-conscious industries may delay or reduce adoption despite the long-term operational benefits offered by technical ceramics. Consequently, high manufacturing costs continue to restrict broader commercial penetration across multiple industrial sectors.
Opportunity:
Advancements in Biomedical and Healthcare Applications
Technological progress in medical science is creating valuable opportunities for the Technical Ceramics Market by expanding the use of advanced ceramic materials in healthcare applications. Their excellent compatibility with biological tissues, long-term durability, and resistance to corrosion make them suitable for implants, dental restorations, surgical tools, and diagnostic equipment. Rising healthcare expenditure, increasing life expectancy, and demand for high-quality medical devices continue to support wider adoption. Innovations in regenerative medicine, personalized implants, and advanced biomedical engineering are expected to increase the utilization of technical ceramics across the global healthcare sector.
Threat:
Rapid Technological Changes and Material Innovation
Fast-paced technological progress represents an important threat to the Technical Ceramics Market because emerging materials and advanced manufacturing techniques are expanding the range of competitive engineering solutions. Innovations in composite materials, nanotechnology, additive manufacturing, specialty alloys, and high-performance polymers continue to improve product capabilities while reducing production costs. Companies that cannot adapt quickly through research, process improvements, and product innovation may lose market opportunities. The increasing speed of technological change also demands ongoing investment in development activities, making sustained innovation essential for preserving long-term competitiveness in the global technical ceramics industry.
Covid-19 Impact:
The COVID-19 outbreak created short-term challenges for the Technical Ceramics Market by causing supply chain disruptions, slowing industrial production, and delaying investments in several end-use industries. Restrictions on transportation, workforce availability, and international trade affected the supply of raw materials and the manufacturing of ceramic components. Despite these setbacks, healthcare-related applications sustained stable demand due to increased requirements for medical equipment and diagnostic technologies. Following the easing of restrictions, expanding investments in semiconductor production, electric mobility, renewable energy, and industrial automation supported market recovery. The experience encouraged manufacturers to strengthen supply chain resilience and improve production flexibility.
The Alumina (Al₂O₃) segment is expected to be the largest during the forecast period
The Alumina (Al₂O₃) segment is expected to account for the largest market share during the forecast period, supported by its balanced combination of durability, electrical insulating capability, chemical resistance, hardness, thermal performance, and economical production. Alumina has become the preferred material for numerous engineering applications, including electronic substrates, industrial wear components, medical equipment, automotive parts, semiconductor manufacturing systems, and processing industries. Its ability to deliver dependable performance under demanding operating conditions while remaining commercially viable has encouraged extensive adoption. Strong demand from multiple end-use industries continues to maintain alumina as the dominant material in the technical ceramics market.
The Electronics & Semiconductor segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Electronics & Semiconductor segment is predicted to witness the highest growth rate. Rapid advancements in semiconductor production and electronic technologies are driving increased utilization of technical ceramics for critical applications requiring superior thermal management, electrical insulation, and structural reliability. Advanced ceramic materials are widely incorporated into semiconductor processing systems, electronic packaging, circuit substrates, sensors, and power devices because they perform efficiently under demanding operating conditions. Growing investments in artificial intelligence infrastructure, high-performance computing, consumer electronics, electric vehicles, and advanced communication networks continue to expand opportunities for technical ceramics, supporting strong growth throughout the forecast period.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, supported by a robust industrial ecosystem, large-scale electronics manufacturing, expanding semiconductor fabrication, and strong automotive production capabilities. Major economies including China, Japan, South Korea, and India continue to increase the use of technical ceramics across industrial machinery, healthcare, energy, and electronic applications. Rising investments in advanced manufacturing technologies, infrastructure expansion, and renewable energy development are further boosting regional demand. A broad manufacturing network and continuous technological advancement continue to sustain Asia-Pacific's dominance in the global market.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, Strong economic development, rapid expansion of electronics and semiconductor manufacturing, rising electric mobility adoption, and increasing industrial automation are driving greater consumption of advanced ceramic materials. Major economies such as China, India, Japan, South Korea, and emerging Southeast Asian countries continue to invest in high-value manufacturing, renewable energy, medical technologies, and aerospace production. Continuous technological advancements, favorable industrial policies, and expanding production capacity are expected to reinforce Asia-Pacific's position as the fastest-growing regional market for technical ceramics.
Key players in the market
Some of the key players in Technical Ceramics Market include Kyocera Corporation, CoorsTek, Inc., CeramTec GmbH, Morgan Advanced Materials plc, Saint-Gobain Ceramics, NGK Insulators, Ltd., Murata Manufacturing Co., Ltd., Rauschert GmbH, Superior Technical Ceramics Corporation, Ortech Advanced Ceramics, McDanel Advanced Ceramic Technologies LLC, Elan Technology, International Syalons (Newcastle) Ltd., Precision Ceramics USA, Blasch Precision Ceramics, Inc., Ceradyne, Inc. (3M), PI Ceramic GmbH and CTS Corporation.
Key Developments:
In March 2026, Kyocera Corporation and Cosmo Energy Holdings have entered into a strategic agreement to exchange solar and wind power. Announced in March 2024, the collaboration aims to address one of the biggest challenges in clean energy—its variable nature—by balancing different sources of generation.
In October 2025, Murata Manufacturing Co., Ltd. announces a significant collaboration with Cadence Design Systems, Inc., making product libraries directly accessible within Cadence’s leading Electronic Design Automation (EDA) tools. Murata’s selected inductor and capacitor products are now pre-installed in the latest versions of Cadence OrCAD X Capture™, Allegro X System Capture™ and AWR Design Environment™ (Microwave Office).
Material Types Covered:
• Alumina (Al₂O₃)
• Zirconia (ZrO₂)
• Silicon Carbide (SiC)
• Silicon Nitride (Si₃N₄)
• Aluminum Nitride (AlN)
• Boron Nitride (BN)
• Ferrite Ceramics
• Titanate Ceramics
• Mullite
• Cordierite
• Steatite
Product Types Covered:
• Monolithic Ceramics
• Ceramic Matrix Composites
• Porous Ceramics
Manufacturing Processs Covered:
• Dry Pressing
• Isostatic Pressing
• Injection Molding
• Extrusion
• Slip Casting
• Tape Casting
• Additive Manufacturing
• Other Manufacturing Processes
Functions Covered:
• Structural Ceramics
• Functional Ceramics
• Bioceramics
Applications Covered:
• Electronics & Semiconductor
• Medical Devices & Implants
• Automotive Components
• Aerospace Components
• Industrial Machinery
• Energy Systems
• Chemical Processing Equipment
• Defense & Ballistic Protection
• Cutting Tools
• Optical Components
• Filtration Systems
End Users Covered:
• Electronics & Semiconductor
• Automotive
• Aerospace & Defense
• Healthcare
• Industrial Manufacturing
• Energy & Power
• Chemical & Petrochemical
• Research & Academia
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Technical Ceramics Market, By Material Type
5.1 Alumina (Al₂O₃)
5.2 Zirconia (ZrO₂)
5.3 Silicon Carbide (SiC)
5.4 Silicon Nitride (Si₃N₄)
5.5 Aluminum Nitride (AlN)
5.6 Boron Nitride (BN)
5.7 Ferrite Ceramics
5.8 Titanate Ceramics
5.9 Mullite
5.10 Cordierite
5.11 Steatite
6 Global Technical Ceramics Market, By Product Type
6.1 Monolithic Ceramics
6.2 Ceramic Matrix Composites
6.3 Porous Ceramics
7 Global Technical Ceramics Market, By Manufacturing Process
7.1 Dry Pressing
7.2 Isostatic Pressing
7.3 Injection Molding
7.4 Extrusion
7.5 Slip Casting
7.6 Tape Casting
7.7 Additive Manufacturing
7.8 Other Manufacturing Processes
8 Global Technical Ceramics Market, By Function
8.1 Structural Ceramics
8.2 Functional Ceramics
8.3 Bioceramics
9 Global Technical Ceramics Market, By Application
9.1 Electronics & Semiconductor
9.2 Medical Devices & Implants
9.3 Automotive Components
9.4 Aerospace Components
9.5 Industrial Machinery
9.6 Energy Systems
9.7 Chemical Processing Equipment
9.8 Defense & Ballistic Protection
9.9 Cutting Tools
9.10 Optical Components
9.11 Filtration Systems
10 Global Technical Ceramics Market, By End-User
10.1 Electronics & Semiconductor
10.2 Automotive
10.3 Aerospace & Defense
10.4 Healthcare
10.5 Industrial Manufacturing
10.6 Energy & Power
10.7 Chemical & Petrochemical
10.8 Research & Academia
11 Global Technical Ceramics Market, By Geography
11.1 North America
11.1.1 United States
11.1.2 Canada
11.1.3 Mexico
11.2 Europe
11.2.1 United Kingdom
11.2.2 Germany
11.2.3 France
11.2.4 Italy
11.2.5 Spain
11.2.6 Netherlands
11.2.7 Belgium
11.2.8 Sweden
11.2.9 Switzerland
11.2.10 Poland
11.2.11 Rest of Europe
11.3 Asia Pacific
11.3.1 China
11.3.2 Japan
11.3.3 India
11.3.4 South Korea
11.3.5 Australia
11.3.6 Indonesia
11.3.7 Thailand
11.3.8 Malaysia
11.3.9 Singapore
11.3.10 Vietnam
11.3.11 Rest of Asia Pacific
11.4 South America
11.4.1 Brazil
11.4.2 Argentina
11.4.3 Colombia
11.4.4 Chile
11.4.5 Peru
11.4.6 Rest of South America
11.5 Rest of the World (RoW)
11.5.1 Middle East
11.5.1.1 Saudi Arabia
11.5.1.2 United Arab Emirates
11.5.1.3 Qatar
11.5.1.4 Israel
11.5.1.5 Rest of Middle East
11.5.2 Africa
11.5.2.1 South Africa
11.5.2.2 Egypt
11.5.2.3 Morocco
11.5.2.4 Rest of Africa
12 Strategic Market Intelligence
12.1 Industry Value Network and Supply Chain Assessment
12.2 White-Space and Opportunity Mapping
12.3 Product Evolution and Market Life Cycle Analysis
12.4 Channel, Distributor, and Go-to-Market Assessment
13 Industry Developments and Strategic Initiatives
13.1 Mergers and Acquisitions
13.2 Partnerships, Alliances, and Joint Ventures
13.3 New Product Launches and Certifications
13.4 Capacity Expansion and Investments
13.5 Other Strategic Initiatives
14 Company Profiles
14.1 Kyocera Corporation
14.2 CoorsTek, Inc.
14.3 CeramTec GmbH
14.4 Morgan Advanced Materials plc
14.5 Saint-Gobain Ceramics
14.6 NGK Insulators, Ltd.
14.7 Murata Manufacturing Co., Ltd.
14.8 Rauschert GmbH
14.9 Superior Technical Ceramics Corporation
14.10 Ortech Advanced Ceramics
14.11 McDanel Advanced Ceramic Technologies LLC
14.12 Elan Technology
14.13 International Syalons (Newcastle) Ltd.
14.14 Precision Ceramics USA
14.15 Blasch Precision Ceramics, Inc.
14.16 Ceradyne, Inc. (3M)
14.17 PI Ceramic GmbH
14.18 CTS Corporation
List of Tables
1 Global Technical Ceramics Market Outlook, By Region (2023-2034) ($MN)
2 Global Technical Ceramics Market Outlook, By Material Type (2023-2034) ($MN)
3 Global Technical Ceramics Market Outlook, By Alumina (Al₂O₃) (2023-2034) ($MN)
4 Global Technical Ceramics Market Outlook, By Zirconia (ZrO₂) (2023-2034) ($MN)
5 Global Technical Ceramics Market Outlook, By Silicon Carbide (SiC) (2023-2034) ($MN)
6 Global Technical Ceramics Market Outlook, By Silicon Nitride (Si₃N₄) (2023-2034) ($MN)
7 Global Technical Ceramics Market Outlook, By Aluminum Nitride (AlN) (2023-2034) ($MN)
8 Global Technical Ceramics Market Outlook, By Boron Nitride (BN) (2023-2034) ($MN)
9 Global Technical Ceramics Market Outlook, By Ferrite Ceramics (2023-2034) ($MN)
10 Global Technical Ceramics Market Outlook, By Titanate Ceramics (2023-2034) ($MN)
11 Global Technical Ceramics Market Outlook, By Mullite (2023-2034) ($MN)
12 Global Technical Ceramics Market Outlook, By Cordierite (2023-2034) ($MN)
13 Global Technical Ceramics Market Outlook, By Steatite (2023-2034) ($MN)
14 Global Technical Ceramics Market Outlook, By Product Type (2023-2034) ($MN)
15 Global Technical Ceramics Market Outlook, By Monolithic Ceramics (2023-2034) ($MN)
16 Global Technical Ceramics Market Outlook, By Ceramic Matrix Composites (2023-2034) ($MN)
17 Global Technical Ceramics Market Outlook, By Porous Ceramics (2023-2034) ($MN)
18 Global Technical Ceramics Market Outlook, By Manufacturing Process (2023-2034) ($MN)
19 Global Technical Ceramics Market Outlook, By Dry Pressing (2023-2034) ($MN)
20 Global Technical Ceramics Market Outlook, By Isostatic Pressing (2023-2034) ($MN)
21 Global Technical Ceramics Market Outlook, By Injection Molding (2023-2034) ($MN)
22 Global Technical Ceramics Market Outlook, By Extrusion (2023-2034) ($MN)
23 Global Technical Ceramics Market Outlook, By Slip Casting (2023-2034) ($MN)
24 Global Technical Ceramics Market Outlook, By Tape Casting (2023-2034) ($MN)
25 Global Technical Ceramics Market Outlook, By Additive Manufacturing (2023-2034) ($MN)
26 Global Technical Ceramics Market Outlook, By Other Manufacturing Processes (2023-2034) ($MN)
27 Global Technical Ceramics Market Outlook, By Function (2023-2034) ($MN)
28 Global Technical Ceramics Market Outlook, By Structural Ceramics (2023-2034) ($MN)
29 Global Technical Ceramics Market Outlook, By Functional Ceramics (2023-2034) ($MN)
30 Global Technical Ceramics Market Outlook, By Bioceramics (2023-2034) ($MN)
31 Global Technical Ceramics Market Outlook, By Application (2023-2034) ($MN)
32 Global Technical Ceramics Market Outlook, By Electronics & Semiconductor (2023-2034) ($MN)
33 Global Technical Ceramics Market Outlook, By Medical Devices & Implants (2023-2034) ($MN)
34 Global Technical Ceramics Market Outlook, By Automotive Components (2023-2034) ($MN)
35 Global Technical Ceramics Market Outlook, By Aerospace Components (2023-2034) ($MN)
36 Global Technical Ceramics Market Outlook, By Industrial Machinery (2023-2034) ($MN)
37 Global Technical Ceramics Market Outlook, By Energy Systems (2023-2034) ($MN)
38 Global Technical Ceramics Market Outlook, By Chemical Processing Equipment (2023-2034) ($MN)
39 Global Technical Ceramics Market Outlook, By Defense & Ballistic Protection (2023-2034) ($MN)
40 Global Technical Ceramics Market Outlook, By Cutting Tools (2023-2034) ($MN)
41 Global Technical Ceramics Market Outlook, By Optical Components (2023-2034) ($MN)
42 Global Technical Ceramics Market Outlook, By Filtration Systems (2023-2034) ($MN)
43 Global Technical Ceramics Market Outlook, By End-User (2023-2034) ($MN)
44 Global Technical Ceramics Market Outlook, By Electronics & Semiconductor (2023-2034) ($MN)
45 Global Technical Ceramics Market Outlook, By Automotive (2023-2034) ($MN)
46 Global Technical Ceramics Market Outlook, By Aerospace & Defense (2023-2034) ($MN)
47 Global Technical Ceramics Market Outlook, By Healthcare (2023-2034) ($MN)
48 Global Technical Ceramics Market Outlook, By Industrial Manufacturing (2023-2034) ($MN)
49 Global Technical Ceramics Market Outlook, By Energy & Power (2023-2034) ($MN)
50 Global Technical Ceramics Market Outlook, By Chemical & Petrochemical (2023-2034) ($MN)
51 Global Technical Ceramics Market Outlook, By Research & Academia (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
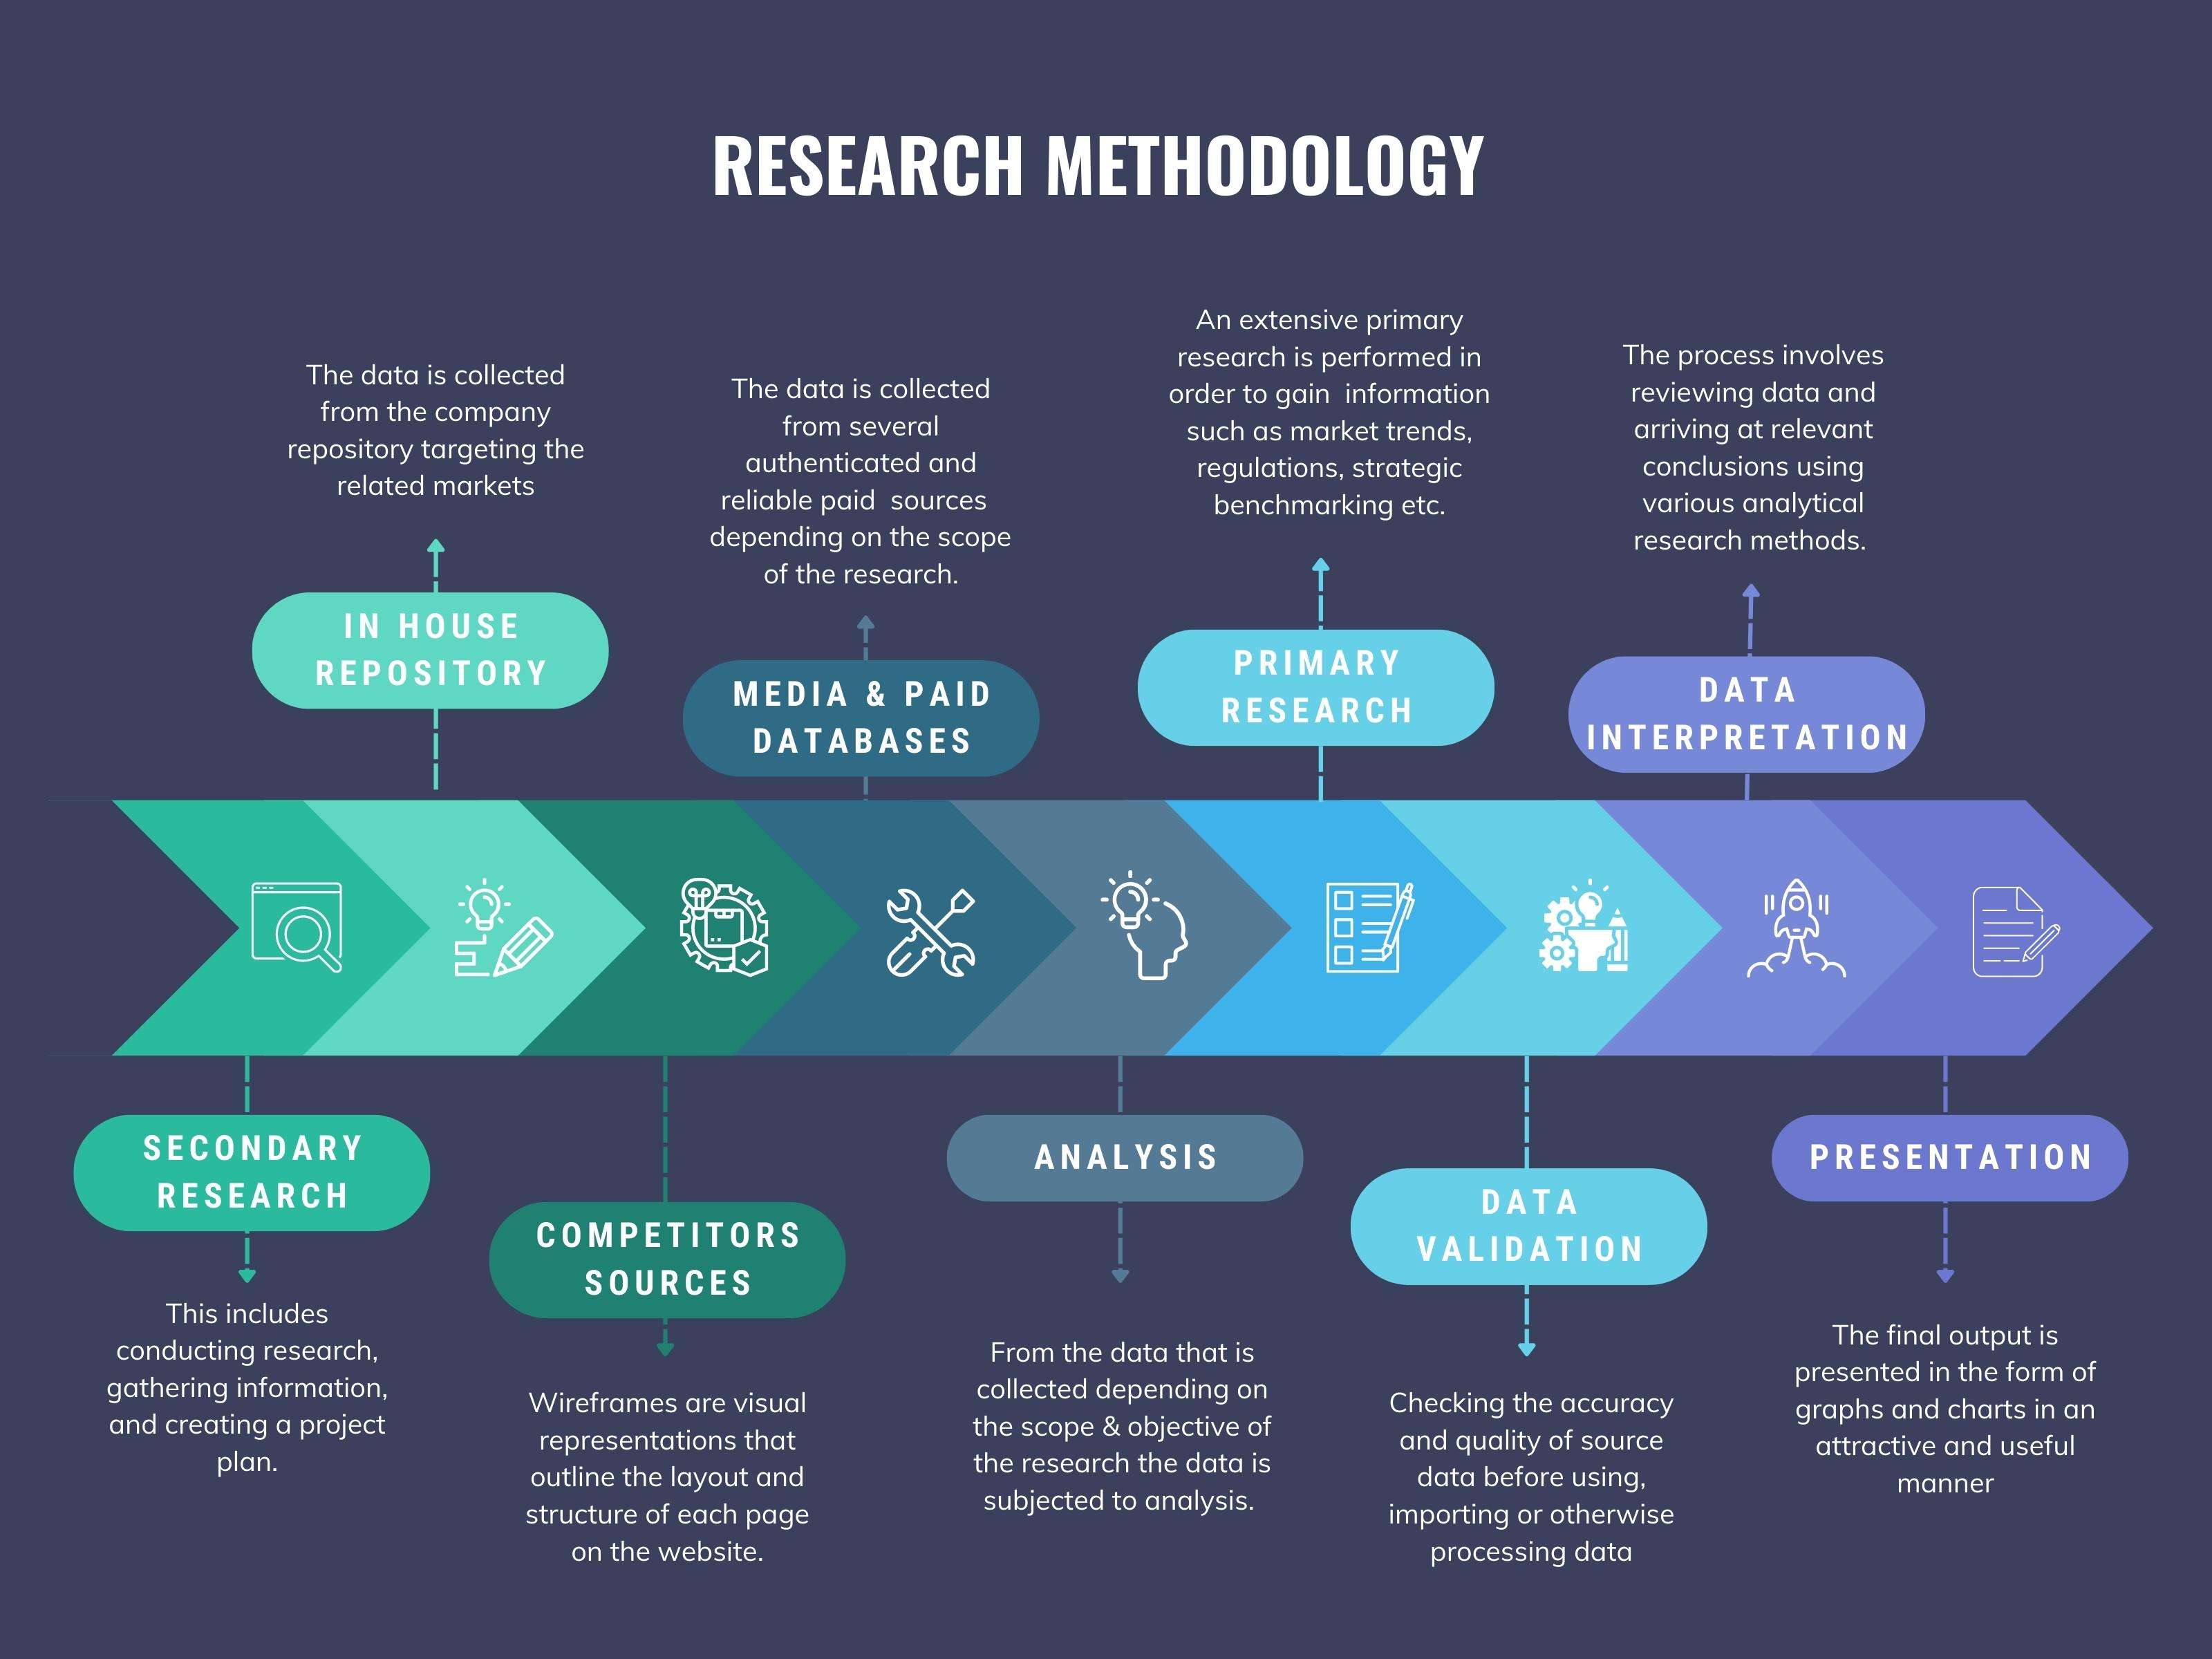
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.