Transportation Digital Twin Market
Transportation Digital Twin Market Forecasts to 2034 – Global Analysis By Twin Scope (Vehicle Twins, Infrastructure Twins, Traffic Environment Twins, Transportation Network Twins, Communication Network Twins, System-Level Twins and Other Twin Scopes), Physical Asset, Lifecycle Stage, Synchronization Level, End User, and Geography
According to Stratistics MRC, the Global Transportation Digital Twin Market is accounted for $3.20 billion in 2026 and is expected to reach $15.10 billion by 2034 growing at a CAGR of 21.4% during the forecast period. Transportation digital twin refers to a virtual representation of transportation assets, infrastructure, networks, and operational processes that is continuously updated using real-world data. These systems integrate IoT sensors, artificial intelligence, simulation technologies, cloud computing, and real-time analytics to model traffic conditions, vehicle movements, infrastructure performance, and logistics operations. Transportation digital twins enable scenario testing, predictive maintenance, network optimization, and informed infrastructure planning without disrupting physical operations. Increasing investments in smart transportation infrastructure and intelligent mobility management are driving adoption of transportation digital twin technologies.
Market Dynamics:
Driver:
Rising simulation-based planning adoption
Digital twins allow enterprises to replicate real-world infrastructure and vehicle systems, enabling predictive analysis and scenario testing. Governments are supporting simulation-based planning to optimize urban mobility, reduce congestion, and improve sustainability. Customers benefit from more reliable transport services and reduced delays. Advances in IoT sensors, AI-driven analytics, and cloud computing are expanding the scope of digital twin applications. Logistics providers and fleet operators are leveraging simulation to enhance operational resilience. Collectively, these factors are driving strong growth in the transportation digital twin market.
Restraint:
Complex infrastructure data integration
Transportation systems involve diverse data sources, including traffic sensors, fleet telematics, and urban infrastructure databases. Enterprises face difficulties in harmonizing these datasets into unified digital twin platforms. Smaller firms struggle with the high costs of integration compared to established players. Governments are pushing for interoperability standards, but adoption remains uneven across regions. Customers may experience incomplete visibility when data integration is inconsistent. This complexity continues to restrain adoption and slows down scalability of digital twin solutions.
Opportunity:
Real-time network simulation platforms
Real-time network simulation platforms present a major opportunity for market expansion. By enabling continuous monitoring and predictive modeling, enterprises can optimize fleet operations, traffic flows, and infrastructure planning. Governments are encouraging real-time simulation adoption as part of smart city initiatives. Customers benefit from improved reliability, reduced travel times, and enhanced safety. Advances in AI, machine learning, and edge computing are enabling faster and more accurate simulations. Partnerships between technology firms, transport authorities, and fleet operators are accelerating deployment. This opportunity is expected to redefine transportation management by shifting from reactive operations to proactive optimization.
Threat:
Cybersecurity risks to digital models
Cybersecurity risks to digital models pose a significant threat to the transportation digital twin market. As digital twins replicate critical infrastructure and fleet operations, they become attractive targets for cyberattacks. Enterprises must invest heavily in secure encryption, intrusion detection, and resilience frameworks to protect sensitive data. Governments are tightening regulations around cybersecurity compliance, raising costs for operators. Customers may lose trust in platforms that fail to safeguard data integrity. Smaller firms are particularly vulnerable compared to larger competitors with advanced security capabilities. Unless robust safeguards are implemented, cybersecurity risks will remain a persistent challenge that could undermine confidence in digital twin adoption.
Covid-19 Impact:
The pandemic disrupted transportation networks, creating unprecedented demand for digital twin solutions to manage uncertainty. Lockdowns highlighted the need for simulation-based planning to optimize reduced capacity and reroute fleets. Enterprises accelerated investment in digital twin platforms to maintain operational continuity. Governments emphasized digital infrastructure as part of recovery strategies, reinforcing the importance of simulation technologies. Customers became more reliant on platforms that provided transparency and predictive insights during disruptions. Advances in remote monitoring and AI-driven analytics gained traction during the crisis.
The infrastructure twins segment is expected to be the largest during the forecast period
The infrastructure twins segment is expected to account for the largest market share during the forecast period as urban transport systems increasingly rely on digital replicas for planning and optimization. Enterprises use infrastructure twins to simulate traffic flows, construction impacts, and maintenance schedules. Governments are prioritizing infrastructure twins in smart city projects to improve efficiency and sustainability. Customers benefit from reduced congestion and improved service reliability. Advances in sensor integration and cloud-based platforms are enhancing scalability. Partnerships with urban planners and technology providers are expanding adoption. Consequently, infrastructure twins dominate the transportation digital twin market.
The vehicles & fleets segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the vehicles & fleets segment is predicted to witness the highest growth rate due to rising demand for real-time fleet management and predictive maintenance. Enterprises are deploying vehicle twins to monitor performance, optimize routes, and reduce downtime. Governments are supporting fleet digitalization as part of sustainable transport initiatives. Customers benefit from improved reliability, reduced costs, and enhanced safety. Advances in IoT-enabled telematics and AI-driven predictive analytics are accelerating adoption. Smaller firms find opportunities in niche fleet applications such as logistics, ride-hailing, and public transport.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share owing to early adoption of digital twin technologies. The U.S. leads in deploying transportation digital twins across urban mobility, logistics, and fleet management. Enterprises are investing heavily in advanced simulation platforms. Customers demand reliable, transparent transport services at higher rates compared to other regions. Regulatory frameworks support innovation while enforcing compliance with safety and cybersecurity standards. Governments are funding pilot projects for smart city and digital infrastructure modernization. These factors collectively secure North America’s leadership in the market.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR driven by rapid urbanization and expanding smart city projects. Countries such as China, India, and Japan are scaling up digital twin adoption to meet rising transport challenges. Expanding middle-class populations are fueling demand for reliable, efficient mobility solutions. Governments are introducing supportive policies to encourage domestic innovation in simulation technologies. Local firms are expanding production to serve both regional and global markets. Advances in real-time network simulation and fleet digitalization accelerate adoption in this region.
Key players in the market
Some of the key players in Transportation Digital Twin Market include Siemens AG, PTC Inc., IBM Corporation, Microsoft Corporation, Autodesk, Inc., Dassault Systèmes SE, Hexagon AB, Ansys, Inc., Schneider Electric SE, Honeywell International Inc., Trimble Inc., Cisco Systems, Inc., Robert Bosch GmbH, AVEVA Group plc and SenseTime Group Inc.
Key Developments:
In March 2026, PTV Group enhanced its PTV Route Optimiser platform by deploying real-time machine-learning traffic algorithms and automated toll-calculation engines. The software dynamically restructures heavy-goods vehicle (HGV) delivery routes to reduce transit emissions and fuel consumption.
In January 2026, Microsoft Corporation launched Azure AI Health Bot modules pre-configured with neurodevelopmental screening and cognitive tracking workflows. The solution integrates with enterprise electronic health records to allow clinicians to collect patient-reported cognitive metrics securely.
Twin Scopes Covered:
• Vehicle Twins
• Infrastructure Twins
• Traffic Environment Twins
• Transportation Network Twins
• Communication Network Twins
• System-Level Twins
• Other Twin Scopes
Physical Assets Covered:
• Roads & Highways
• Bridges & Tunnels
• Vehicles & Fleets
• Rail Infrastructure
• Ports & Maritime Assets
• Other Physical Assets
Lifecycle Stages Covered:
• Planning & Design
• Construction & Commissioning
• Operations
• Maintenance & Renewal
• Other Lifecycle Stages
Synchronization Levels Covered:
• Static Digital Models
• Near-Real-Time Twins
• Real-Time Synchronized Twins
• Autonomous Adaptive Twins
• Other Synchronization Levels
End Users Covered:
• Transportation Authorities
• Rail Operators
• Airports
• Port Operators
• Infrastructure Owners
• Other End Users
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest ((Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Transportation Digital Twin Market, By Twin Scope
5.1 Vehicle Twins
5.2 Infrastructure Twins
5.3 Traffic Environment Twins
5.4 Transportation Network Twins
5.5 Communication Network Twins
5.6 System-Level Twins
5.7 Other Twin Scopes
6 Global Transportation Digital Twin Market, By Physical Asset
6.1 Roads & Highways
6.2 Bridges & Tunnels
6.3 Vehicles & Fleets
6.4 Rail Infrastructure
6.5 Ports & Maritime Assets
6.6 Other Physical Assets
7 Global Transportation Digital Twin Market, By Lifecycle Stage
7.1 Planning & Design
7.2 Construction & Commissioning
7.3 Operations
7.4 Maintenance & Renewal
7.5 Other Lifecycle Stages
8 Global Transportation Digital Twin Market, By Synchronization Level
8.1 Static Digital Models
8.2 Near-Real-Time Twins
8.3 Real-Time Synchronized Twins
8.4 Autonomous Adaptive Twins
8.5 Other Synchronization Levels
9 Global Transportation Digital Twin Market, By End User
9.1 Transportation Authorities
9.2 Rail Operators
9.3 Airports
9.4 Port Operators
9.5 Infrastructure Owners
9.6 Other End Users
10 Global Transportation Digital Twin Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Siemens AG
13.2 PTC Inc.
13.3 IBM Corporation
13.4 Microsoft Corporation
13.5 Autodesk, Inc.
13.6 Dassault Systèmes SE
13.7 Hexagon AB
13.8 Ansys, Inc.
13.9 Schneider Electric SE
13.10 Honeywell International Inc.
13.11 Trimble Inc.
13.12 Cisco Systems, Inc.
13.13 Robert Bosch GmbH
13.14 AVEVA Group plc
13.15 SenseTime Group Inc.
List of Tables
1 Global Transportation Digital Twin Market Outlook, By Region (2023-2034) ($MN)
2 Global Transportation Digital Twin Market, By Twin Scope (2023–2034) ($MN)
3 Global Transportation Digital Twin Market, By Vehicle Twins (2023–2034) ($MN)
4 Global Transportation Digital Twin Market, By Infrastructure Twins (2023–2034) ($MN)
5 Global Transportation Digital Twin Market, By Traffic Environment Twins (2023–2034) ($MN)
6 Global Transportation Digital Twin Market, By Transportation Network Twins (2023–2034) ($MN)
7 Global Transportation Digital Twin Market, By Communication Network Twins (2023–2034) ($MN)
8 Global Transportation Digital Twin Market, By System-Level Twins (2023–2034) ($MN)
9 Global Transportation Digital Twin Market, By Other Twin Scopes (2023–2034) ($MN)
10 Global Transportation Digital Twin Market, By Physical Asset (2023–2034) ($MN)
11 Global Transportation Digital Twin Market, By Roads & Highways (2023–2034) ($MN)
12 Global Transportation Digital Twin Market, By Bridges & Tunnels (2023–2034) ($MN)
13 Global Transportation Digital Twin Market, By Vehicles & Fleets (2023–2034) ($MN)
14 Global Transportation Digital Twin Market, By Rail Infrastructure (2023–2034) ($MN)
15 Global Transportation Digital Twin Market, By Ports & Maritime Assets (2023–2034) ($MN)
16 Global Transportation Digital Twin Market, By Other Physical Assets (2023–2034) ($MN)
17 Global Transportation Digital Twin Market, By Lifecycle Stage (2023–2034) ($MN)
18 Global Transportation Digital Twin Market, By Planning & Design (2023–2034) ($MN)
19 Global Transportation Digital Twin Market, By Construction & Commissioning (2023–2034) ($MN)
20 Global Transportation Digital Twin Market, By Operations (2023–2034) ($MN)
21 Global Transportation Digital Twin Market, By Maintenance & Renewal (2023–2034) ($MN)
22 Global Transportation Digital Twin Market, By Other Lifecycle Stages (2023–2034) ($MN)
23 Global Transportation Digital Twin Market, By Synchronization Level (2023–2034) ($MN)
24 Global Transportation Digital Twin Market, By Static Digital Models (2023–2034) ($MN)
25 Global Transportation Digital Twin Market, By Near-Real-Time Twins (2023–2034) ($MN)
26 Global Transportation Digital Twin Market, By Real-Time Synchronized Twins (2023–2034) ($MN)
27 Global Transportation Digital Twin Market, By Autonomous Adaptive Twins (2023–2034) ($MN)
28 Global Transportation Digital Twin Market, By Other Synchronization Levels (2023–2034) ($MN)
29 Global Transportation Digital Twin Market, By End User (2023–2034) ($MN)
30 Global Transportation Digital Twin Market, By Transportation Authorities (2023–2034) ($MN)
31 Global Transportation Digital Twin Market, By Rail Operators (2023–2034) ($MN)
32 Global Transportation Digital Twin Market, By Airports (2023–2034) ($MN)
33 Global Transportation Digital Twin Market, By Port Operators (2023–2034) ($MN)
34 Global Transportation Digital Twin Market, By Infrastructure Owners (2023–2034) ($MN)
35 Global Transportation Digital Twin Market, By Other End Users (2023–2034) ($MN)
(Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
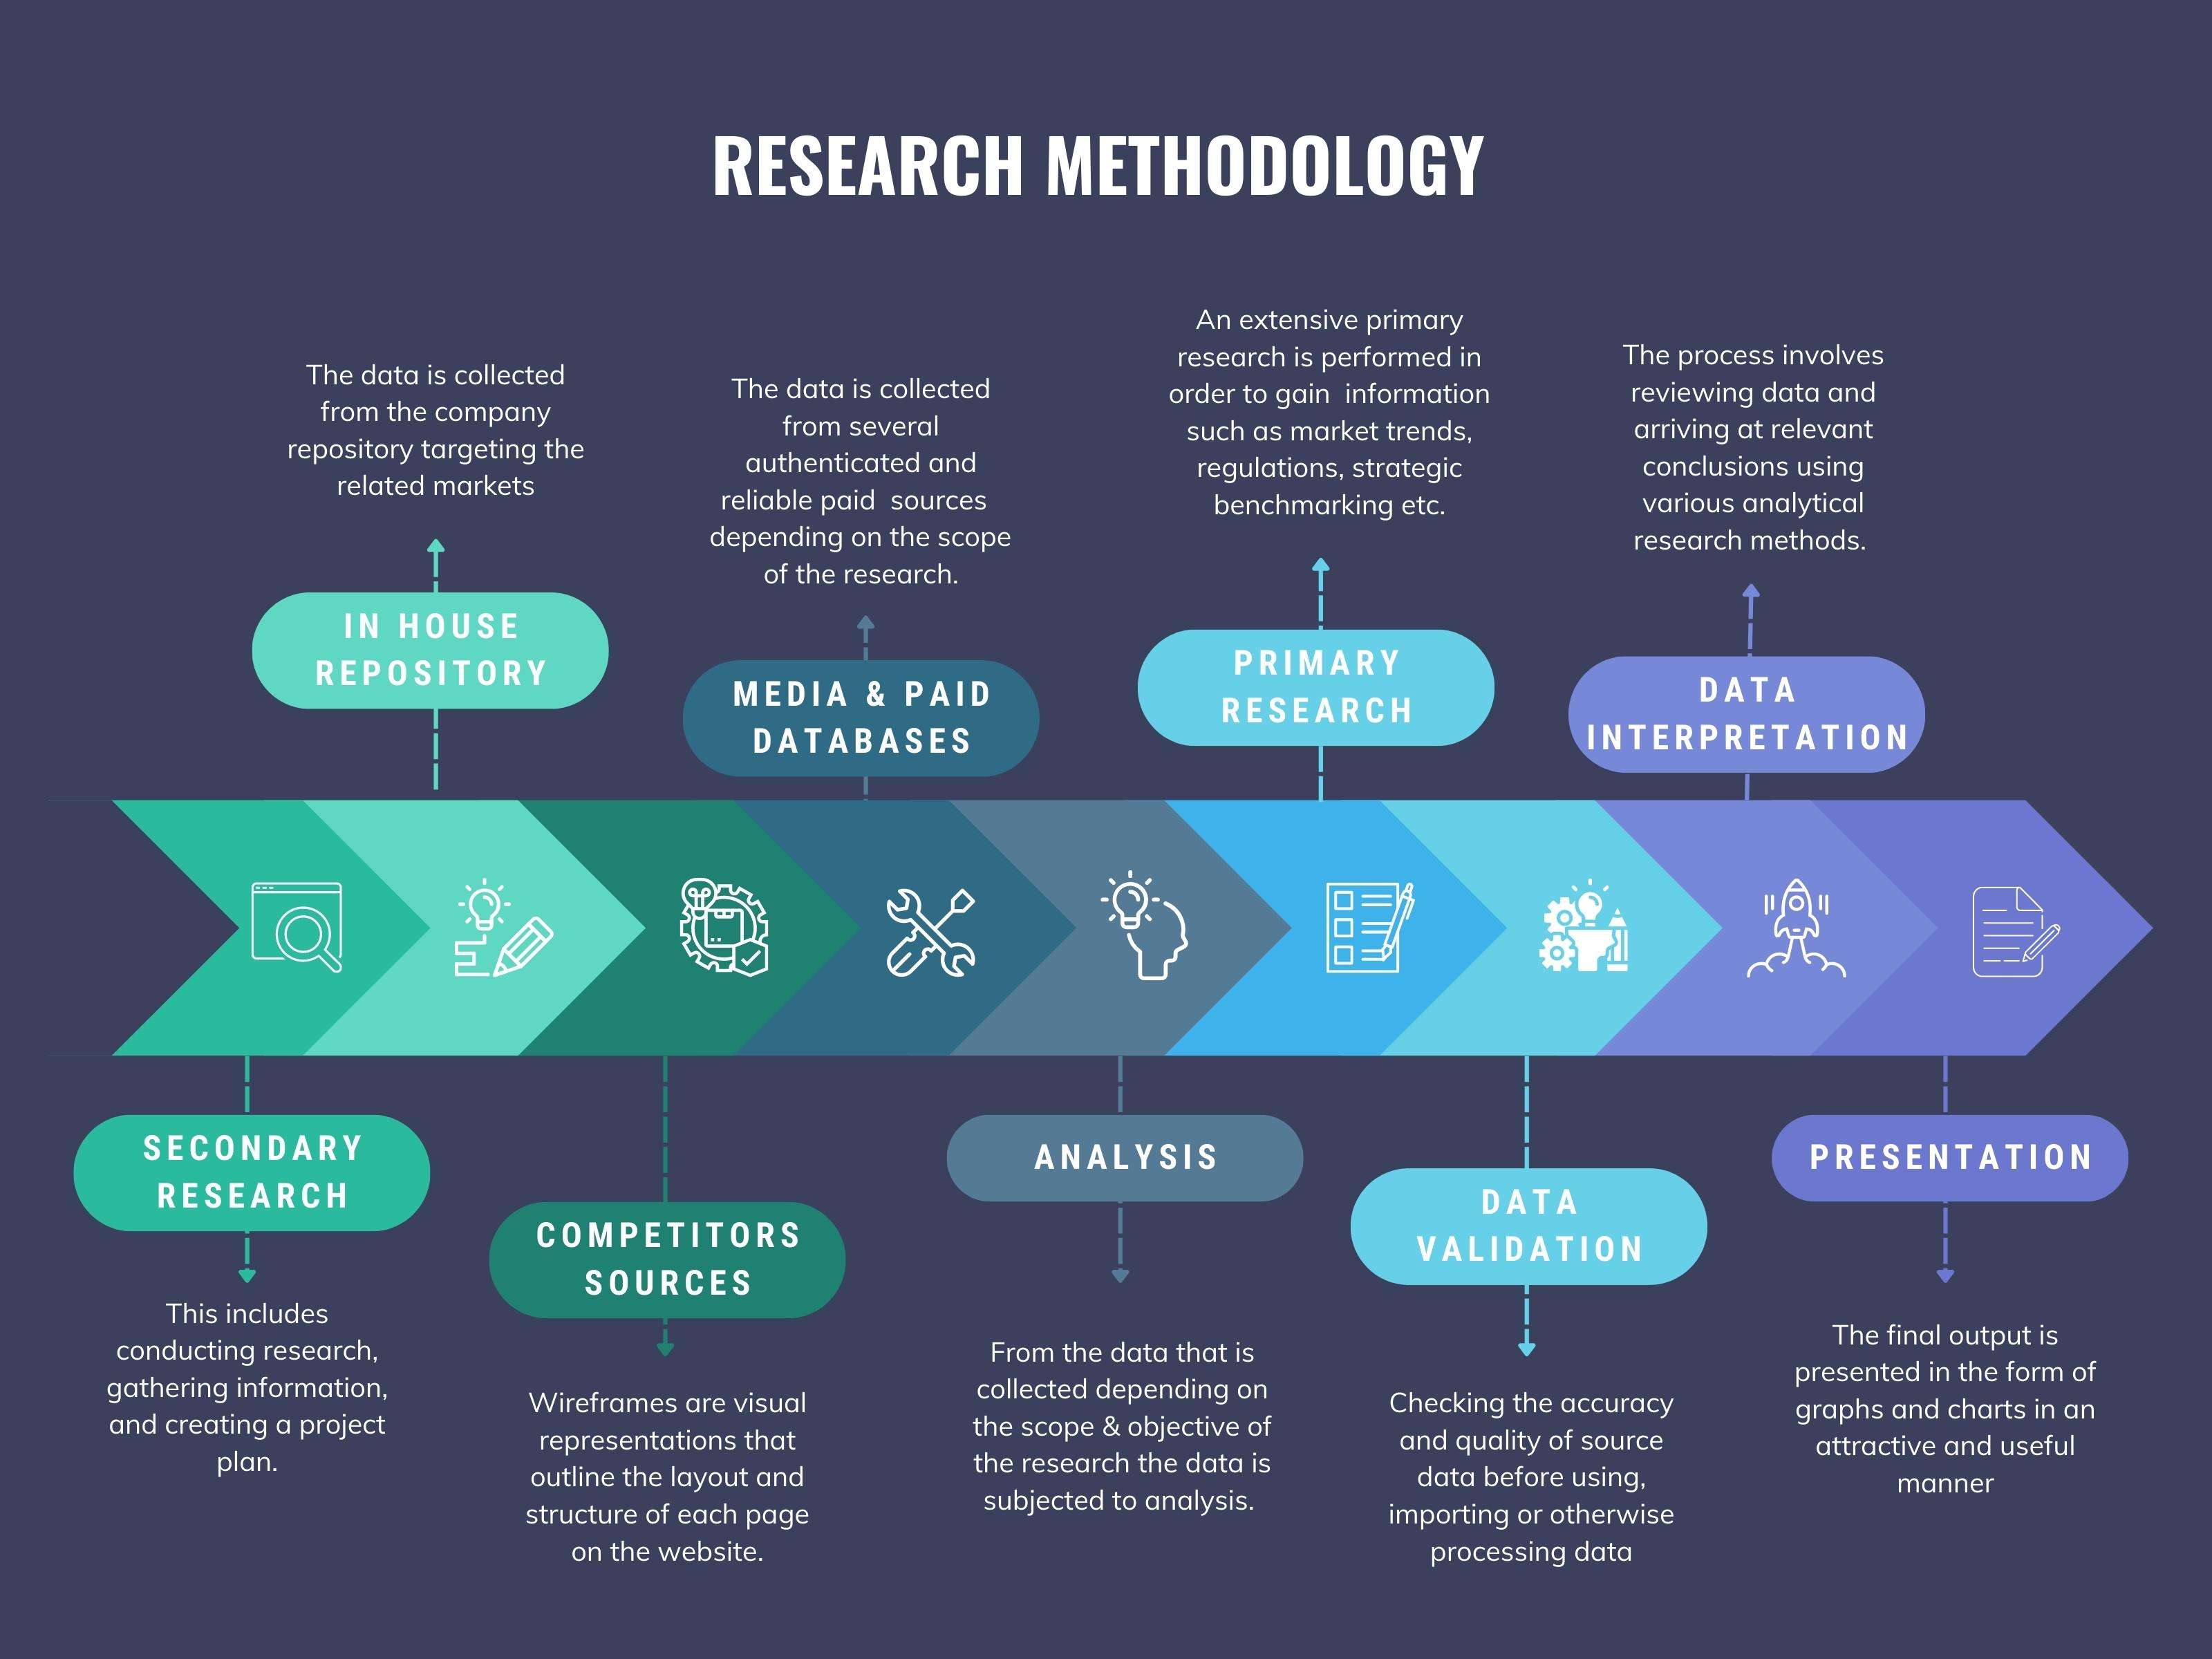
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.