Automotive Cybersecurity Market
Automotive Cybersecurity Market Forecasts To 2034 – Global Analysis By Security Domain (Network Security, Application Security, Endpoint Security, Cloud Security and Wireless Security), Solution, Offering, Vehicle Type, Propulsion Type, Autonomy Level, Application, Connectivity Technology, Deployment, End User and By Geography
According to Stratistics MRC, the Global Automotive Cybersecurity Market is accounted for $5.2 billion in 2026 and is expected to reach $18.9 billion by 2034 growing at a CAGR of 17.4% during the forecast period. The AUTOMOTIVE CYBERSECURITY Market is witnessing strong growth due to the increasing digitalization and connectivity of modern vehicles. Automobiles now incorporate advanced technologies such as ADAS, telematics, infotainment, V2X communication, cloud platforms, and OTA updates, which expand their exposure to potential cyberattacks. This is encouraging automotive manufacturers and suppliers to deploy technologies that safeguard vehicle networks, ECUs, software, sensitive information, and connected services. The growing penetration of electric, autonomous, and software-defined vehicles is creating additional demand for encryption, secure authentication, intrusion detection, vulnerability assessment, and protected software management. Furthermore, evolving automotive cybersecurity regulations are encouraging manufacturers to implement security measures across the complete vehicle development and operational lifecycle.
Market Dynamics:
Driver:
Increasing Cyber attacks and Evolving Cyber Threats
The growing sophistication and frequency of cyber threats against automotive systems is creating strong demand for cybersecurity solutions. Today's vehicles depend on extensive software, ECUs, wireless interfaces, and connected services, exposing them to risks including unauthorized access, ransomware, malware, information theft, and remote system manipulation. Attacks involving vehicles and automotive supply-chain infrastructure have increased industry awareness of these vulnerabilities. In response, manufacturers and suppliers are investing in intrusion detection, secure endpoints, encryption, vulnerability assessment, and threat-intelligence technologies. Protecting vehicle operations, customer information, and safety-critical functions has become increasingly important, encouraging automotive companies to adopt continuous cybersecurity measures and strengthen protection throughout connected vehicle ecosystems.
Restraint:
High Implementation and Integration Costs
The substantial expense associated with implementing and integrating cybersecurity technologies can limit the expansion of the automotive cybersecurity market. Effective protection requires spending on secure components, cybersecurity software, encryption, intrusion detection, vulnerability testing, and monitoring capabilities. Automotive architectures are highly complex, containing interconnected ECUs, sensors, networks, and software, making integration technically demanding and expensive. Additional expenditures arise from compliance, certification, maintenance, security testing, and continuous software updates throughout the vehicle lifecycle. Smaller suppliers and manufacturers may experience greater difficulty absorbing these costs because of limited budgets and competitive pricing pressures. Therefore, significant initial and ongoing investments can restrict cybersecurity adoption, particularly among price-sensitive vehicle manufacturers and emerging markets.
Opportunity:
Development of AI-Driven Automotive Cybersecurity
Advances in artificial intelligence and machine learning are creating attractive opportunities for automotive cybersecurity companies. Increasingly complicated vehicle networks and software architectures can generate security events that conventional protection methods may not identify efficiently. AI-based cybersecurity platforms can process extensive vehicle data, recognize abnormal behavior, detect potential intrusions, and support rapid responses. Machine-learning algorithms can also continuously improve vulnerability detection and identify emerging attack patterns based on historical and real-time security information. Automotive security providers can incorporate these capabilities into intrusion detection, threat intelligence, monitoring, and incident-response systems. As cyberattacks become more sophisticated, intelligent security technologies can provide adaptive protection while expanding the range of advanced cybersecurity products available to vehicle manufacturers.
Threat:
Rapid Expansion of Connected Attack Surfaces
The growing number of digital connections within modern vehicles is expanding the potential attack surface and creating an important industry threat. Cellular connectivity, Wi-Fi, Bluetooth, V2X communication, mobile applications, cloud platforms, and charging infrastructure all provide additional pathways that attackers could potentially exploit. Software-defined vehicles further increase exposure because their functions remain continuously connected and can receive remote software updates. Cybercriminals may target APIs, communication interfaces, cloud systems, or connected devices to access vehicle functions or sensitive information. Protecting this expanding network of digital entry points requires increasingly comprehensive security architectures. Consequently, greater connectivity can increase cybersecurity complexity, operational expenditure, and the overall risk environment facing automakers and suppliers.
Covid-19 Impact:
The COVID-19 pandemic temporarily restrained the AUTOMOTIVE CYBERSECURITY Market because manufacturing shutdowns, disrupted supply chains, reduced vehicle sales, and economic uncertainty affected automotive investments. During the initial period, manufacturers concentrated on controlling costs, causing some technology and cybersecurity projects to be delayed. At the same time, increased dependence on digital operations, remote services, connected vehicles, and cloud technologies created greater exposure to cyber threats. This shift increased awareness of the importance of protecting automotive systems and encouraged organizations to strengthen cybersecurity capabilities. Following the pandemic, recovering vehicle production and accelerating adoption of connected, electric, and software-defined vehicles supported renewed demand for automotive cybersecurity solutions.
The Software segment is expected to be the largest during the forecast period
The Software segment is expected to account for the largest market share during the forecast period as automotive systems increasingly depend on sophisticated software and software-defined architectures. Cybersecurity software supports functions such as intrusion prevention, secure boot, encryption, vulnerability assessment, access management, threat detection, and protected OTA updates. Its ability to receive updates and respond to evolving cyber risks provides an important advantage for connected and digitally integrated vehicles. The expansion of telematics, ADAS, cloud connectivity, infotainment, and vehicle communication networks is also increasing demand for flexible software-based security. Consequently, software has become a fundamental element of automotive cybersecurity, supporting continuous protection across increasingly connected and software-intensive vehicle platforms.
The Battery Management Systems segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Battery Management Systems segment is predicted to witness the highest growth rate, supported by expanding electric vehicle adoption and increasing reliance on digitally controlled battery technologies. BMS platforms manage essential functions such as battery monitoring, charging and discharging, thermal regulation, and performance optimization. Their increasing integration with vehicle communication networks, charging stations, cloud services, and energy-management platforms introduces additional cybersecurity exposure. Consequently, manufacturers are placing greater emphasis on protecting battery software, communication channels, and operational information from cyber threats. The continued expansion of electric mobility and growing requirements for secure connected energy infrastructure are expected to strengthen demand for cybersecurity solutions designed for battery management systems.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by its extensive vehicle manufacturing ecosystem and accelerating adoption of connected, electric, and digitally advanced automobiles. The region hosts numerous major automotive and technology companies that are increasing investments in vehicle security as software and electronic systems become more sophisticated. Expanding use of telematics, infotainment, ADAS, V2X connectivity, and intelligent vehicle platforms is further increasing cybersecurity needs. Moreover, strong automotive production and growing integration of electronic technologies across China, Japan, South Korea, and India are contributing to sustained demand for advanced cybersecurity solutions across the regional automotive industry.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, driven by increasing deployment of connected, electric, autonomous, and software-driven vehicles throughout major automotive economies. China, Japan, South Korea, and India are strengthening their automotive technology ecosystems, creating greater requirements for vehicle protection. Expanding use of ADAS, telematics, V2X technologies, infotainment platforms, centralized vehicle architectures, and OTA updates is increasing the number of systems requiring cybersecurity protection. In addition, evolving cybersecurity regulations and greater integration of electronic technologies are encouraging manufacturers to strengthen vehicle security. These developments, combined with the region's strong automotive production capabilities, are expected to support rapid cybersecurity market expansion.
Key players in the market
Some of the key players in Automotive Cybersecurity Market include Robert Bosch GmbH, Continental AG, Aptiv PLC, DENSO Corporation, HARMAN International, NXP Semiconductors N.V., BlackBerry Limited, Infineon Technologies AG, Thales Group, Lear Corporation, Vector Informatik GmbH, Renesas Electronics Corporation, Cybellum Technologies Ltd., Upstream Security, Karamba Security, GuardKnox Cyber Technologies, VicOne and C2A Security.
Key Developments:
In May 2026, NXP announced a collaboration with Quanta to develop deterministic zonal networking for software-defined vehicles. The solution combines NXP S32 automotive processors, TSN-enabled networking, CAN/LIN connectivity, and scalable power management.
In April 2026, VicOne and Trustonic expanded their strategic partnership, combining VicOne's xCarbon intrusion detection/prevention technology and Edge AI capabilities with Trustonic's Kinibi Trusted Execution Environment.
In December 2025, DENSO announced a joint development agreement with MediaTek, signed in October 2025, to develop next-generation automotive SoCs. DENSO will define system requirements and architecture, while MediaTek handles detailed design and verification.
Security Domains Covered:
• Network Security
• Application Security
• Endpoint Security
• Cloud Security
• Wireless Security
Solutions Covered:
• Intrusion Detection and Prevention
• Encryption and Cryptography
• Identity and Access Management
• Vulnerability and Risk Management
• Secure Boot and Firmware Protection
• Security Information and Event Management
Offerings Covered:
• Hardware
• Software
• Services
Vehicle Types Covered:
• Passenger Cars
• Light Commercial Vehicles
• Heavy Commercial Vehicles
Propulsion Types Covered:
• Internal Combustion Engine Vehicles
• Hybrid Electric Vehicles
• Battery Electric Vehicles
• Fuel Cell Electric Vehicles
Autonomy Levels Covered:
• Non-Autonomous Vehicles
• Semi-Autonomous Vehicles
• Autonomous Vehicles
Applications Covered:
• ADAS and Safety Systems
• Infotainment Systems
• Telematics Systems
• Body Control Systems
• Powertrain Systems
• Battery Management Systems
Connectivity Technologies Covered:
• Cellular
• Wi-Fi
• Bluetooth
• Vehicle-to-Vehicle
• Vehicle-to-Infrastructure
• Vehicle-to-Everything
Deployments Covered:
• Embedded
• On-Premises
• Cloud-Based
• Hybrid
End Users Covered:
• Automotive OEMs
• Tier 1 Suppliers
• Fleet Operators
• Aftermarket Service Providers
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Automotive Cybersecurity Market, By Security Domain
5.1 Network Security
5.2 Application Security
5.3 Endpoint Security
5.4 Cloud Security
5.5 Wireless Security
6 Global Automotive Cybersecurity Market, By Solution
6.1 Intrusion Detection and Prevention
6.2 Encryption and Cryptography
6.3 Identity and Access Management
6.4 Vulnerability and Risk Management
6.5 Secure Boot and Firmware Protection
6.6 Security Information and Event Management
7 Global Automotive Cybersecurity Market, By Offering
7.1 Hardware
7.2 Software
7.3 Services
8 Global Automotive Cybersecurity Market, By Vehicle Type
8.1 Passenger Cars
8.2 Light Commercial Vehicles
8.3 Heavy Commercial Vehicles
9 Global Automotive Cybersecurity Market, By Propulsion Type
9.1 Internal Combustion Engine Vehicles
9.2 Hybrid Electric Vehicles
9.3 Battery Electric Vehicles
9.4 Fuel Cell Electric Vehicles
10 Global Automotive Cybersecurity Market, By Autonomy Level
10.1 Non-Autonomous Vehicles
10.2 Semi-Autonomous Vehicles
10.3 Autonomous Vehicles
11 Global Automotive Cybersecurity Market, By Application
11.1 ADAS and Safety Systems
11.2 Infotainment Systems
11.3 Telematics Systems
11.4 Body Control Systems
11.5 Powertrain Systems
11.6 Battery Management Systems
12 Global Automotive Cybersecurity Market, By Connectivity Technology
12.1 Cellular
12.2 Wi-Fi
12.3 Bluetooth
12.4 Vehicle-to-Vehicle
12.5 Vehicle-to-Infrastructure
12.6 Vehicle-to-Everything
13 Global Automotive Cybersecurity Market, By Deployment
13.1 Embedded
13.2 On-Premises
13.3 Cloud-Based
13.4 Hybrid
14 Global Automotive Cybersecurity Market, By End User
14.1 Automotive OEMs
14.2 Tier 1 Suppliers
14.3 Fleet Operators
14.4 Aftermarket Service Providers
15 Global Automotive Cybersecurity Market, By Geography
15.1 North America
15.1.1 United States
15.1.2 Canada
15.1.3 Mexico
15.2 Europe
15.2.1 United Kingdom
15.2.2 Germany
15.2.3 France
15.2.4 Italy
15.2.5 Spain
15.2.6 Netherlands
15.2.7 Belgium
15.2.8 Sweden
15.2.9 Switzerland
15.2.10 Poland
15.2.11 Rest of Europe
15.3 Asia Pacific
15.3.1 China
15.3.2 Japan
15.3.3 India
15.3.4 South Korea
15.3.5 Australia
15.3.6 Indonesia
15.3.7 Thailand
15.3.8 Malaysia
15.3.9 Singapore
15.3.10 Vietnam
15.3.11 Rest of Asia Pacific
15.4 South America
15.4.1 Brazil
15.4.2 Argentina
15.4.3 Colombia
15.4.4 Chile
15.4.5 Peru
15.4.6 Rest of South America
15.5 Rest of the World (RoW)
15.5.1 Middle East
15.5.1.1 Saudi Arabia
15.5.1.2 United Arab Emirates
15.5.1.3 Qatar
15.5.1.4 Israel
15.5.1.5 Rest of Middle East
15.5.2 Africa
15.5.2.1 South Africa
15.5.2.2 Egypt
15.5.2.3 Morocco
15.5.2.4 Rest of Africa
16 Strategic Market Intelligence
16.1 Industry Value Network and Supply Chain Assessment
16.2 White-Space and Opportunity Mapping
16.3 Product Evolution and Market Life Cycle Analysis
16.4 Channel, Distributor, and Go-to-Market Assessment
17 Industry Developments and Strategic Initiatives
17.1 Mergers and Acquisitions
17.2 Partnerships, Alliances, and Joint Ventures
17.3 New Product Launches and Certifications
17.4 Capacity Expansion and Investments
17.5 Other Strategic Initiatives
18 Company Profiles
18.1 Robert Bosch GmbH
18.2 Continental AG
18.3 Aptiv PLC
18.4 DENSO Corporation
18.5 HARMAN International
18.6 NXP Semiconductors N.V.
18.7 BlackBerry Limited
18.8 Infineon Technologies AG
18.9 Thales Group
18.10 Lear Corporation
18.11 Vector Informatik GmbH
18.12 Renesas Electronics Corporation
18.13 Cybellum Technologies Ltd.
18.14 Upstream Security
18.15 Karamba Security
18.16 GuardKnox Cyber Technologies
18.17 VicOne
18.18 C2A Security
List of Tables
1 Global Automotive Cybersecurity Market Outlook, By Region (2023-2034) ($MN)
2 Global Automotive Cybersecurity Market Outlook, By Security Domain (2023-2034) ($MN)
3 Global Automotive Cybersecurity Market Outlook, By Network Security (2023-2034) ($MN)
4 Global Automotive Cybersecurity Market Outlook, By Application Security (2023-2034) ($MN)
5 Global Automotive Cybersecurity Market Outlook, By Endpoint Security (2023-2034) ($MN)
6 Global Automotive Cybersecurity Market Outlook, By Cloud Security (2023-2034) ($MN)
7 Global Automotive Cybersecurity Market Outlook, By Wireless Security (2023-2034) ($MN)
8 Global Automotive Cybersecurity Market Outlook, By Solution (2023-2034) ($MN)
9 Global Automotive Cybersecurity Market Outlook, By Offering (2023-2034) ($MN)
10 Global Automotive Cybersecurity Market Outlook, By Hardware (2023-2034) ($MN)
11 Global Automotive Cybersecurity Market Outlook, By Software (2023-2034) ($MN)
12 Global Automotive Cybersecurity Market Outlook, By Services (2023-2034) ($MN)
13 Global Automotive Cybersecurity Market Outlook, By Intrusion Detection and Prevention (2023-2034) ($MN)
14 Global Automotive Cybersecurity Market Outlook, By Encryption and Cryptography (2023-2034) ($MN)
15 Global Automotive Cybersecurity Market Outlook, By Identity and Access Management (2023-2034) ($MN)
16 Global Automotive Cybersecurity Market Outlook, By Vulnerability and Risk Management (2023-2034) ($MN)
17 Global Automotive Cybersecurity Market Outlook, By Secure Boot and Firmware Protection (2023-2034) ($MN)
18 Global Automotive Cybersecurity Market Outlook, By Security Information and Event Management (2023-2034) ($MN)
19 Global Automotive Cybersecurity Market Outlook, By Offering (2023-2034) ($MN)
20 Global Automotive Cybersecurity Market Outlook, By Hardware (2023-2034) ($MN)
21 Global Automotive Cybersecurity Market Outlook, By Software (2023-2034) ($MN)
22 Global Automotive Cybersecurity Market Outlook, By Services (2023-2034) ($MN)
23 Global Automotive Cybersecurity Market Outlook, By Vehicle Type (2023-2034) ($MN)
24 Global Automotive Cybersecurity Market Outlook, By Passenger Cars (2023-2034) ($MN)
25 Global Automotive Cybersecurity Market Outlook, By Light Commercial Vehicles (2023-2034) ($MN)
26 Global Automotive Cybersecurity Market Outlook, By Heavy Commercial Vehicles (2023-2034) ($MN)
27 Global Automotive Cybersecurity Market Outlook, By Internal Combustion Engine Vehicles (2023-2034) ($MN)
28 Global Automotive Cybersecurity Market Outlook, By Hybrid Electric Vehicles (2023-2034) ($MN)
29 Global Automotive Cybersecurity Market Outlook, By Battery Electric Vehicles (2023-2034) ($MN)
30 Global Automotive Cybersecurity Market Outlook, By Fuel Cell Electric Vehicles (2023-2034) ($MN)
31 Global Automotive Cybersecurity Market Outlook, By Autonomy Level (2023-2034) ($MN)
32 Global Automotive Cybersecurity Market Outlook, By Non-Autonomous Vehicles (2023-2034) ($MN)
33 Global Automotive Cybersecurity Market Outlook, By Semi-Autonomous Vehicles (2023-2034) ($MN)
34 Global Automotive Cybersecurity Market Outlook, By Application (2023-2034) ($MN)
35 Global Automotive Cybersecurity Market Outlook, By ADAS and Safety Systems (2023-2034) ($MN)
36 Global Automotive Cybersecurity Market Outlook, By Infotainment Systems (2023-2034) ($MN)
37 Global Automotive Cybersecurity Market Outlook, By Telematics Systems (2023-2034) ($MN)
38 Global Automotive Cybersecurity Market Outlook, By Body Control Systems (2023-2034) ($MN)
39 Global Automotive Cybersecurity Market Outlook, By Powertrain Systems (2023-2034) ($MN)
40 Global Automotive Cybersecurity Market Outlook, By Battery Management Systems (2023-2034) ($MN)
41 Global Automotive Cybersecurity Market Outlook, By Connectivity Technology (2023-2034) ($MN)
42 Global Automotive Cybersecurity Market Outlook, By Cellular (2023-2034) ($MN)
43 Global Automotive Cybersecurity Market Outlook, By Wi-Fi (2023-2034) ($MN)
44 Global Automotive Cybersecurity Market Outlook, By Bluetooth (2023-2034) ($MN)
45 Global Automotive Cybersecurity Market Outlook, By Vehicle-to-Vehicle (2023-2034) ($MN)
46 Global Automotive Cybersecurity Market Outlook, By Vehicle-to-Infrastructure (2023-2034) ($MN)
47 Global Automotive Cybersecurity Market Outlook, By Vehicle-to-Everything (2023-2034) ($MN)
48 Global Automotive Cybersecurity Market Outlook, By Deployment (2023-2034) ($MN)
49 Global Automotive Cybersecurity Market Outlook, By Embedded (2023-2034) ($MN)
50 Global Automotive Cybersecurity Market Outlook, By On-Premises (2023-2034) ($MN)
51 Global Automotive Cybersecurity Market Outlook, By Cloud-Based (2023-2034) ($MN)
52 Global Automotive Cybersecurity Market Outlook, By Hybrid (2023-2034) ($MN)
53 Global Automotive Cybersecurity Market Outlook, By End User (2023-2034) ($MN)
54 Global Automotive Cybersecurity Market Outlook, By Automotive OEMs (2023-2034) ($MN)
55 Global Automotive Cybersecurity Market Outlook, By Tier 1 Suppliers (2023-2034) ($MN)
56 Global Automotive Cybersecurity Market Outlook, By Fleet Operators (2023-2034) ($MN)
57 Global Automotive Cybersecurity Market Outlook, By Aftermarket Service Providers (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
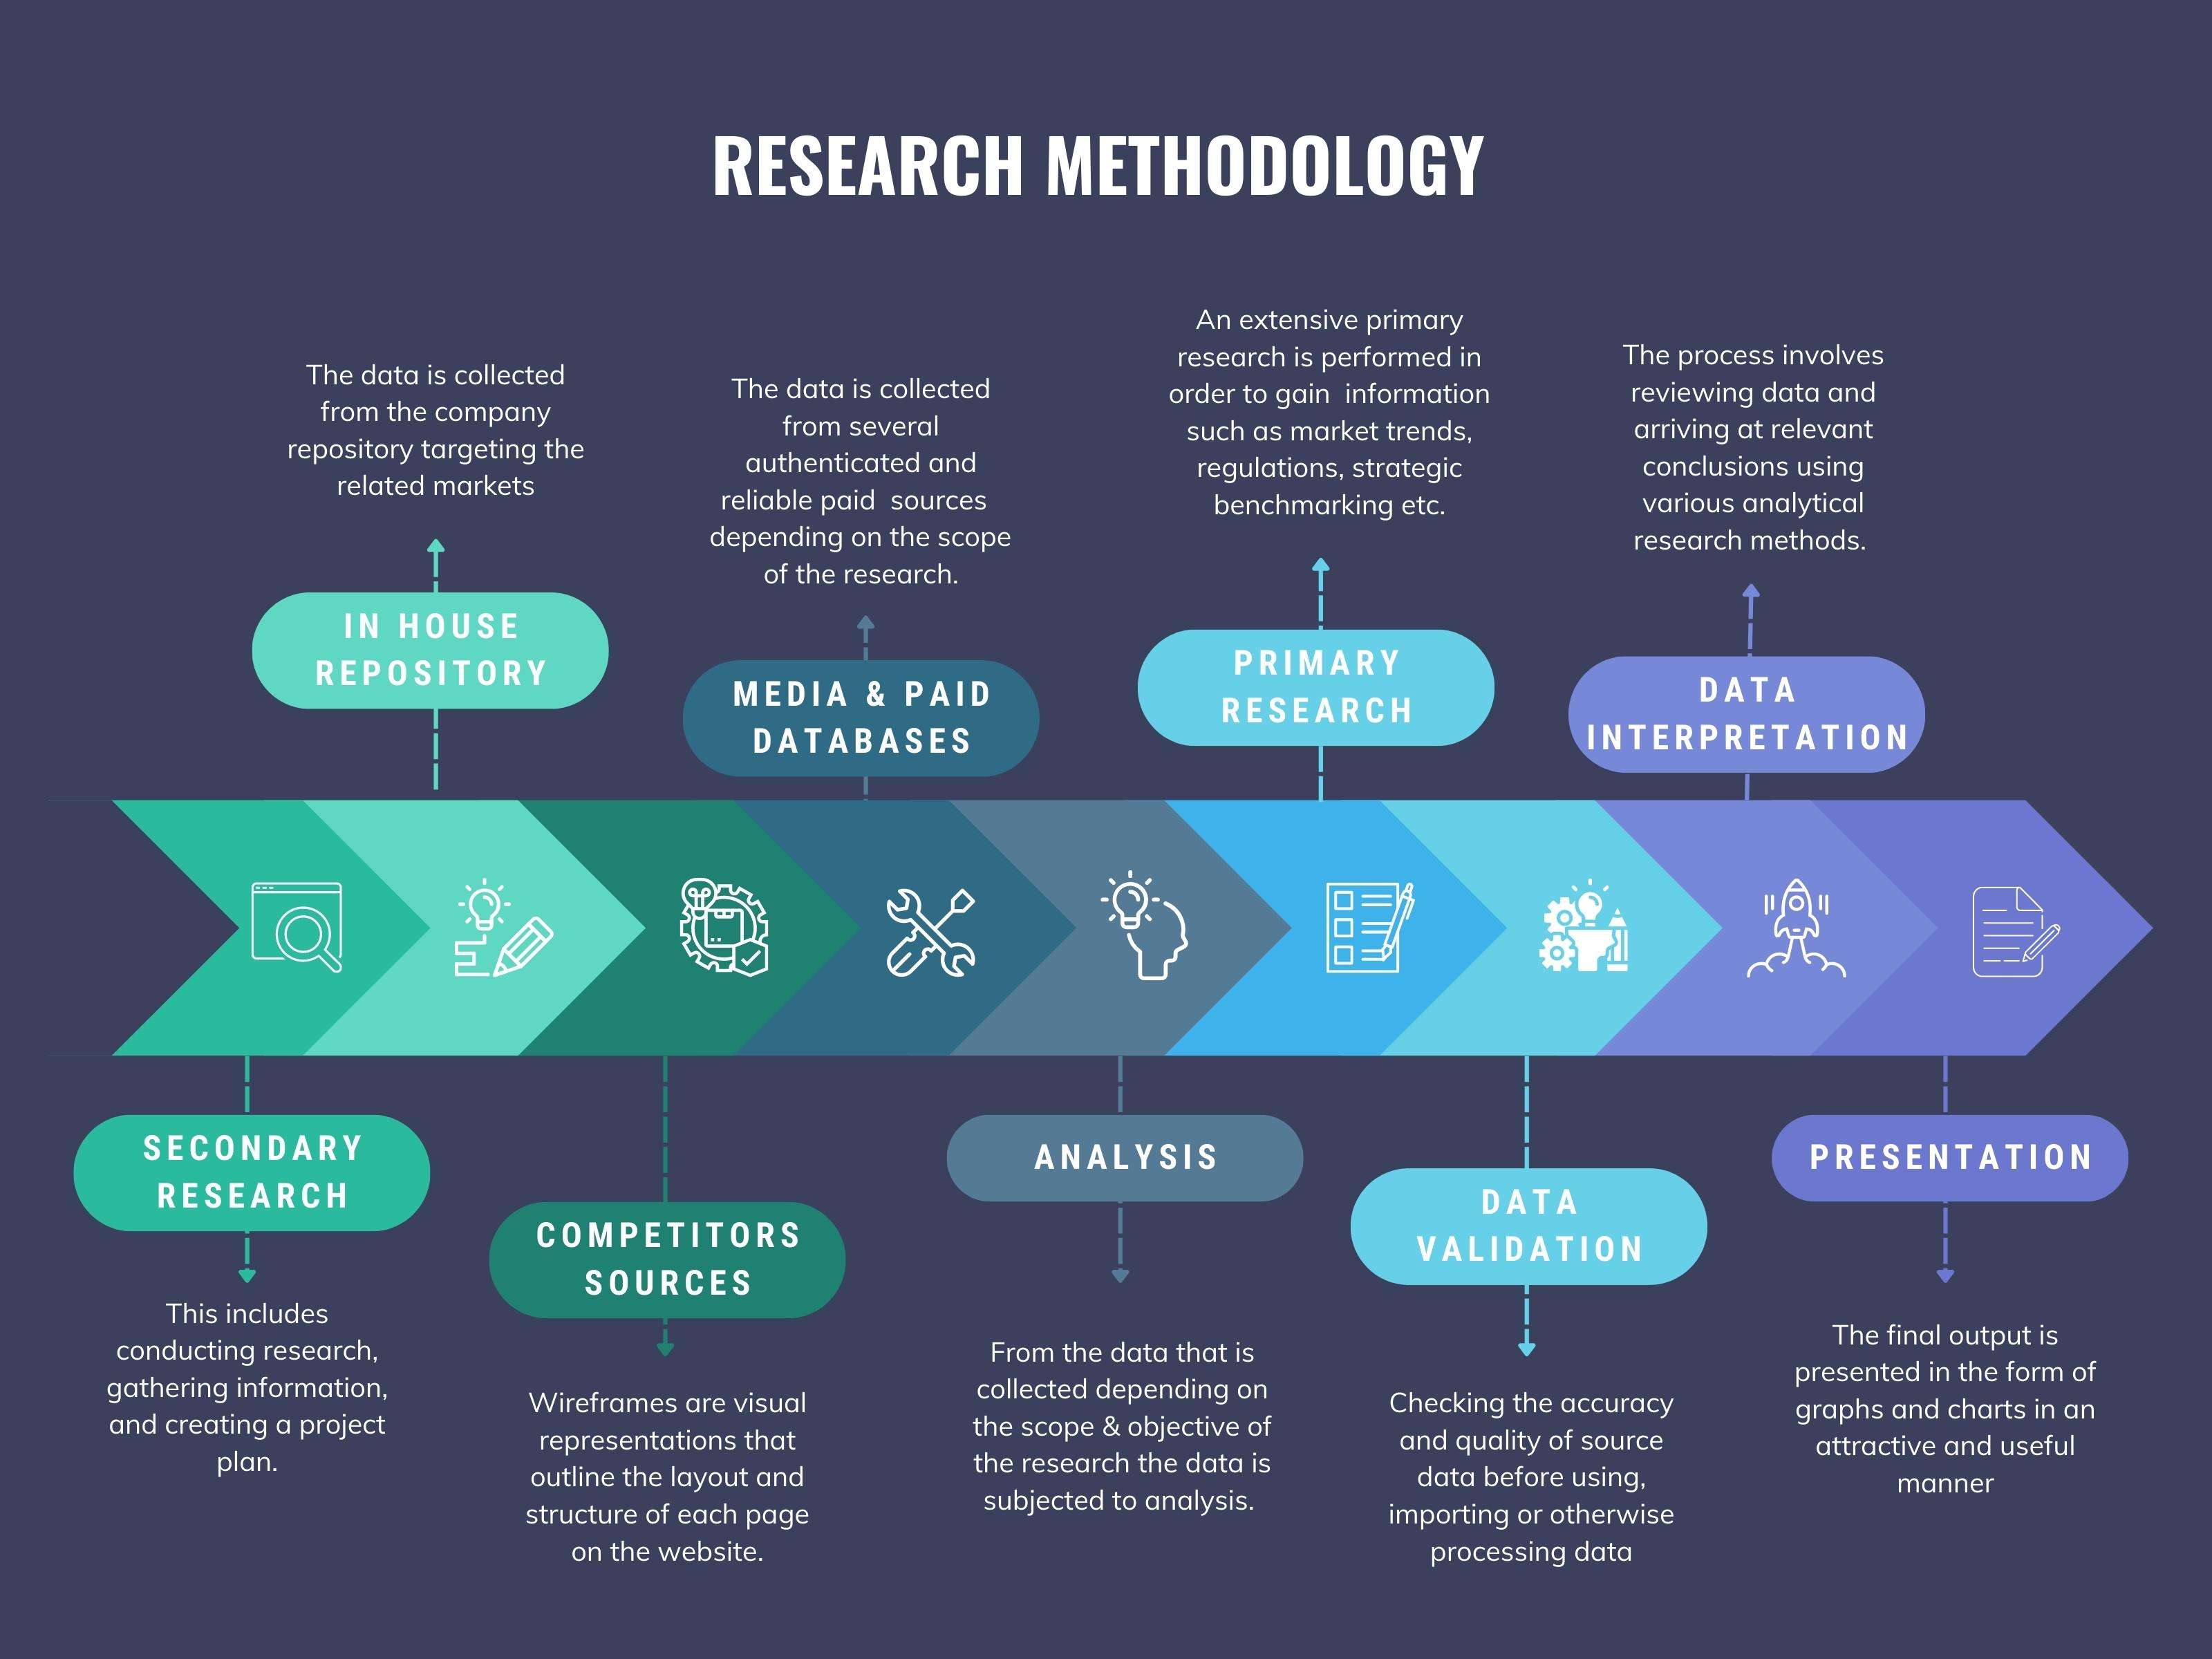
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.