Distributed Energy Resource Market
Distributed Energy Resource Market Forecasts to 2034 – Global Analysis By Resource Type (Distributed Energy Generation (Solar Photovoltaic (PV), Distributed Wind, Combined Heat & Power (CHP), Fuel Cells, Small Hydropower, and Other Distributed Generation Resources), Energy Storage (Battery Energy Storage, Thermal Energy Storage, and Other Energy Storage Resources), Flexible Loads & Demand Response (Smart HVAC Systems, Smart Water Heating, Smart Appliances, Industrial Load Flexibility, and Other Flexible Loads), Electric Vehicle Resources (EV Charging Systems, Vehicle-to-Home (V2H), Vehicle-to-Building (V2B), and Vehicle-to-Grid (V2G)), and Other Distributed Energy Resources), Configuration, Metering Configuration, Capacity, Ownership Model, Application, End User, and By Geography
According to Stratistics MRC, the Global Distributed Energy Resource Market is accounted for $43.7 billion in 2026 and is expected to reach $56.3 billion by 2034 growing at a CAGR of 3.2% during the forecast period. Distributed Energy Resources (DERs) are decentralized power generation, storage, and load management systems located close to the point of consumption, enabling greater energy efficiency, grid resilience, and renewable energy integration. These resources include distributed energy generation, energy storage, flexible loads and demand response, electric vehicle resources, and other DER types. The market encompasses standalone DER configurations, hybrid systems, and aggregated DERs including virtual power plants.
Market Dynamics:
Driver:
Increasing renewable energy adoption and decarbonization goals
The global transition toward renewable energy and ambitious decarbonization targets is a primary driver for the distributed energy resource market. Governments worldwide are implementing policies and incentives to promote distributed solar, wind, and other renewable generation. DERs enable integration of renewable energy at the distribution level, reducing transmission losses and enhancing grid resilience. The declining cost of solar PV, battery storage, and other DER technologies is making distributed generation increasingly cost-competitive. As countries pursue net-zero emissions targets and energy independence, investment in distributed energy resources continues growing, supporting sustained market expansion across all regions.
Restraint:
High upfront costs and financing challenges
The significant capital investment required for DER deployment and financing challenges represent a major restraint for the market. DER systems including solar PV, battery storage, and CHP require substantial upfront investment, despite declining technology costs. Access to financing can be limited, particularly for residential and small commercial customers. Complex ownership structures and incentives affect investment decisions. Return on investment periods vary significantly by region and application. These financial barriers may limit DER adoption, particularly among cost-sensitive customers and in regions with limited financing options.
Opportunity:
Adoption of virtual power plants and DER aggregation
The growing adoption of virtual power plants and DER aggregation platforms presents significant opportunities for market expansion. VPPs aggregate multiple distributed energy resources including solar, storage, and flexible loads to function as a single power plant, enabling DER participation in wholesale energy markets and grid services. Aggregation platforms monetize DER flexibility through demand response, frequency regulation, and capacity markets. The value proposition of DERs increases through aggregation, improving investment economics. As VPP technology matures and market mechanisms develop, aggregated DERs capture growing market share, expanding the addressable market.
Threat:
Regulatory and policy uncertainty
Complex and evolving regulatory frameworks for DER interconnection, net metering, and market participation pose significant threats to market growth. Changing net metering policies in some regions are affecting solar PV investment economics. Interconnection requirements vary significantly across jurisdictions, creating complexity. Utility opposition to DER deployment in some markets affects policy development. Uncertainty about future incentives and market rules affects investment decisions. This regulatory uncertainty may slow DER deployment, particularly in regions with less supportive policy environments.
Covid-19 Impact:
The COVID-19 pandemic had a mixed impact on the distributed energy resource market. Initial disruptions included supply chain interruptions, project delays, and reduced investment during economic uncertainty. However, the pandemic accelerated focus on energy resilience and grid reliability. Remote work increased residential energy consumption and interest in backup power. Government stimulus packages included renewable energy and infrastructure investment. Post-pandemic, renewable energy and DER investment have accelerated, with growing focus on energy resilience and decarbonization.
The Solar Photovoltaic (PV) segment is expected to be the largest during the forecast period
The Solar Photovoltaic (PV) segment is expected to account for the largest market share during the forecast period, driven by the dramatic cost reduction in solar PV technology, widespread availability, and broad applicability across residential, commercial, and industrial segments. Solar PV is the most deployed DER technology globally, representing a substantial portion of distributed generation capacity. The segment benefits from strong policy support including tax incentives, net metering, and renewable portfolio standards. Solar PV systems have modular, scalable designs suitable for diverse applications. As solar PV deployment continues expanding globally, this resource type maintains the largest segment share throughout the forecast period.
The Hybrid Distributed Energy Resources segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Hybrid Distributed Energy Resources segment is predicted to witness the highest growth rate, fueled by the growing adoption of solar-plus-storage systems, increasing demand for energy resilience, and the enhanced value proposition of hybrid systems. Hybrid systems combine multiple DER types including renewable generation and storage, providing grid independence, backup power, and optimized energy economics. The segment benefits from declining battery costs and increasing integration of renewables and storage. As energy resilience and self-sufficiency become priorities, hybrid DER configurations deliver the fastest configuration segment growth.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, supported by strong renewable energy policies, growing adoption of distributed generation, and significant investment in grid modernization. The United States leads regional growth with substantial DER deployment across residential, commercial, and utility segments. Federal and state policies support solar PV, battery storage, and demand response adoption. Strong financing infrastructure and project development ecosystem support market growth. With established policies and continued investment, North America maintains its dominant market position.
Region with highest CAGR:
Over the forecast period, the Asia-Pacific region is anticipated to exhibit the highest CAGR, driven by rapid renewable energy deployment, urbanization, and increasing energy demand across countries including China, India, Japan, and Southeast Asia. The region's large and growing energy demand creates substantial opportunities for DER deployment. Government renewable energy targets and distributed generation policies are accelerating. Rising energy resilience and reliability concerns support market growth. As DER adoption expands across the region, Asia Pacific delivers the fastest distributed energy resource market growth globally.
Key players in the market
Some of the key players in Distributed Energy Resource Market include Schneider Electric SE, Siemens AG, ABB Ltd., Eaton Corporation plc, General Electric Company, Tesla, Inc., Enphase Energy, Inc., Sunrun Inc., NextEra Energy, Inc., Generac Holdings Inc., Fluence Energy, Inc., Stem, Inc., AutoGrid Systems, Inc., Sunnova Energy International Inc., Bloom Energy Corporation, Honeywell International Inc., Wärtsilä Corporation, and Landis+Gyr Group AG.
Key Developments:
In July 2026, Siemens and FuelCell Energy announced a strategic collaboration to integrate large-scale distributed fuel cell power generation with Siemens' Smart Infrastructure power distribution equipment, expanding modular on-site DER capabilities for commercial and industrial facilities.
In July 2026, ABB Electrification Ventures completed a strategic minority investment in UK-based software startup Gridcog, integrating advanced modeling and optimization software for industrial microgrids, distributed generation, and energy-as-a-service platforms into ABB's digital services portfolio.
In May 2026, Fluence introduced its high-density Smartstack BESS platform, featuring modular control architectures that separate battery packs from power electronics to accelerate commercial microgrid installations.
In February 2026, Sunrun announced that customer participation in its 17 distributed power plant programs grew fivefold in 2025, deploying over 18 GWh of dispatchable energy from more than 217,000 enrolled home battery systems to support regional grids during extreme demand spikes.
Resource Types Covered:
• Distributed Energy Generation
• Energy Storage
• Flexible Loads and Demand Response
• Electric Vehicle Resources
• Other Distributed Energy Resources
Configurations Covered:
• Standalone Distributed Energy Resources
• Hybrid Distributed Energy Resources
• Aggregated Distributed Energy Resources
Metering Configurations Covered:
• Behind-the-Meter (BTM)
• Front-of-the-Meter (FTM)
Capacities Covered:
• Up to 100 kW
• Above 100 kW to 1 MW
• Above 1 MW to 10 MW
• Above 10 MW
Ownership Models Covered:
• Customer-Owned
• Utility-Owned
• Third-Party-Owned
• Aggregator-Owned and Managed
• Community-Owned
Applications Covered:
• On-Site Power Generation
• Self-Consumption and Energy Cost Reduction
• Backup and Resilience
• Peak Demand Management
• Energy Arbitrage
• Demand Response
• Grid Balancing and Ancillary Services
• Renewable Energy Integration
• Distribution Grid Support
• Transmission Deferral and Capacity Support
End Users Covered:
• Residential
• Commercial
• Industrial
• Utilities
• Government and Public Infrastructure
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Distributed Energy Resource Market, By Resource Type
5.1 Distributed Energy Generation
5.1.1 Solar Photovoltaic (PV)
5.1.2 Distributed Wind
5.1.3 Combined Heat and Power (CHP)
5.1.4 Fuel Cells
5.1.5 Small Hydropower
5.1.6 Other Distributed Generation Resources
5.2 Energy Storage
5.2.1 Battery Energy Storage
5.2.2 Thermal Energy Storage
5.2.3 Other Energy Storage Resources
5.3 Flexible Loads and Demand Response
5.3.1 Smart HVAC Systems
5.3.2 Smart Water Heating
5.3.3 Smart Appliances
5.3.4 Industrial Load Flexibility
5.3.5 Other Flexible Loads
5.4 Electric Vehicle Resources
5.4.1 EV Charging Systems
5.4.2 Vehicle-to-Home (V2H)
5.4.3 Vehicle-to-Building (V2B)
5.4.4 Vehicle-to-Grid (V2G)
5.5 Other Distributed Energy Resources
6 Global Distributed Energy Resource Market, By Configuration
6.1 Standalone Distributed Energy Resources
6.2 Hybrid Distributed Energy Resources
6.2.1 Solar-Plus-Storage Systems
6.2.2 Solar-Plus-Generator Systems
6.2.3 Renewable Energy and Storage Hybrid Systems
6.2.4 Multi-Resource Hybrid Systems
6.3 Aggregated Distributed Energy Resources
6.3.1 Virtual Power Plants (VPPs)
6.3.2 Demand Response Aggregations
6.3.3 Distributed Storage Aggregations
6.3.4 Distributed Generation Aggregations
6.3.5 Hybrid DER Aggregations
7 Global Distributed Energy Resource Market, By Metering Configuration
7.1 Behind-the-Meter (BTM)
7.2 Front-of-the-Meter (FTM)
8 Global Distributed Energy Resource Market, By Capacity
8.1 Up to 100 kW
8.2 Above 100 kW to 1 MW
8.3 Above 1 MW to 10 MW
8.4 Above 10 MW
9 Global Distributed Energy Resource Market, By Ownership Model
9.1 Customer-Owned
9.2 Utility-Owned
9.3 Third-Party-Owned
9.4 Aggregator-Owned and Managed
9.5 Community-Owned
10 Global Distributed Energy Resource Market, By Application
10.1 On-Site Power Generation
10.2 Self-Consumption and Energy Cost Reduction
10.3 Backup and Resilience
10.4 Peak Demand Management
10.5 Energy Arbitrage
10.6 Demand Response
10.7 Grid Balancing and Ancillary Services
10.8 Renewable Energy Integration
10.9 Distribution Grid Support
10.10 Transmission Deferral and Capacity Support
11 Global Distributed Energy Resource Market, By End User
11.1 Residential
11.2 Commercial
11.3 Industrial
11.4 Utilities
11.5 Government and Public Infrastructure
12 Global Distributed Energy Resource Market, By Geography
12.1 North America
12.1.1 United States
12.1.2 Canada
12.1.3 Mexico
12.2 Europe
12.2.1 United Kingdom
12.2.2 Germany
12.2.3 France
12.2.4 Italy
12.2.5 Spain
12.2.6 Netherlands
12.2.7 Belgium
12.2.8 Sweden
12.2.9 Switzerland
12.2.10 Poland
12.2.11 Rest of Europe
12.3 Asia Pacific
12.3.1 China
12.3.2 Japan
12.3.3 India
12.3.4 South Korea
12.3.5 Australia
12.3.6 Indonesia
12.3.7 Thailand
12.3.8 Malaysia
12.3.9 Singapore
12.3.10 Vietnam
12.3.11 Rest of Asia Pacific
12.4 South America
12.4.1 Brazil
12.4.2 Argentina
12.4.3 Colombia
12.4.4 Chile
12.4.5 Peru
12.4.6 Rest of South America
12.5 Rest of the World (RoW)
12.5.1 Middle East
12.5.1.1 Saudi Arabia
12.5.1.2 United Arab Emirates
12.5.1.3 Qatar
12.5.1.4 Israel
12.5.1.5 Rest of Middle East
12.5.2 Africa
12.5.2.1 South Africa
12.5.2.2 Egypt
12.5.2.3 Morocco
12.5.2.4 Rest of Africa
13 Strategic Market Intelligence
13.1 Industry Value Network and Supply Chain Assessment
13.2 White-Space and Opportunity Mapping
13.3 Product Evolution and Market Life Cycle Analysis
13.4 Channel, Distributor, and Go-to-Market Assessment
14 Industry Developments and Strategic Initiatives
14.1 Mergers and Acquisitions
14.2 Partnerships, Alliances, and Joint Ventures
14.3 New Product Launches and Certifications
14.4 Capacity Expansion and Investments
14.5 Other Strategic Initiatives
15 Company Profiles
15.1 Schneider Electric SE
15.2 Siemens AG
15.3 ABB Ltd.
15.4 Eaton Corporation plc
15.5 General Electric Company
15.6 Tesla, Inc.
15.7 Enphase Energy, Inc.
15.8 Sunrun Inc.
15.9 NextEra Energy, Inc.
15.10 Generac Holdings Inc.
15.11 Fluence Energy, Inc.
15.12 Stem, Inc.
15.13 AutoGrid Systems, Inc.
15.14 Sunnova Energy International Inc.
15.15 Bloom Energy Corporation
15.16 Honeywell International Inc.
15.17 Wärtsilä Corporation
15.18 Landis+Gyr Group AG
List of Tables
1 Global Distributed Energy Resource Market Outlook, By Region (2023–2034) ($MN)
2 Global Distributed Energy Resource Market Outlook, By Resource Type (2023–2034) ($MN)
3 Global Distributed Energy Resource Market Outlook, By Distributed Energy Generation (2023–2034) ($MN)
4 Global Distributed Energy Resource Market Outlook, By Solar Photovoltaic (PV) (2023–2034) ($MN)
5 Global Distributed Energy Resource Market Outlook, By Distributed Wind (2023–2034) ($MN)
6 Global Distributed Energy Resource Market Outlook, By Combined Heat and Power (CHP) (2023–2034) ($MN)
7 Global Distributed Energy Resource Market Outlook, By Fuel Cells (2023–2034) ($MN)
8 Global Distributed Energy Resource Market Outlook, By Small Hydropower (2023–2034) ($MN)
9 Global Distributed Energy Resource Market Outlook, By Other Distributed Generation Resources (2023–2034) ($MN)
10 Global Distributed Energy Resource Market Outlook, By Energy Storage (2023–2034) ($MN)
11 Global Distributed Energy Resource Market Outlook, By Battery Energy Storage (2023–2034) ($MN)
12 Global Distributed Energy Resource Market Outlook, By Thermal Energy Storage (2023–2034) ($MN)
13 Global Distributed Energy Resource Market Outlook, By Other Energy Storage Resources (2023–2034) ($MN)
14 Global Distributed Energy Resource Market Outlook, By Flexible Loads and Demand Response (2023–2034) ($MN)
15 Global Distributed Energy Resource Market Outlook, By Smart HVAC Systems (2023–2034) ($MN)
16 Global Distributed Energy Resource Market Outlook, By Smart Water Heating (2023–2034) ($MN)
17 Global Distributed Energy Resource Market Outlook, By Smart Appliances (2023–2034) ($MN)
18 Global Distributed Energy Resource Market Outlook, By Industrial Load Flexibility (2023–2034) ($MN)
19 Global Distributed Energy Resource Market Outlook, By Other Flexible Loads (2023–2034) ($MN)
20 Global Distributed Energy Resource Market Outlook, By Electric Vehicle Resources (2023–2034) ($MN)
21 Global Distributed Energy Resource Market Outlook, By EV Charging Systems (2023–2034) ($MN)
22 Global Distributed Energy Resource Market Outlook, By Vehicle-to-Home (V2H) (2023–2034) ($MN)
23 Global Distributed Energy Resource Market Outlook, By Vehicle-to-Building (V2B) (2023–2034) ($MN)
24 Global Distributed Energy Resource Market Outlook, By Vehicle-to-Grid (V2G) (2023–2034) ($MN)
25 Global Distributed Energy Resource Market Outlook, By Other Distributed Energy Resources (2023–2034) ($MN)
26 Global Distributed Energy Resource Market Outlook, By Configuration (2023–2034) ($MN)
27 Global Distributed Energy Resource Market Outlook, By Standalone Distributed Energy Resources (2023–2034) ($MN)
28 Global Distributed Energy Resource Market Outlook, By Hybrid Distributed Energy Resources (2023–2034) ($MN)
29 Global Distributed Energy Resource Market Outlook, By Solar-Plus-Storage Systems (2023–2034) ($MN)
30 Global Distributed Energy Resource Market Outlook, By Solar-Plus-Generator Systems (2023–2034) ($MN)
31 Global Distributed Energy Resource Market Outlook, By Renewable Energy and Storage Hybrid Systems (2023–2034) ($MN)
32 Global Distributed Energy Resource Market Outlook, By Multi-Resource Hybrid Systems (2023–2034) ($MN)
33 Global Distributed Energy Resource Market Outlook, By Aggregated Distributed Energy Resources (2023–2034) ($MN)
34 Global Distributed Energy Resource Market Outlook, By Virtual Power Plants (VPPs) (2023–2034) ($MN)
35 Global Distributed Energy Resource Market Outlook, By Demand Response Aggregations (2023–2034) ($MN)
36 Global Distributed Energy Resource Market Outlook, By Distributed Storage Aggregations (2023–2034) ($MN)
37 Global Distributed Energy Resource Market Outlook, By Distributed Generation Aggregations (2023–2034) ($MN)
38 Global Distributed Energy Resource Market Outlook, By Hybrid DER Aggregations (2023–2034) ($MN)
39 Global Distributed Energy Resource Market Outlook, By Metering Configuration (2023–2034) ($MN)
40 Global Distributed Energy Resource Market Outlook, By Behind-the-Meter (BTM) (2023–2034) ($MN)
41 Global Distributed Energy Resource Market Outlook, By Front-of-the-Meter (FTM) (2023–2034) ($MN)
42 Global Distributed Energy Resource Market Outlook, By Capacity (2023–2034) ($MN)
43 Global Distributed Energy Resource Market Outlook, By Up to 100 kW (2023–2034) ($MN)
44 Global Distributed Energy Resource Market Outlook, By Above 100 kW to 1 MW (2023–2034) ($MN)
45 Global Distributed Energy Resource Market Outlook, By Above 1 MW to 10 MW (2023–2034) ($MN)
46 Global Distributed Energy Resource Market Outlook, By Above 10 MW (2023–2034) ($MN)
47 Global Distributed Energy Resource Market Outlook, By Ownership Model (2023–2034) ($MN)
48 Global Distributed Energy Resource Market Outlook, By Customer-Owned (2023–2034) ($MN)
49 Global Distributed Energy Resource Market Outlook, By Utility-Owned (2023–2034) ($MN)
50 Global Distributed Energy Resource Market Outlook, By Third-Party-Owned (2023–2034) ($MN)
51 Global Distributed Energy Resource Market Outlook, By Aggregator-Owned and Managed (2023–2034) ($MN)
52 Global Distributed Energy Resource Market Outlook, By Community-Owned (2023–2034) ($MN)
53 Global Distributed Energy Resource Market Outlook, By Application (2023–2034) ($MN)
54 Global Distributed Energy Resource Market Outlook, By On-Site Power Generation (2023–2034) ($MN)
55 Global Distributed Energy Resource Market Outlook, By Self-Consumption and Energy Cost Reduction (2023–2034) ($MN)
56 Global Distributed Energy Resource Market Outlook, By Backup and Resilience (2023–2034) ($MN)
57 Global Distributed Energy Resource Market Outlook, By Peak Demand Management (2023–2034) ($MN)
58 Global Distributed Energy Resource Market Outlook, By Energy Arbitrage (2023–2034) ($MN)
59 Global Distributed Energy Resource Market Outlook, By Demand Response (2023–2034) ($MN)
60 Global Distributed Energy Resource Market Outlook, By Grid Balancing and Ancillary Services (2023–2034) ($MN)
61 Global Distributed Energy Resource Market Outlook, By Renewable Energy Integration (2023–2034) ($MN)
62 Global Distributed Energy Resource Market Outlook, By Distribution Grid Support (2023–2034) ($MN)
63 Global Distributed Energy Resource Market Outlook, By Transmission Deferral and Capacity Support (2023–2034) ($MN)
64 Global Distributed Energy Resource Market Outlook, By End User (2023–2034) ($MN)
65 Global Distributed Energy Resource Market Outlook, By Residential (2023–2034) ($MN)
66 Global Distributed Energy Resource Market Outlook, By Commercial (2023–2034) ($MN)
67 Global Distributed Energy Resource Market Outlook, By Industrial (2023–2034) ($MN)
68 Global Distributed Energy Resource Market Outlook, By Utilities (2023–2034) ($MN)
69 Global Distributed Energy Resource Market Outlook, By Government and Public Infrastructure (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
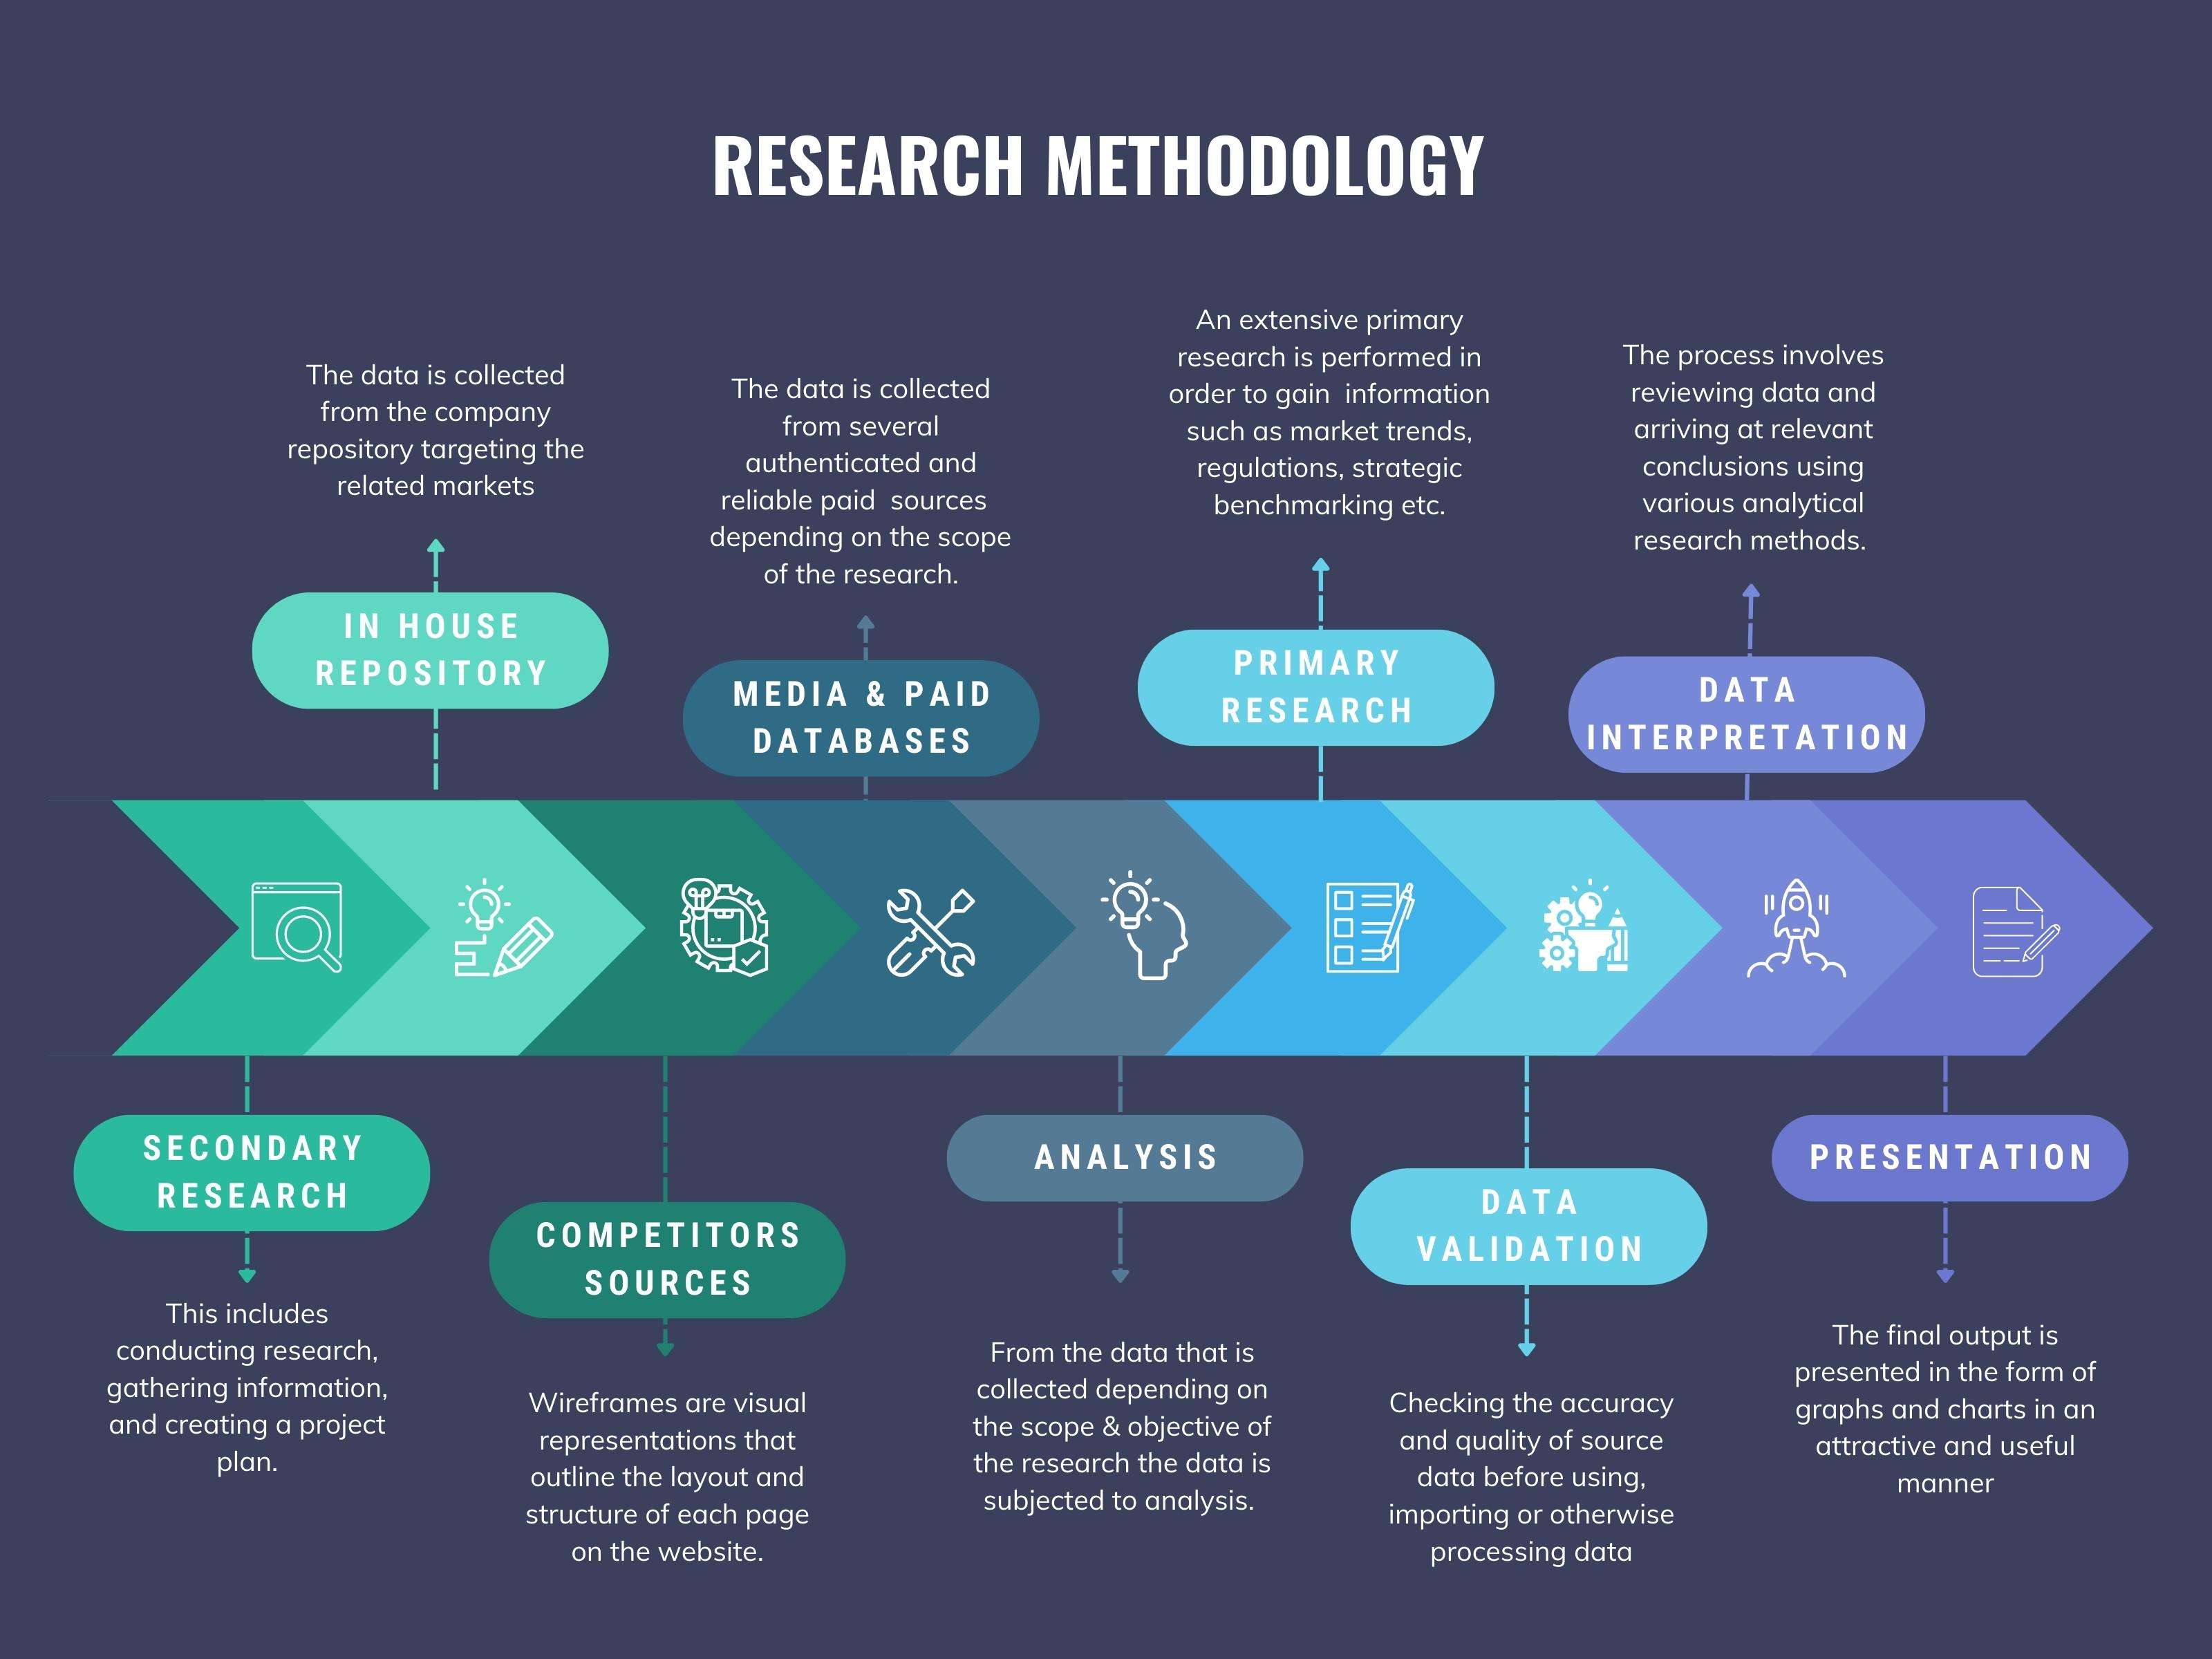
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.