Distributed Solar Market
Distributed Solar Market Forecasts to 2034 - Global Analysis By System Type (Rooftop Solar PV, Ground-Mounted Distributed Solar, Solar Carports and Canopies, Building-Integrated Photovoltaics), Capacity / Customer Class, Component, Business Model, End User, and By Geography
Market Dynamics:
Driver:
Growing demand for decentralized renewable electricity generation
Increasing demand for clean electricity and greater control over energy expenditure are major drivers of the distributed solar market. Residential consumers, commercial establishments, and industrial facilities are installing solar PV systems to generate electricity at the point of consumption, reduce exposure to conventional electricity prices, and improve energy independence. Rooftop installations enable property owners to use existing building surfaces without requiring extensive additional land. Government incentives, net-metering arrangements, renewable energy targets, and corporate decarbonization commitments further encourage deployment in many markets. Additionally, improvements in solar module efficiency, inverter technology, installation practices, and system monitoring are supporting wider adoption. As electricity demand grows and distributed energy resources become increasingly important, distributed solar is gaining traction across multiple customer segments.
Restraint:
High upfront investment and grid interconnection constraints
The initial cost of installing distributed solar systems remains a significant barrier, particularly for residential consumers and small businesses with limited access to affordable financing. Although solar installations can reduce electricity expenditure over time, equipment purchases, installation, permitting, and electrical upgrades can increase upfront costs. Grid interconnection procedures, restrictions on system size, delays in approvals, and variations in net-metering policies can further affect project economics. In addition, customers without suitable rooftops, adequate sunlight exposure, or property ownership may face difficulties adopting individual systems. Financing uncertainty and changes in electricity export compensation can also influence investment decisions, extending payback periods and limiting deployment in markets with less supportive regulatory frameworks.
Opportunity:
Integration of battery storage and innovative solar financing models
The integration of battery energy storage with distributed solar presents substantial opportunities for market participants. Storage systems enable consumers to use solar electricity beyond daylight hours, improve backup power availability, and manage electricity consumption according to tariff structures. Advanced inverters, energy management software, smart meters, and monitoring platforms can further optimize generation, consumption, and grid interaction. Innovative financing arrangements, including solar leasing, power purchase agreements, and community solar subscriptions, can expand access for consumers unable or unwilling to make large upfront investments. Additionally, solar carports, building-integrated photovoltaics, and distributed installations at commercial and industrial facilities create opportunities to utilize underused surfaces. As distributed energy management develops, combined solar, storage, and digital solutions can support broader customer adoption.
Threat:
Policy uncertainty, supply chain volatility, and grid integration challenges
The distributed solar market faces risks associated with changing government incentives, electricity export compensation, import duties, and local installation requirements. Reductions in subsidies or unfavorable net-metering changes can affect project affordability and investment returns. Supply chain volatility, fluctuations in module and inverter prices, trade restrictions, and dependence on geographically concentrated manufacturing can also influence equipment availability and project costs. Moreover, high concentrations of rooftop PV generation can create voltage management, reverse power flow, and distribution network balancing challenges in areas with limited grid modernization. Competition among manufacturers and installers may further compress margins, while inconsistent installation quality can increase maintenance costs and reduce customer confidence. Addressing these risks requires reliable supply chains, adaptable commercial models, and improved coordination between distributed generation and electricity networks.
Covid-19 Impact:
The COVID-19 pandemic affected the distributed solar market through installation delays, supply chain disruptions, workforce restrictions, and uncertainty in residential and commercial investment decisions. Restrictions on movement and interruptions in manufacturing affected the availability of solar modules, inverters, and other system components. Some commercial projects were postponed as businesses reassessed capital expenditure during periods of economic uncertainty. However, the pandemic also reinforced interest in energy resilience, decentralized electricity generation, and long-term energy cost management. Following the initial disruptions, digital sales channels, remote system design, and improved installation coordination helped market participants adapt their operations. Subsequent investment in renewable electricity, residential rooftop solar, and commercial energy cost reduction has supported continued market development.
The Rooftop Solar PV segment is expected to be the largest during the forecast period
The Rooftop Solar PV segment is expected to account for the largest market share during the forecast period, supported by its applicability across residential, commercial, industrial, and institutional buildings. Rooftop systems use existing structures to generate electricity near the point of consumption, reducing the need for dedicated land and extensive transmission infrastructure. Residential installations benefit from household electricity savings and government-supported adoption programs, while commercial and industrial users can deploy larger systems to manage operating expenses and meet sustainability targets. Improvements in module efficiency, inverter performance, installation processes, and monitoring technologies further support adoption. The availability of customer-owned, leased, and power purchase agreement models also broadens access to rooftop solar across different consumer groups.
The Commercial and Industrial segment is expected to witness strong growth during the forecast period
The Commercial and Industrial segment is expected to experience strong growth as businesses seek to reduce electricity expenditure, improve energy security, and meet corporate sustainability objectives. Warehouses, manufacturing facilities, shopping centers, offices, logistics centers, and other large properties often provide substantial rooftop or onsite installation space. Distributed solar can help these facilities offset daytime electricity consumption and reduce exposure to grid electricity price fluctuations. Power purchase agreements and solar leasing arrangements can also enable businesses to adopt solar without bearing the full upfront capital cost. In addition, integration with battery storage and energy management systems can improve self-consumption and support operational resilience, strengthening the attractiveness of distributed solar for commercial and industrial customers.
Region with largest share:
During the forecast period, Asia Pacific is expected to hold the largest share of the Global Distributed Solar Market, supported by extensive solar deployment, large electricity-consuming populations, strong manufacturing capabilities, and government initiatives promoting renewable energy. China is a major contributor through its substantial photovoltaic manufacturing base and extensive deployment of distributed solar systems. India is also expanding rooftop solar adoption through residential incentive programs and growing commercial and industrial demand. Japan, Australia, South Korea, and Southeast Asian countries provide additional opportunities through rooftop installations, energy cost management, and renewable energy targets. The region's combination of large customer markets, established solar supply chains, and continued investment in decentralized electricity generation supports its leading market position.
Region with highest CAGR:
North America is expected to register strong growth during the forecast period, driven by demand for residential solar, commercial rooftop installations, battery storage integration, and alternative financing arrangements. The United States represents a major market for distributed solar through residential solar leasing, power purchase agreements, and customer-owned systems. Rising interest in backup power and home energy management is also encouraging the integration of solar generation with battery storage and smart inverters. Commercial and industrial facilities are adopting distributed solar to manage electricity expenditure and meet sustainability commitments. In Canada and Mexico, opportunities arise from renewable energy development, electricity cost management, and growing interest in onsite generation. Supportive policies, financing innovation, and improvements in distributed energy management are expected to contribute to regional growth.
Key players in the market
Some of the key players in the Global Distributed Solar Market include Sunrun Inc., Sunnova Energy International Inc., Enphase Energy, Inc., SolarEdge Technologies, Inc., First Solar, Inc., LONGi Green Energy Technology Co., Ltd., JinkoSolar Holding Co., Ltd., Trina Solar Co., Ltd., Canadian Solar Inc., Tata Power Solar Systems Limited, Waaree Energies Limited, Adani Solar, SMA Solar Technology AG, Huawei Digital Power, and Brookfield Renewable Partners L.P.
Key Developments:
In October 2026, Sunrun Inc. reported record residential distributed power plant dispatches, delivering 669 megawatts on October 5 and 745 megawatts on October 6 to support California's electricity grid during a prolonged heat wave. The development highlights the growing role of residential solar and battery systems in distributed energy resources and grid flexibility.
In October 2026, Enphase Energy, Inc. began production shipments of its IQ Gateway Fusion in India. The system combines gateway and relay functions with a built-in power socket and supports solar-powered operation of essential appliances during daytime grid outages, expanding the company's distributed solar energy management offerings.
In September 2026, Sunrun Inc. and SPAN expanded their partnership to combine residential solar and battery systems with distributed computing infrastructure. The collaboration is intended to support behind-the-meter distributed computing deployments and demonstrates the potential for residential energy assets to support emerging electricity-intensive applications.
In August 2026, Enphase Energy, Inc. expanded support for its IQ Battery 10C and whole-home backup solutions to existing third-party solar systems across the United States and Canada. The development enables eligible homeowners to add battery storage and energy management capabilities without replacing their existing solar installations.
System Types Covered:
• Rooftop Solar PV
• Ground-Mounted Distributed Solar
• Solar Carports and Canopies
• Building-Integrated Photovoltaics
Capacity / Customer Classes Covered:
• Residential
• Commercial and Industrial
• Community and Small Distributed Projects
Components Covered:
• Solar Modules
• Inverters
• Mounting Structures
• Balance of System
• Monitoring and Control
Business Models Covered:
• Customer-Owned Systems
• Solar Leasing
• Power Purchase Agreements
• Community Solar Subscriptions
End Users Covered:
• Residential
• Commercial
• Industrial
• Public and Institutional
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
• Market share assessments for regional and country-level segments
• Strategic recommendations for new entrants
• Covers market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032, and 2034
• Market trends, including drivers, constraints, opportunities, threats, challenges, investment opportunities, and recommendations
• Strategic recommendations for key business segments based on market estimations
• Competitive landscape mapping and assessment of key industry trends
• Company profiling with detailed strategies, financials, and recent developments
• Supply chain trends and assessment of the latest technological advancements
Free Customization Offerings:
All customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, forecasts, and CAGR of any prominent country as per the client's interest (subject to feasibility assessment)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Distributed Solar Market, By System Type
5.1 Rooftop Solar PV
5.2 Ground-Mounted Distributed Solar
5.3 Solar Carports and Canopies
5.4 Building-Integrated Photovoltaics
6 Global Distributed Solar Market, By Capacity / Customer Class
6.1 Residential
6.2 Commercial and Industrial
6.3 Community and Small Distributed Projects
7 Global Distributed Solar Market, By Component
7.1 Solar Modules
7.2 Inverters
7.3 Mounting Structures
7.4 Balance of System
7.5 Monitoring and Control
8 Global Distributed Solar Market, By Business Model
8.1 Customer-Owned Systems
8.2 Solar Leasing
8.3 Power Purchase Agreements
8.4 Community Solar Subscriptions
9 Global Distributed Solar Market, By End User
9.1 Residential
9.2 Commercial
9.3 Industrial
9.4 Public and Institutional
10 Global Distributed Solar Market, By Geography
10.1 North America
10.1.1 United States
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 United Kingdom
10.2.2 Germany
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Netherlands
10.2.7 Belgium
10.2.8 Sweden
10.2.9 Switzerland
10.2.10 Poland
10.2.11 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 Japan
10.3.3 India
10.3.4 South Korea
10.3.5 Australia
10.3.6 Indonesia
10.3.7 Thailand
10.3.8 Malaysia
10.3.9 Singapore
10.3.10 Vietnam
10.3.11 Rest of Asia Pacific
10.4 South America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Colombia
10.4.4 Chile
10.4.5 Peru
10.4.6 Rest of South America
10.5 Rest of the World (RoW)
10.5.1 Middle East
10.5.1.1 Saudi Arabia
10.5.1.2 United Arab Emirates
10.5.1.3 Qatar
10.5.1.4 Israel
10.5.1.5 Rest of Middle East
10.5.2 Africa
10.5.2.1 South Africa
10.5.2.2 Egypt
10.5.2.3 Morocco
10.5.2.4 Rest of Africa
11 Strategic Market Intelligence
11.1 Industry Value Network and Supply Chain Assessment
11.2 White-Space and Opportunity Mapping
11.3 Product Evolution and Market Life Cycle Analysis
11.4 Channel, Distributor, and Go-to-Market Assessment
12 Industry Developments and Strategic Initiatives
12.1 Mergers and Acquisitions
12.2 Partnerships, Alliances, and Joint Ventures
12.3 New Product Launches and Certifications
12.4 Capacity Expansion and Investments
12.5 Other Strategic Initiatives
13 Company Profiles
13.1 Sunrun Inc.
13.2 Sunnova Energy International Inc.
13.3 Enphase Energy, Inc.
13.4 SolarEdge Technologies, Inc.
13.5 First Solar, Inc.
13.6 LONGi Green Energy Technology Co., Ltd.
13.7 JinkoSolar Holding Co., Ltd.
13.8 Trina Solar Co., Ltd.
13.9 Canadian Solar Inc.
13.10 Tata Power Solar Systems Limited
13.11 Waaree Energies Limited
13.12 Adani Solar
13.13 SMA Solar Technology AG
13.14 Huawei Digital Power
13.15 Brookfield Renewable Partners L.P.
List of Tables
1 Global Distributed Solar Market Outlook, By Region (2023–2034) ($MN)
2 Global Distributed Solar Market Outlook, By System Type (2023–2034) ($MN)
3 Global Distributed Solar Market Outlook, By Rooftop Solar PV (2023–2034) ($MN)
4 Global Distributed Solar Market Outlook, By Ground-Mounted Distributed Solar (2023–2034) ($MN)
5 Global Distributed Solar Market Outlook, By Solar Carports and Canopies (2023–2034) ($MN)
6 Global Distributed Solar Market Outlook, By Building-Integrated Photovoltaics (2023–2034) ($MN)
7 Global Distributed Solar Market Outlook, By Capacity / Customer Class (2023–2034) ($MN)
8 Global Distributed Solar Market Outlook, By Residential (2023–2034) ($MN)
9 Global Distributed Solar Market Outlook, By Commercial and Industrial (2023–2034) ($MN)
10 Global Distributed Solar Market Outlook, By Community and Small Distributed Projects (2023–2034) ($MN)
11 Global Distributed Solar Market Outlook, By Component (2023–2034) ($MN)
12 Global Distributed Solar Market Outlook, By Solar Modules (2023–2034) ($MN)
13 Global Distributed Solar Market Outlook, By Inverters (2023–2034) ($MN)
14 Global Distributed Solar Market Outlook, By Mounting Structures (2023–2034) ($MN)
15 Global Distributed Solar Market Outlook, By Balance of System (2023–2034) ($MN)
16 Global Distributed Solar Market Outlook, By Monitoring and Control (2023–2034) ($MN)
17 Global Distributed Solar Market Outlook, By Business Model (2023–2034) ($MN)
18 Global Distributed Solar Market Outlook, By Customer-Owned Systems (2023–2034) ($MN)
19 Global Distributed Solar Market Outlook, By Solar Leasing (2023–2034) ($MN)
20 Global Distributed Solar Market Outlook, By Power Purchase Agreements (2023–2034) ($MN)
21 Global Distributed Solar Market Outlook, By Community Solar Subscriptions (2023–2034) ($MN)
22 Global Distributed Solar Market Outlook, By End User (2023–2034) ($MN)
23 Global Distributed Solar Market Outlook, By Residential (2023–2034) ($MN)
24 Global Distributed Solar Market Outlook, By Commercial (2023–2034) ($MN)
25 Global Distributed Solar Market Outlook, By Industrial (2023–2034) ($MN)
26 Global Distributed Solar Market Outlook, By Public and Institutional (2023–2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
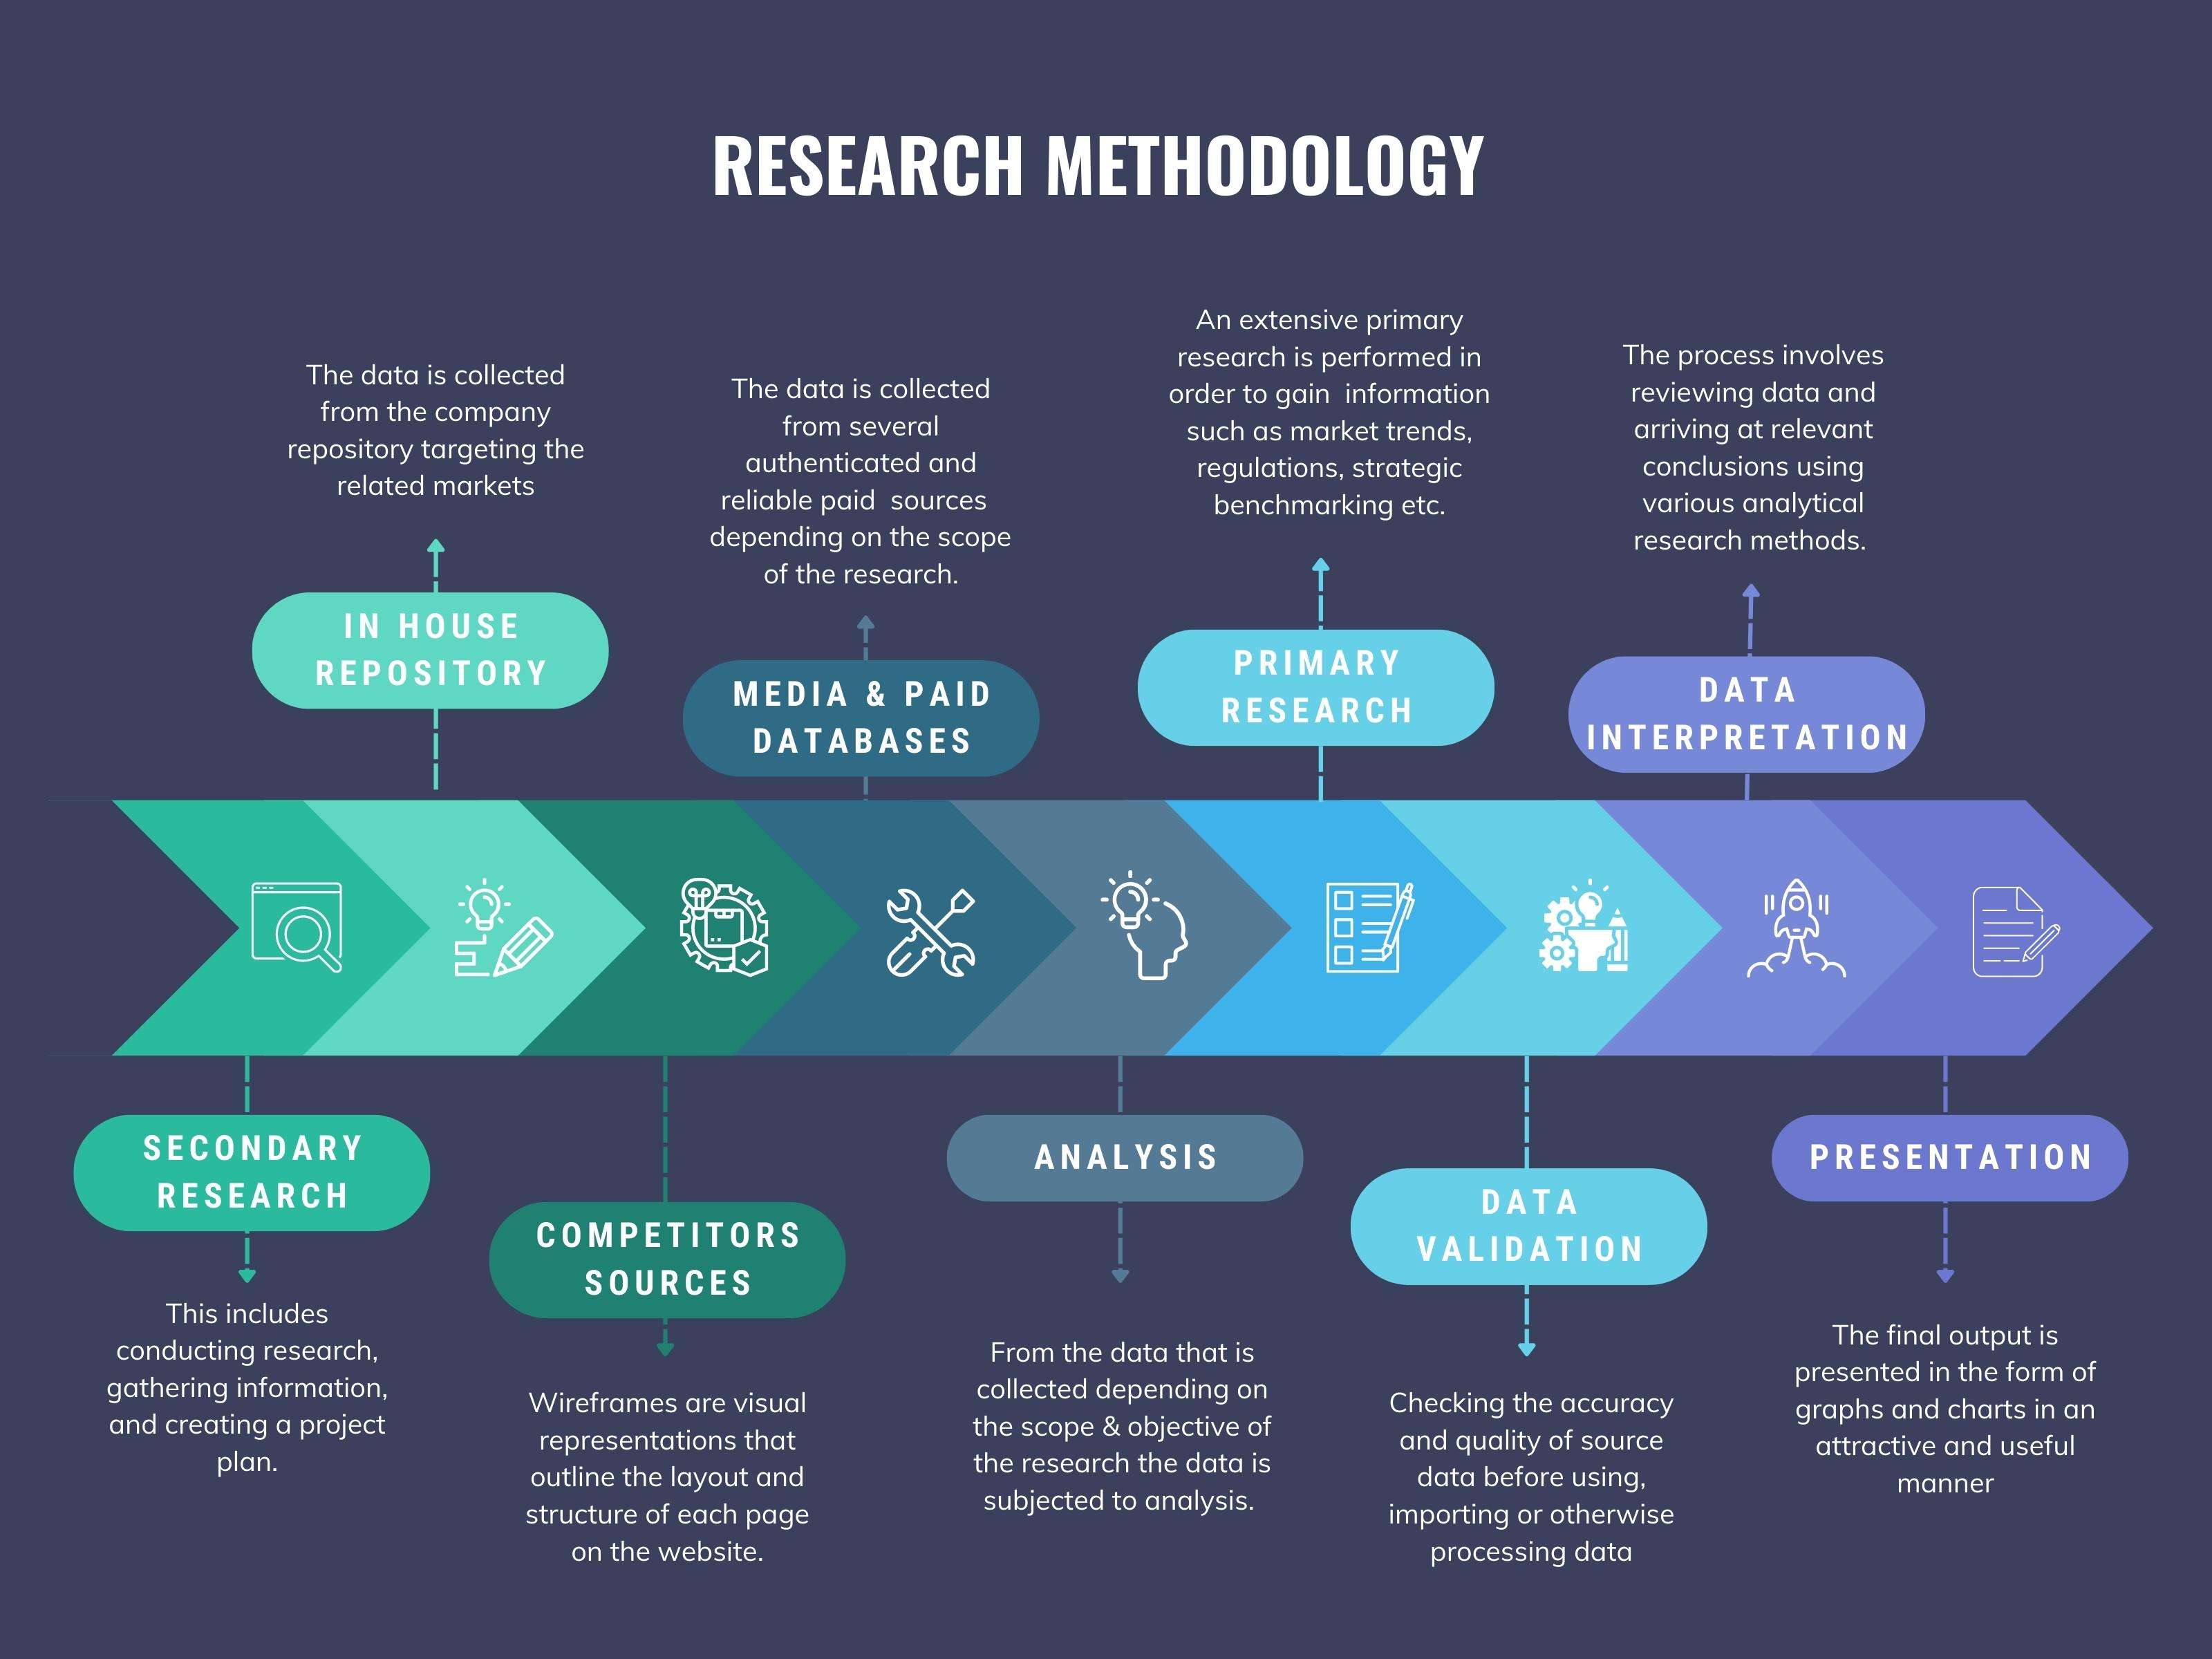
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.