Fuel Cell Power Generation Market
Fuel Cell Power Generation Market Forecasts To 2034 - Global Analysis By Fuel Cell Type (Proton Exchange Membrane Fuel Cells, Solid Oxide Fuel Cells, Phosphoric Acid Fuel Cells, Molten Carbonate Fuel Cells, Alkaline Fuel Cells, Direct Methanol Fuel Cells and Anion Exchange Membrane Fuel Cells), Power Capacity, Fuel Source, Power Generation Configuration, System Integration, Hydrogen Production Pathway, Generation Technology, Application, End User and By Geography
According to Stratistics MRC, the Global Fuel Cell Power Generation Market is accounted for $1.4 billion in 2026 and is expected to reach $14.4 billion by 2034 growing at a CAGR of 34.3% during the forecast period. The fuel cell power generation market is witnessing increasing adoption as businesses, utilities, and commercial establishments pursue dependable, energy-efficient, and environmentally sustainable power sources. Fuel cells produce electricity through electrochemical processes, enabling efficient generation while producing fewer emissions than traditional fossil-fuel-based systems. Rising requirements for decentralized electricity, backup power, and clean energy infrastructure are driving market growth. Investments in hydrogen supply, fuel cell innovation, and emissions-reduction programs are accelerating deployment. These systems are increasingly utilized in stationary power plants, manufacturing facilities, data centers, homes, and microgrids. Ongoing technological improvements, decreasing equipment costs, and favorable regulatory initiatives are anticipated to support market expansion during the forecast period.
Market Dynamics:
Driver:
Increasing Adoption of Distributed and Backup Power Systems
Rising requirements for dependable onsite and emergency electricity are contributing to greater adoption of fuel cell power generation technologies. These systems can generate electricity near the location where it is needed, helping users reduce reliance on centralized grids and maintain operations during grid failures. Their reliability makes them attractive for critical facilities such as hospitals, data centers, telecommunications sites, factories, and commercial buildings. Fuel cells can also be incorporated into microgrids and distributed energy systems to deliver consistent baseload or standby electricity. With organizations increasingly focused on improving energy security and preventing costly operational disruptions, spending on onsite generation solutions is growing. This demand for resilient power infrastructure should continue supporting the fuel cell market.
Restraint:
High Initial Capital and Installation Costs
The considerable upfront expenditure required for fuel cell power systems is a major factor limiting market expansion. Costs can arise from fuel cell stacks, catalysts, supporting equipment, installation, hydrogen supply infrastructure, and integration with existing electrical systems. As a result, fuel cell installations may face economic disadvantages when compared with conventional backup generators and other mature distributed generation solutions. Smaller businesses and organizations with limited investment budgets can be particularly sensitive to these high initial expenses. Additional engineering, maintenance planning, and specialized installation requirements may increase project costs further. While manufacturing improvements and larger production volumes are expected to lower expenses over time, high capital requirements remain a challenge for widespread fuel cell deployment.
Opportunity:
Emerging Applications in Remote and Off-Grid Power Systems
Off-grid and remote power requirements represent another promising growth opportunity for the fuel cell power generation market. Many isolated communities, telecommunications sites, mining facilities, military installations, islands, and remote industrial operations face challenges associated with unreliable grids or costly grid expansion. Fuel cells can provide stable electricity in these environments and can be combined with renewable generation and hydrogen storage to reduce dependence on transported diesel fuel. Their decentralized operating capability makes them well suited to locations where traditional electricity infrastructure is limited. Increasing priorities around reliable energy access, disaster preparedness, and reduced reliance on fossil-fuel-based generators may further encourage deployment. These factors can broaden the use of fuel cell systems across remote and distributed power applications.
Threat:
Public Perception and Safety Concerns Related to Hydrogen
Concerns about hydrogen safety and community acceptance may restrict the expansion of fuel cell power generation. Hydrogen requires specialized systems for safe production, transportation, storage, and use, along with appropriate monitoring, containment measures, trained operators, and regulatory controls. Any significant incident involving hydrogen infrastructure could attract public attention and create negative perceptions of fuel cell technologies. Communities may consequently oppose proposed hydrogen facilities or related infrastructure, potentially making permitting more difficult and extending development timelines. Additional safety measures can also increase project costs. Although technological advances have improved hydrogen management and safety, continued concerns about handling and storage could influence public acceptance, investment decisions, and the pace of fuel cell deployment.
Covid-19 Impact:
The COVID-19 outbreak had a short-term negative effect on the fuel cell power generation market, mainly through factory interruptions, delayed installations, workforce restrictions, and disruptions across supply networks. Reduced economic activity and lower electricity consumption also caused some companies to postpone investments in hydrogen infrastructure and other capital-intensive fuel cell projects. Hydrogen technologies faced particular difficulties because their development relies on complex supply chains and substantial financing. However, the sector remained relatively resilient, and fuel cell shipments continued despite operational challenges. As economies reopened, clean-energy recovery initiatives, hydrogen strategies, and renewed investment helped restore market momentum and strengthen prospects for future fuel cell power generation deployment.
The Proton Exchange Membrane Fuel Cells segment is expected to be the largest during the forecast period
The Proton Exchange Membrane Fuel Cells segment is expected to account for the largest market share during the forecast period, driven by its efficient performance, compact structure, quick activation, and adaptability across power-generation applications. PEMFC systems are increasingly suitable for distributed generation, backup electricity, residential installations, commercial facilities, and other stationary uses where reliable and responsive power is required. Their comparatively low operating temperature supports rapid start-up and effective response to changing electricity requirements. Ongoing advancements in membrane technology, stack longevity, system performance, and hydrogen utilization are improving their overall applicability. These advantages are expected to reinforce PEMFC technology as the leading segment in fuel cell power generation.
The Backup Power segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Backup Power segment is predicted to witness the highest growth rate, supported by rising requirements for continuous and reliable electricity across essential facilities and commercial operations. Fuel cell technologies can deliver dependable standby power during grid interruptions while providing lower emissions, quieter operation, and longer-duration performance than traditional diesel-based systems. Increasing investments in data centers, telecommunications infrastructure, hospitals, and emergency services are generating further opportunities for fuel cell backup systems. Growing concerns over power-grid disruptions and the transition toward cleaner backup alternatives are accelerating adoption. Improvements in fuel cell technology, development of hydrogen supply networks, and increasing focus on energy security are expected to further contribute to segment expansion.
Region with largest share:
During the forecast period, the Asia Pacific region is expected to hold the largest market share, supported by expanding stationary fuel cell deployment, developing hydrogen infrastructure, and rising investment in low-carbon energy solutions. Japan, South Korea, China, and India are strengthening the regional market through hydrogen initiatives, clean-energy policies, and programs focused on energy security and decarbonization. Increasing requirements for dependable distributed power across residential, commercial, industrial, and utility settings are also encouraging fuel cell adoption. Furthermore, strong regional manufacturing capabilities, technological advancements, and continued investment in fuel cell infrastructure are expected to reinforce Asia Pacific’s leading position.
Region with highest CAGR:
Over the forecast period, the North America region is anticipated to exhibit the highest CAGR, supported by increasing investments in hydrogen infrastructure, clean energy technologies, and distributed power generation. The United States and Canada are advancing hydrogen development through government initiatives, incentives, and investments in fuel cell technologies. Rising demand for reliable electricity from data centers, telecommunications facilities, healthcare institutions, and commercial infrastructure is also creating opportunities for fuel cell-based power systems. In addition, growing efforts to reduce carbon emissions, improve grid resilience, and replace conventional backup generators are encouraging adoption. These factors are expected to strengthen North America’s growth trajectory.
Key players in the market
Some of the key players in Fuel Cell Power Generation Market include Bloom Energy Corporation, FuelCell Energy, Inc., Doosan Fuel Cell Co., Ltd., Ballard Power Systems Inc., Plug Power Inc., Cummins Inc., Panasonic Holdings Corporation, Toshiba Energy Systems & Solutions Corporation, Mitsubishi Heavy Industries, Ltd., Fuji Electric Co., Ltd., SFC Energy AG, AFC Energy PLC, Ceres Power Holdings plc, POSCO ENERGY, Advent Technologies Holdings, Inc., Intelligent Energy Limited, GenCell Ltd. and Altergy Systems.
Key Developments:
In June 2026, Bloom Energy and Brookfield expanded their AI infrastructure partnership, increasing Brookfield’s financing framework from $5 billion to $25 billion. Bloom stated that the expanded funding would support the global growth of its fuel-cell partnership and accelerate power projects for AI infrastructure.
In May 2026, Panasonic Electric Works established a new fuel-cell-generator R&D site in Takatsuki, Japan, intended to strengthen co-creation among industry, government, and academia. Panasonic said the facility would address energy challenges and contribute to sustainable development by partnering with relevant stakeholders, supporting the development and commercialization of fuel-cell generator technologies.
In April 2026, Bloom Energy and Oracle expanded their strategic partnership through a master services agreement supporting up to 2.8 GW of Bloom fuel-cell capacity for Oracle’s U.S. AI and cloud infrastructure. An initial 1.2 GW was contracted and deployment was underway.
Fuel Cell Types Covered:
• Proton Exchange Membrane Fuel Cells
• Solid Oxide Fuel Cells
• Phosphoric Acid Fuel Cells
• Molten Carbonate Fuel Cells
• Alkaline Fuel Cells
• Direct Methanol Fuel Cells
• Anion Exchange Membrane Fuel Cells
Power Capacities Covered:
• Below 100 kW
• 100 kW–1 MW
• 1–5 MW
• 5–10 MW
• Above 10 MW
Fuel Sources Covered:
• Hydrogen
• Natural Gas
• Biogas
• Methanol
• Ammonia
• Other Fuels
Power Generation Configurations Covered:
• Grid-Connected
• Off-Grid
• Microgrid
• Distributed Generation
• Centralized Generation
System Integrations Covered:
• Fuel Cell–Battery Hybrid Systems
• Fuel Cell–Renewable Energy Hybrid Systems
• Fuel Cell–Energy Storage Systems
• Fuel Cell–Electrolyzer Integrated Systems
Hydrogen Production Pathways Covered:
• Green Hydrogen
• Blue Hydrogen
• Gray Hydrogen
• Other Hydrogen Pathways
Generation Technologies Covered:
• Electricity-Only Generation
• Combined Heat and Power
• Combined Cooling, Heat and Power
Applications Covered:
• Primary Power
• Backup Power
• Peak Power
• Emergency Power
• Remote Power
End Users Covered:
• Residential
• Commercial
• Industrial
• Utility
• Data Centers
• Telecommunications
• Healthcare
• Government and Defense
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Fuel Cell Power Generation Market, By Fuel Cell Type
5.1 Proton Exchange Membrane Fuel Cells
5.2 Solid Oxide Fuel Cells
5.3 Phosphoric Acid Fuel Cells
5.4 Molten Carbonate Fuel Cells
5.5 Alkaline Fuel Cells
5.6 Direct Methanol Fuel Cells
5.7 Anion Exchange Membrane Fuel Cells
6 Global Fuel Cell Power Generation Market, By Power Capacity
6.1 Below 100 kW
6.2 100 kW–1 MW
6.3 1–5 MW
6.4 5–10 MW
6.5 Above 10 MW
7 Global Fuel Cell Power Generation Market, By Fuel Source
7.1 Hydrogen
7.2 Natural Gas
7.3 Biogas
7.4 Methanol
7.5 Ammonia
7.6 Other Fuels
8 Global Fuel Cell Power Generation Market, By Power Generation Configuration
8.1 Grid-Connected
8.2 Off-Grid
8.3 Microgrid
8.4 Distributed Generation
8.5 Centralized Generation
9 Global Fuel Cell Power Generation Market, By System Integration
9.1 Fuel Cell–Battery Hybrid Systems
9.2 Fuel Cell–Renewable Energy Hybrid Systems
9.3 Fuel Cell–Energy Storage Systems
9.4 Fuel Cell–Electrolyzer Integrated Systems
10 Global Fuel Cell Power Generation Market, By Hydrogen Production Pathway
10.1 Green Hydrogen
10.2 Blue Hydrogen
10.3 Gray Hydrogen
10.4 Other Hydrogen Pathways
11 Global Fuel Cell Power Generation Market, By Generation Technology
11.1 Electricity-Only Generation
11.2 Combined Heat and Power
11.3 Combined Cooling, Heat and Power
12 Global Fuel Cell Power Generation Market, By Application
12.1 Primary Power
12.2 Backup Power
12.3 Peak Power
12.4 Emergency Power
12.5 Remote Power
13 Global Fuel Cell Power Generation Market, By End User
13.1 Residential
13.2 Commercial
13.3 Industrial
13.4 Utility
13.5 Data Centers
13.6 Telecommunications
13.7 Healthcare
13.8 Government and Defense
13.9 Other End Users
14 Global Fuel Cell Power Generation Market, By Geography
14.1 North America
14.1.1 United States
14.1.2 Canada
14.1.3 Mexico
14.2 Europe
14.2.1 United Kingdom
14.2.2 Germany
14.2.3 France
14.2.4 Italy
14.2.5 Spain
14.2.6 Netherlands
14.2.7 Belgium
14.2.8 Sweden
14.2.9 Switzerland
14.2.10 Poland
14.2.11 Rest of Europe
14.3 Asia Pacific
14.3.1 China
14.3.2 Japan
14.3.3 India
14.3.4 South Korea
14.3.5 Australia
14.3.6 Indonesia
14.3.7 Thailand
14.3.8 Malaysia
14.3.9 Singapore
14.3.10 Vietnam
14.3.11 Rest of Asia Pacific
14.4 South America
14.4.1 Brazil
14.4.2 Argentina
14.4.3 Colombia
14.4.4 Chile
14.4.5 Peru
14.4.6 Rest of South America
14.5 Rest of the World (RoW)
14.5.1 Middle East
14.5.1.1 Saudi Arabia
14.5.1.2 United Arab Emirates
14.5.1.3 Qatar
14.5.1.4 Israel
14.5.1.5 Rest of Middle East
14.5.2 Africa
14.5.2.1 South Africa
14.5.2.2 Egypt
14.5.2.3 Morocco
14.5.2.4 Rest of Africa
15 Strategic Market Intelligence
15.1 Industry Value Network and Supply Chain Assessment
15.2 White-Space and Opportunity Mapping
15.3 Product Evolution and Market Life Cycle Analysis
15.4 Channel, Distributor, and Go-to-Market Assessment
16 Industry Developments and Strategic Initiatives
16.1 Mergers and Acquisitions
16.2 Partnerships, Alliances, and Joint Ventures
16.3 New Product Launches and Certifications
16.4 Capacity Expansion and Investments
16.5 Other Strategic Initiatives
17 Company Profiles
17.1 Bloom Energy Corporation
17.2 FuelCell Energy, Inc.
17.3 Doosan Fuel Cell Co., Ltd.
17.4 Ballard Power Systems Inc.
17.5 Plug Power Inc.
17.6 Cummins Inc.
17.7 Panasonic Holdings Corporation
17.8 Toshiba Energy Systems & Solutions Corporation
17.9 Mitsubishi Heavy Industries, Ltd.
17.10 Fuji Electric Co., Ltd.
17.11 SFC Energy AG
17.12 AFC Energy PLC
17.13 Ceres Power Holdings plc
17.14 POSCO ENERGY
17.15 Advent Technologies Holdings, Inc.
17.16 Intelligent Energy Limited
17.17 GenCell Ltd.
17.18 Altergy Systems
List of Tables
1 Global Fuel Cell Power Generation Market Outlook, By Region (2023-2034) ($MN)
2 Global Fuel Cell Power Generation Market Outlook, By Fuel Cell Type (2023-2034) ($MN)
3 Global Fuel Cell Power Generation Market Outlook, By Proton Exchange Membrane Fuel Cells (2023-2034) ($MN)
4 Global Fuel Cell Power Generation Market Outlook, By Solid Oxide Fuel Cells (2023-2034) ($MN)
5 Global Fuel Cell Power Generation Market Outlook, By Phosphoric Acid Fuel Cells (2023-2034) ($MN)
6 Global Fuel Cell Power Generation Market Outlook, By Molten Carbonate Fuel Cells (2023-2034) ($MN)
7 Global Fuel Cell Power Generation Market Outlook, By Alkaline Fuel Cells (2023-2034) ($MN)
8 Global Fuel Cell Power Generation Market Outlook, By Direct Methanol Fuel Cells (2023-2034) ($MN)
9 Global Fuel Cell Power Generation Market Outlook, By Anion Exchange Membrane Fuel Cells (2023-2034) ($MN)
10 Global Fuel Cell Power Generation Market Outlook, By Power Capacity (2023-2034) ($MN)
11 Global Fuel Cell Power Generation Market Outlook, By Below 100 kW (2023-2034) ($MN)
12 Global Fuel Cell Power Generation Market Outlook, By 100 kW–1 MW (2023-2034) ($MN)
13 Global Fuel Cell Power Generation Market Outlook, By 1–5 MW (2023-2034) ($MN)
14 Global Fuel Cell Power Generation Market Outlook, By 5–10 MW (2023-2034) ($MN)
15 Global Fuel Cell Power Generation Market Outlook, By Above 10 MW (2023-2034) ($MN)
16 Global Fuel Cell Power Generation Market Outlook, By Fuel Source (2023-2034) ($MN)
17 Global Fuel Cell Power Generation Market Outlook, By Hydrogen (2023-2034) ($MN)
18 Global Fuel Cell Power Generation Market Outlook, By Natural Gas (2023-2034) ($MN)
19 Global Fuel Cell Power Generation Market Outlook, By Biogas (2023-2034) ($MN)
20 Global Fuel Cell Power Generation Market Outlook, By Methanol (2023-2034) ($MN)
21 Global Fuel Cell Power Generation Market Outlook, By Ammonia (2023-2034) ($MN)
22 Global Fuel Cell Power Generation Market Outlook, By Other Fuels (2023-2034) ($MN)
23 Global Fuel Cell Power Generation Market Outlook, By Power Generation Configuration (2023-2034) ($MN)
24 Global Fuel Cell Power Generation Market Outlook, By Grid-Connected (2023-2034) ($MN)
25 Global Fuel Cell Power Generation Market Outlook, By Off-Grid (2023-2034) ($MN)
26 Global Fuel Cell Power Generation Market Outlook, By Microgrid (2023-2034) ($MN)
27 Global Fuel Cell Power Generation Market Outlook, By Distributed Generation (2023-2034) ($MN)
28 Global Fuel Cell Power Generation Market Outlook, By Centralized Generation (2023-2034) ($MN)
29 Global Fuel Cell Power Generation Market Outlook, By System Integration (2023-2034) ($MN)
30 Global Fuel Cell Power Generation Market Outlook, By Fuel Cell–Battery Hybrid Systems (2023-2034) ($MN)
31 Global Fuel Cell Power Generation Market Outlook, By Fuel Cell–Renewable Energy Hybrid Systems (2023-2034) ($MN)
32 Global Fuel Cell Power Generation Market Outlook, By Fuel Cell–Energy Storage Systems (2023-2034) ($MN)
33 Global Fuel Cell Power Generation Market Outlook, By Fuel Cell–Electrolyzer Integrated Systems (2023-2034) ($MN)
34 Global Fuel Cell Power Generation Market Outlook, By Hydrogen Production Pathway (2023-2034) ($MN)
35 Global Fuel Cell Power Generation Market Outlook, By Green Hydrogen (2023-2034) ($MN)
36 Global Fuel Cell Power Generation Market Outlook, By Blue Hydrogen (2023-2034) ($MN)
37 Global Fuel Cell Power Generation Market Outlook, By Gray Hydrogen (2023-2034) ($MN)
38 Global Fuel Cell Power Generation Market Outlook, By Other Hydrogen Pathways (2023-2034) ($MN)
39 Global Fuel Cell Power Generation Market Outlook, By Generation Technology (2023-2034) ($MN)
40 Global Fuel Cell Power Generation Market Outlook, By Electricity-Only Generation (2023-2034) ($MN)
41 Global Fuel Cell Power Generation Market Outlook, By Combined Heat and Power (2023-2034) ($MN)
42 Global Fuel Cell Power Generation Market Outlook, By Combined Cooling, Heat and Power (2023-2034) ($MN)
43 Global Fuel Cell Power Generation Market Outlook, By Application (2023-2034) ($MN)
44 Global Fuel Cell Power Generation Market Outlook, By Primary Power (2023-2034) ($MN)
45 Global Fuel Cell Power Generation Market Outlook, By Backup Power (2023-2034) ($MN)
46 Global Fuel Cell Power Generation Market Outlook, By Peak Power (2023-2034) ($MN)
47 Global Fuel Cell Power Generation Market Outlook, By Emergency Power (2023-2034) ($MN)
48 Global Fuel Cell Power Generation Market Outlook, By Remote Power (2023-2034) ($MN)
49 Global Fuel Cell Power Generation Market Outlook, By End User (2023-2034) ($MN)
50 Global Fuel Cell Power Generation Market Outlook, By Residential (2023-2034) ($MN)
51 Global Fuel Cell Power Generation Market Outlook, By Commercial (2023-2034) ($MN)
52 Global Fuel Cell Power Generation Market Outlook, By Industrial (2023-2034) ($MN)
53 Global Fuel Cell Power Generation Market Outlook, By Utility (2023-2034) ($MN)
54 Global Fuel Cell Power Generation Market Outlook, By Data Centers (2023-2034) ($MN)
55 Global Fuel Cell Power Generation Market Outlook, By Telecommunications (2023-2034) ($MN)
56 Global Fuel Cell Power Generation Market Outlook, By Healthcare (2023-2034) ($MN)
57 Global Fuel Cell Power Generation Market Outlook, By Government and Defense (2023-2034) ($MN)
58 Global Fuel Cell Power Generation Market Outlook, By Other End Users (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
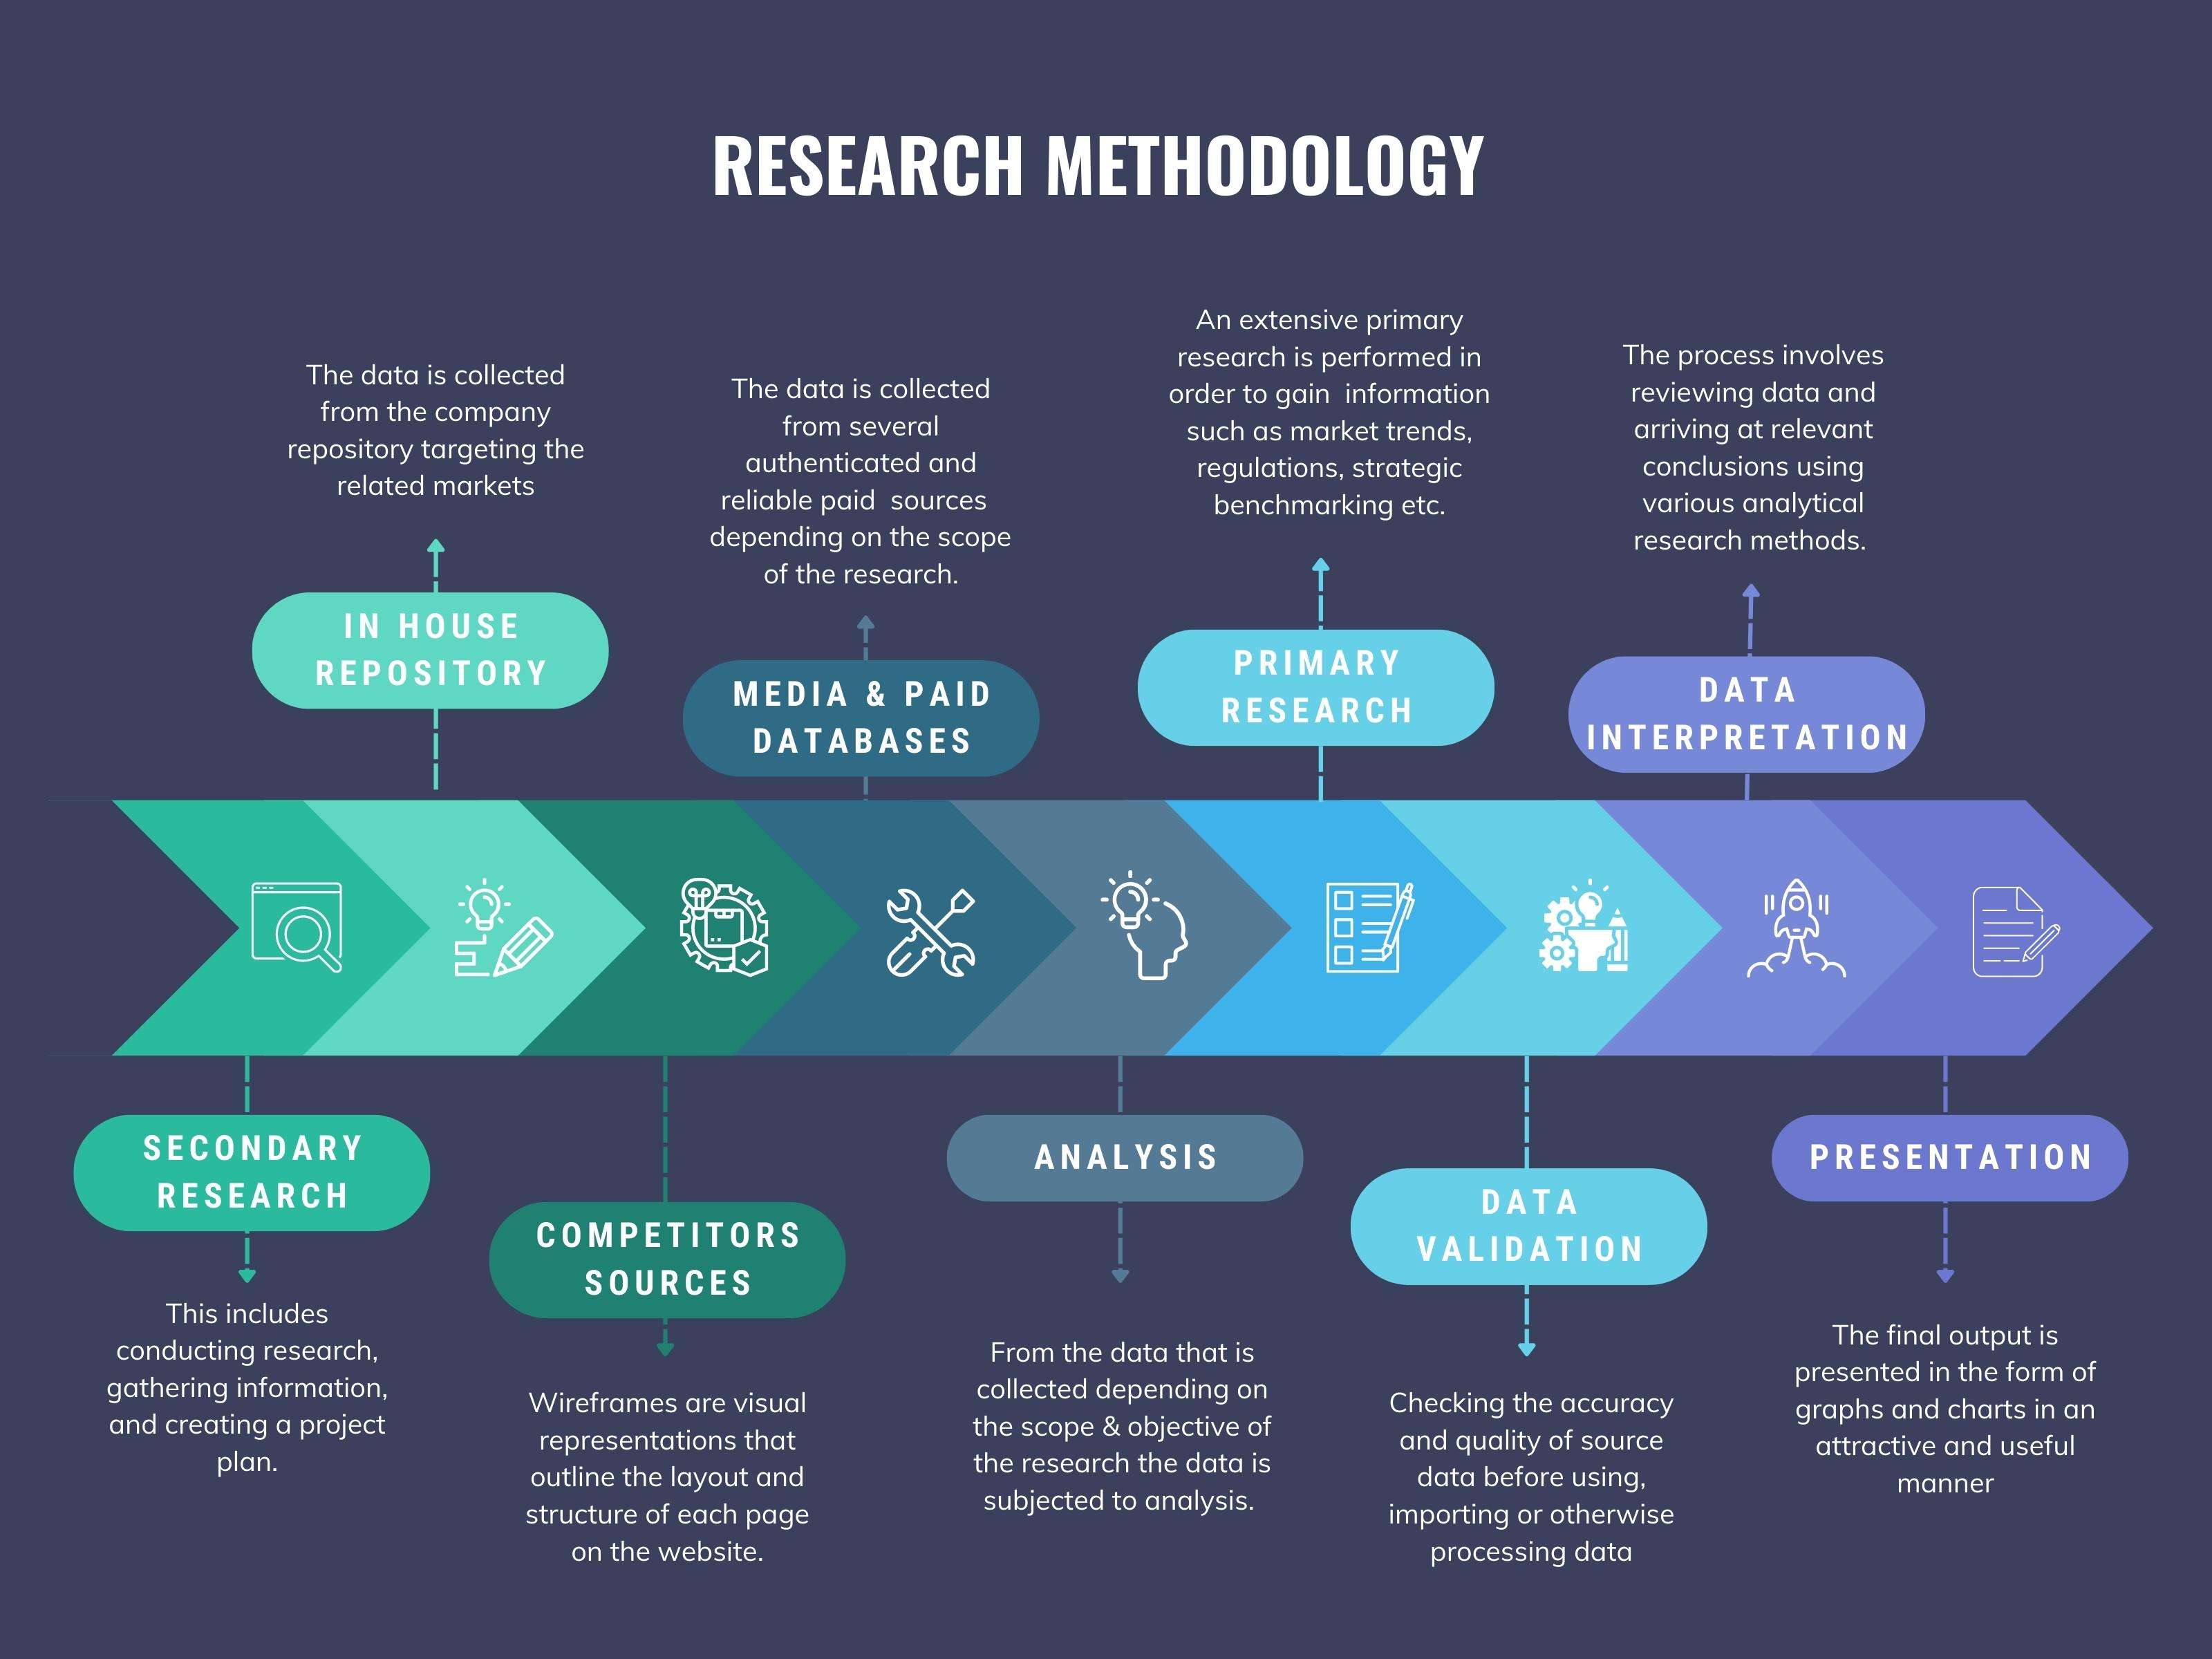
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.