High Voltage Direct Current Market
High-Voltage Direct Current Market Forecasts To 2034 – Global Analysis By Component (HVDC Cables, Overhead Transmission Lines, Converter Transformers, Thyristor Valves, IGBT-Based Valves, Smoothing Reactors, Harmonic Filters, DC Switchgear, Control and Protection Systems and Other Components), Project Configuration, Transmission Medium, Voltage Level, Power Rating, Technology, Application, End User and By Geography
According to Stratistics MRC, the Global High-Voltage Direct Current Market is accounted for $16.1 billion in 2026 and is expected to reach $31.4 billion by 2034 growing at a CAGR of 8.7% during the forecast period. The High-Voltage Direct Current market is witnessing growth due to increasing demand for efficient electricity transmission, renewable energy connectivity, and modernized power networks. HVDC systems provide advantages such as reduced transmission losses, enhanced control over electricity flows, and dependable connections between grids operating at different frequencies. Rising deployment of offshore wind, utility-scale solar, international power links, and advanced grid infrastructure is creating new opportunities for HVDC solutions. Innovations in converter technology, high-voltage cables, and voltage-source converters are enhancing operational performance and adaptability. The global transition toward electrification, expansion of renewable power generation, and growing requirements for grid reliability are expected to drive HVDC adoption.
Market Dynamics:
Driver:
Increasing Demand for Long-Distance Power Transmission
Rising demand for efficient electricity transportation across extended distances is contributing strongly to HVDC market development. Power generation facilities are increasingly being established away from densely populated cities, whereas electricity demand continues to grow in urban and industrial areas. HVDC technology enables bulk electricity to be transmitted efficiently between distant locations while helping reduce energy losses and infrastructure requirements. It is especially valuable for transferring power from remote renewable and conventional generation projects to major consumption centers. Increasing electricity usage, development of interconnected grids, and modernization of aging transmission infrastructure are motivating utilities and governments to invest in HVDC networks, supporting continued expansion of the global market.
Restraint:
High Initial Capital Investment
The considerable upfront cost associated with HVDC infrastructure can restrict market expansion. Developing an HVDC network requires major investments in converter stations, specialized cables, substations, control equipment, and related transmission facilities. Engineering complexity and construction requirements can further raise expenses, especially for projects involving long transmission distances or underwater cables. Utilities and governments with constrained budgets may experience difficulties securing sufficient financing for such large-scale developments. While HVDC technology can deliver operational and efficiency advantages over its lifetime, the substantial initial expenditure and lengthy investment recovery period can discourage immediate adoption. These economic considerations may particularly affect HVDC deployment in developing and financially constrained electricity markets.
Opportunity:
Expansion of Offshore Wind Power Projects
Growing deployment of offshore wind farms creates strong opportunities for HVDC technology providers. Offshore renewable facilities are commonly situated considerable distances from shore, making dependable and efficient electricity transmission essential. HVDC systems can transport substantial power through extended underwater cable routes while maintaining comparatively low transmission losses, making them suitable for large offshore developments. Future offshore energy hubs and interconnected transmission networks could generate additional requirements for HVDC converters, cables, and grid-control systems. Increasing government support, private-sector investment, and decarbonization initiatives are encouraging offshore wind development across various regions. This expansion provides HVDC manufacturers and infrastructure developers with significant opportunities to secure new projects and expand their market presence.
Threat:
Environmental and Community Opposition
Environmental issues and resistance from local communities can create significant obstacles for HVDC infrastructure development. Transmission corridors may require substantial land, construction activities, and supporting facilities that could affect ecosystems, farmland, residential areas, and coastal environments. Underwater HVDC cables may also attract environmental scrutiny because of potential impacts on marine ecosystems. Community objections can result in legal proceedings, additional environmental assessments, permitting complications, and construction delays. Such challenges can increase development expenses and create uncertainty for project developers. Despite HVDC technology's benefits for renewable integration and efficient power transmission, concerns involving land requirements, environmental disruption, visual effects, and local interests may hinder approvals and slow infrastructure deployment.
Covid-19 Impact:
COVID-19 created considerable challenges for the High-Voltage Direct Current market through interruptions in power demand, project construction, equipment manufacturing, logistics, and infrastructure spending. Lockdown measures reduced electricity consumption from industrial and commercial sectors, while workforce restrictions and limited site access slowed transmission construction. Disruptions across international supply networks affected the availability and transportation of specialized HVDC equipment, including transformers, cables, and converter-related components. Financial difficulties among utilities and energy companies further contributed to project delays and investment uncertainty. In India, pandemic restrictions affected transmission and renewable energy development, demonstrating weaknesses in supply-chain resilience and project execution. At the same time, the crisis strengthened attention toward reliable and resilient power infrastructure.
The HVDC Cables segment is expected to be the largest during the forecast period
The HVDC Cables segment is expected to account for the largest market share during the forecast period, supported by rising investments in long-distance and underwater power transmission infrastructure. These cables enable efficient transfer of substantial electricity volumes from remote generation sources to major demand centers. Demand is being reinforced by expanding offshore wind developments, international grid connections, and renewable energy facilities situated away from established transmission networks. Continuous improvements in insulation technologies, cable durability, power-handling capabilities, and installation methods are enhancing their performance. Furthermore, expanding grid modernization initiatives and increasing renewable electricity deployment are creating favorable conditions for greater adoption of HVDC cable systems across global transmission networks.
The Voltage Source Converter (VSC) segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the Voltage Source Converter (VSC) segment is predicted to witness the highest growth rate, driven by rising demand for renewable energy connections, offshore wind transmission, and flexible electricity networks. VSC-based HVDC technology offers precise power management, black-start functionality, and reliable operation with weak or isolated electrical grids. Its ability to support submarine connections for offshore renewable facilities is expanding its application potential. The technology can independently manage active and reactive power, contributing to improved grid stability and greater operational flexibility. Continuous developments in power semiconductors, converter designs, efficiency, and digital control technologies are strengthening VSC performance. These capabilities are expected to accelerate VSC adoption across modern transmission infrastructure worldwide.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, driven by increasing spending on transmission upgrades, renewable energy connections, and modern grid infrastructure. The region's extensive electricity network requires modernization to enhance reliability, operational flexibility, and efficient power transfer across long distances. Expansion of offshore wind, utility-scale solar, and other renewable generation facilities is creating additional requirements for advanced transmission technologies. Development of regional power connections and initiatives focused on improving grid resilience are further encouraging HVDC deployment. Ongoing technological innovation, utility modernization programs, and favorable energy policies are strengthening North America's position in the global HVDC market.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, driven by rising electricity consumption, growing renewable generation, and significant development of power transmission infrastructure. The region is witnessing increasing construction of large solar farms, wind installations, hydropower facilities, and offshore renewable projects that require dependable long-distance transmission solutions. Rapid urban development and industrial expansion are further increasing the need for efficient and stable electricity networks. Development of regional interconnections and upgrades to existing grids are creating additional opportunities for HVDC systems. Supportive government policies targeting renewable energy expansion, grid modernization, and energy security are also accelerating regional HVDC adoption.
Key players in the market
Some of the key players in High-Voltage Direct Current Market include Hitachi Energy Ltd., Siemens Energy AG, GE Vernova Inc., Mitsubishi Electric Corporation, Toshiba Energy Systems & Solutions Corporation, Bharat Heavy Electricals Limited (BHEL), NR Electric Co., Ltd., TBEA Co., Ltd., Hyosung Heavy Industries Corporation, LS ELECTRIC Co., Ltd., Prysmian S.p.A., Nexans S.A., NKT A/S, Sumitomo Electric Industries, Ltd., LS Cable & System Ltd., Hengtong Group, Taihan Cable & Solution Co., Ltd. and Jiangsu Zhongtian Technology Co., Ltd. (ZTT).
Key Developments:
In August 2026, GE Vernova announced an agreement with LS Electric to establish a joint venture focused on strengthening their competitiveness in the VSC-HVDC business.
In June 2026, Terna and STEG awarded Hitachi Energy a major contract for the converter stations of the Elmed electricity interconnection between Italy and Tunisia. The partnership involves delivery of the HVDC converter-station solution for the first direct-current interconnection between Europe and North Africa, supporting cross-border electricity transmission and regional grid integration.
In April 2026, Hitachi Energy and Samsung C&T expanded their strategic collaboration to accelerate global grid infrastructure development. The agreement builds on their existing cooperation across major projects, particularly in the HVDC market, and establishes a framework for jointly pursuing opportunities and developing a shared market roadmap
Components Covered:
• HVDC Cables
• Overhead Transmission Lines
• Converter Transformers
• Thyristor Valves
• IGBT-Based Valves
• Smoothing Reactors
• Harmonic Filters
• DC Switchgear
• Control and Protection Systems
• Other Components
Project Configurations Covered:
• Point-to-Point HVDC
• Back-to-Back HVDC
• Multi-Terminal HVDC
• HVDC Grids
Transmission Mediums Covered:
• Overhead Transmission
• Submarine Transmission
• Underground Transmission
• Hybrid Transmission
Voltage Levels Covered:
• ±100–200 kV
• ±201–400 kV
• ±401–600 kV
• ±601–800 kV
• Above ±800 kV
Power Ratings Covered:
• Up to 500 MW
• 501–1,000 MW
• 1,001–2,000 MW
• 2,001–5,000 MW
• Above 5,000 MW
Technologies Covered:
• Line-Commutated Converter (LCC)
• Voltage Source Converter (VSC)
• Capacitor-Commutated Converter (CCC)
• Other HVDC Technologies
Applications Covered:
• Long-Distance Bulk Power Transmission
• Renewable Energy Integration
• Offshore Renewable Energy Transmission
• Power Grid Interconnection
• Remote Power Supply
• Urban Power Transmission
• Grid Stabilization and Power Flow Control
• Other Applications
End Users Covered:
• Transmission System Operators
• Electric Utilities
• Renewable Energy Developers
• Independent Power Producers
• Industrial Power Consumers
• Government and Public Infrastructure Operators
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global High-Voltage Direct Current Market, By Component
5.1 HVDC Cables
5.2 Overhead Transmission Lines
5.3 Converter Transformers
5.4 Thyristor Valves
5.5 IGBT-Based Valves
5.6 Smoothing Reactors
5.7 Harmonic Filters
5.8 DC Switchgear
5.9 Control and Protection Systems
5.10 Other Components
6 Global High-Voltage Direct Current Market, By Project Configuration
6.1 Point-to-Point HVDC
6.2 Back-to-Back HVDC
6.3 Multi-Terminal HVDC
6.4 HVDC Grids
7 Global High-Voltage Direct Current Market, By Transmission Medium
7.1 Overhead Transmission
7.2 Submarine Transmission
7.3 Underground Transmission
7.4 Hybrid Transmission
8 Global High-Voltage Direct Current Market, By Voltage Level
8.1 ±100–200 kV
8.2 ±201–400 kV
8.3 ±401–600 kV
8.4 ±601–800 kV
8.5 Above ±800 kV
9 Global High-Voltage Direct Current Market, By Power Rating
9.1 Up to 500 MW
9.2 501–1,000 MW
9.3 1,001–2,000 MW
9.4 2,001–5,000 MW
9.5 Above 5,000 MW
10 Global High-Voltage Direct Current Market, By Technology
10.1 Line-Commutated Converter (LCC)
10.2 Voltage Source Converter (VSC)
10.3 Capacitor-Commutated Converter (CCC)
10.4 Other HVDC Technologies
11 Global High-Voltage Direct Current Market, By Application
11.1 Long-Distance Bulk Power Transmission
11.2 Renewable Energy Integration
11.3 Offshore Renewable Energy Transmission
11.4 Power Grid Interconnection
11.5 Remote Power Supply
11.6 Urban Power Transmission
11.7 Grid Stabilization and Power Flow Control
11.8 Other Applications
12 Global High-Voltage Direct Current Market, By End User
12.1 Transmission System Operators
12.2 Electric Utilities
12.3 Renewable Energy Developers
12.4 Independent Power Producers
12.5 Industrial Power Consumers
12.6 Government and Public Infrastructure Operators
13 Global High-Voltage Direct Current Market, By Geography
13.1 North America
13.1.1 United States
13.1.2 Canada
13.1.3 Mexico
13.2 Europe
13.2.1 United Kingdom
13.2.2 Germany
13.2.3 France
13.2.4 Italy
13.2.5 Spain
13.2.6 Netherlands
13.2.7 Belgium
13.2.8 Sweden
13.2.9 Switzerland
13.2.10 Poland
13.2.11 Rest of Europe
13.3 Asia Pacific
13.3.1 China
13.3.2 Japan
13.3.3 India
13.3.4 South Korea
13.3.5 Australia
13.3.6 Indonesia
13.3.7 Thailand
13.3.8 Malaysia
13.3.9 Singapore
13.3.10 Vietnam
13.3.11 Rest of Asia Pacific
13.4 South America
13.4.1 Brazil
13.4.2 Argentina
13.4.3 Colombia
13.4.4 Chile
13.4.5 Peru
13.4.6 Rest of South America
13.5 Rest of the World (RoW)
13.5.1 Middle East
13.5.1.1 Saudi Arabia
13.5.1.2 United Arab Emirates
13.5.1.3 Qatar
13.5.1.4 Israel
13.5.1.5 Rest of Middle East
13.5.2 Africa
13.5.2.1 South Africa
13.5.2.2 Egypt
13.5.2.3 Morocco
13.5.2.4 Rest of Africa
14 Strategic Market Intelligence
14.1 Industry Value Network and Supply Chain Assessment
14.2 White-Space and Opportunity Mapping
14.3 Product Evolution and Market Life Cycle Analysis
14.4 Channel, Distributor, and Go-to-Market Assessment
15 Industry Developments and Strategic Initiatives
15.1 Mergers and Acquisitions
15.2 Partnerships, Alliances, and Joint Ventures
15.3 New Product Launches and Certifications
15.4 Capacity Expansion and Investments
15.5 Other Strategic Initiatives
16 Company Profiles
16.1 Hitachi Energy Ltd.
16.2 Siemens Energy AG
16.3 GE Vernova Inc.
16.4 Mitsubishi Electric Corporation
16.5 Toshiba Energy Systems & Solutions Corporation
16.6 Bharat Heavy Electricals Limited (BHEL)
16.7 NR Electric Co., Ltd.
16.8 TBEA Co., Ltd.
16.9 Hyosung Heavy Industries Corporation
16.10 LS ELECTRIC Co., Ltd.
16.11 Prysmian S.p.A.
16.12 Nexans S.A.
16.13 NKT A/S
16.14 Sumitomo Electric Industries, Ltd.
16.15 LS Cable & System Ltd.
16.16 Hengtong Group
16.17 Taihan Cable & Solution Co., Ltd.
16.18 Jiangsu Zhongtian Technology Co., Ltd. (ZTT)
List of Tables
1 Global High-Voltage Direct Current Market Outlook, By Region (2023-2034) ($MN)
2 Global High-Voltage Direct Current Market Outlook, By Component (2023-2034) ($MN)
3 Global High-Voltage Direct Current Market Outlook, By HVDC Cables (2023-2034) ($MN)
4 Global High-Voltage Direct Current Market Outlook, By Overhead Transmission Lines (2023-2034) ($MN)
5 Global High-Voltage Direct Current Market Outlook, By Converter Transformers (2023-2034) ($MN)
6 Global High-Voltage Direct Current Market Outlook, By Thyristor Valves (2023-2034) ($MN)
7 Global High-Voltage Direct Current Market Outlook, By IGBT-Based Valves (2023-2034) ($MN)
8 Global High-Voltage Direct Current Market Outlook, By Smoothing Reactors (2023-2034) ($MN)
9 Global High-Voltage Direct Current Market Outlook, By Harmonic Filters (2023-2034) ($MN)
10 Global High-Voltage Direct Current Market Outlook, By DC Switchgear (2023-2034) ($MN)
11 Global High-Voltage Direct Current Market Outlook, By Control and Protection Systems (2023-2034) ($MN)
12 Global High-Voltage Direct Current Market Outlook, By Other Components (2023-2034) ($MN)
13 Global High-Voltage Direct Current Market Outlook, By Project Configuration (2023-2034) ($MN)
14 Global High-Voltage Direct Current Market Outlook, By Point-to-Point HVDC (2023-2034) ($MN)
15 Global High-Voltage Direct Current Market Outlook, By Back-to-Back HVDC (2023-2034) ($MN)
16 Global High-Voltage Direct Current Market Outlook, By Multi-Terminal HVDC (2023-2034) ($MN)
17 Global High-Voltage Direct Current Market Outlook, By HVDC Grids (2023-2034) ($MN)
18 Global High-Voltage Direct Current Market Outlook, By Transmission Medium (2023-2034) ($MN)
19 Global High-Voltage Direct Current Market Outlook, By Overhead Transmission (2023-2034) ($MN)
20 Global High-Voltage Direct Current Market Outlook, By Submarine Transmission (2023-2034) ($MN)
21 Global High-Voltage Direct Current Market Outlook, By Underground Transmission (2023-2034) ($MN)
22 Global High-Voltage Direct Current Market Outlook, By Hybrid Transmission (2023-2034) ($MN)
23 Global High-Voltage Direct Current Market Outlook, By Voltage Level (2023-2034) ($MN)
24 Global High-Voltage Direct Current Market Outlook, By ±100–200 kV (2023-2034) ($MN)
25 Global High-Voltage Direct Current Market Outlook, By ±201–400 kV (2023-2034) ($MN)
26 Global High-Voltage Direct Current Market Outlook, By ±401–600 kV (2023-2034) ($MN)
27 Global High-Voltage Direct Current Market Outlook, By ±601–800 kV (2023-2034) ($MN)
28 Global High-Voltage Direct Current Market Outlook, By Above ±800 kV (2023-2034) ($MN)
29 Global High-Voltage Direct Current Market Outlook, By Power Rating (2023-2034) ($MN)
30 Global High-Voltage Direct Current Market Outlook, By Up to 500 MW (2023-2034) ($MN)
31 Global High-Voltage Direct Current Market Outlook, By 501–1,000 MW (2023-2034) ($MN)
32 Global High-Voltage Direct Current Market Outlook, By 1,001–2,000 MW (2023-2034) ($MN)
33 Global High-Voltage Direct Current Market Outlook, By 2,001–5,000 MW (2023-2034) ($MN)
34 Global High-Voltage Direct Current Market Outlook, By Above 5,000 MW (2023-2034) ($MN)
35 Global High-Voltage Direct Current Market Outlook, By Technology (2023-2034) ($MN)
36 Global High-Voltage Direct Current Market Outlook, By Line-Commutated Converter (LCC) (2023-2034) ($MN)
37 Global High-Voltage Direct Current Market Outlook, By Voltage Source Converter (VSC) (2023-2034) ($MN)
38 Global High-Voltage Direct Current Market Outlook, By Capacitor-Commutated Converter (CCC) (2023-2034) ($MN)
39 Global High-Voltage Direct Current Market Outlook, By Other HVDC Technologies (2023-2034) ($MN)
40 Global High-Voltage Direct Current Market Outlook, By Application (2023-2034) ($MN)
41 Global High-Voltage Direct Current Market Outlook, By Long-Distance Bulk Power Transmission (2023-2034) ($MN)
42 Global High-Voltage Direct Current Market Outlook, By Renewable Energy Integration (2023-2034) ($MN)
43 Global High-Voltage Direct Current Market Outlook, By Offshore Renewable Energy Transmission (2023-2034) ($MN)
44 Global High-Voltage Direct Current Market Outlook, By Power Grid Interconnection (2023-2034) ($MN)
45 Global High-Voltage Direct Current Market Outlook, By Remote Power Supply (2023-2034) ($MN)
46 Global High-Voltage Direct Current Market Outlook, By Urban Power Transmission (2023-2034) ($MN)
47 Global High-Voltage Direct Current Market Outlook, By Grid Stabilization and Power Flow Control (2023-2034) ($MN)
48 Global High-Voltage Direct Current Market Outlook, By Other Applications (2023-2034) ($MN)
49 Global High-Voltage Direct Current Market Outlook, By End User (2023-2034) ($MN)
50 Global High-Voltage Direct Current Market Outlook, By Transmission System Operators (2023-2034) ($MN)
51 Global High-Voltage Direct Current Market Outlook, By Electric Utilities (2023-2034) ($MN)
52 Global High-Voltage Direct Current Market Outlook, By Renewable Energy Developers (2023-2034) ($MN)
53 Global High-Voltage Direct Current Market Outlook, By Independent Power Producers (2023-2034) ($MN)
54 Global High-Voltage Direct Current Market Outlook, By Industrial Power Consumers (2023-2034) ($MN)
55 Global High-Voltage Direct Current Market Outlook, By Government and Public Infrastructure Operators (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
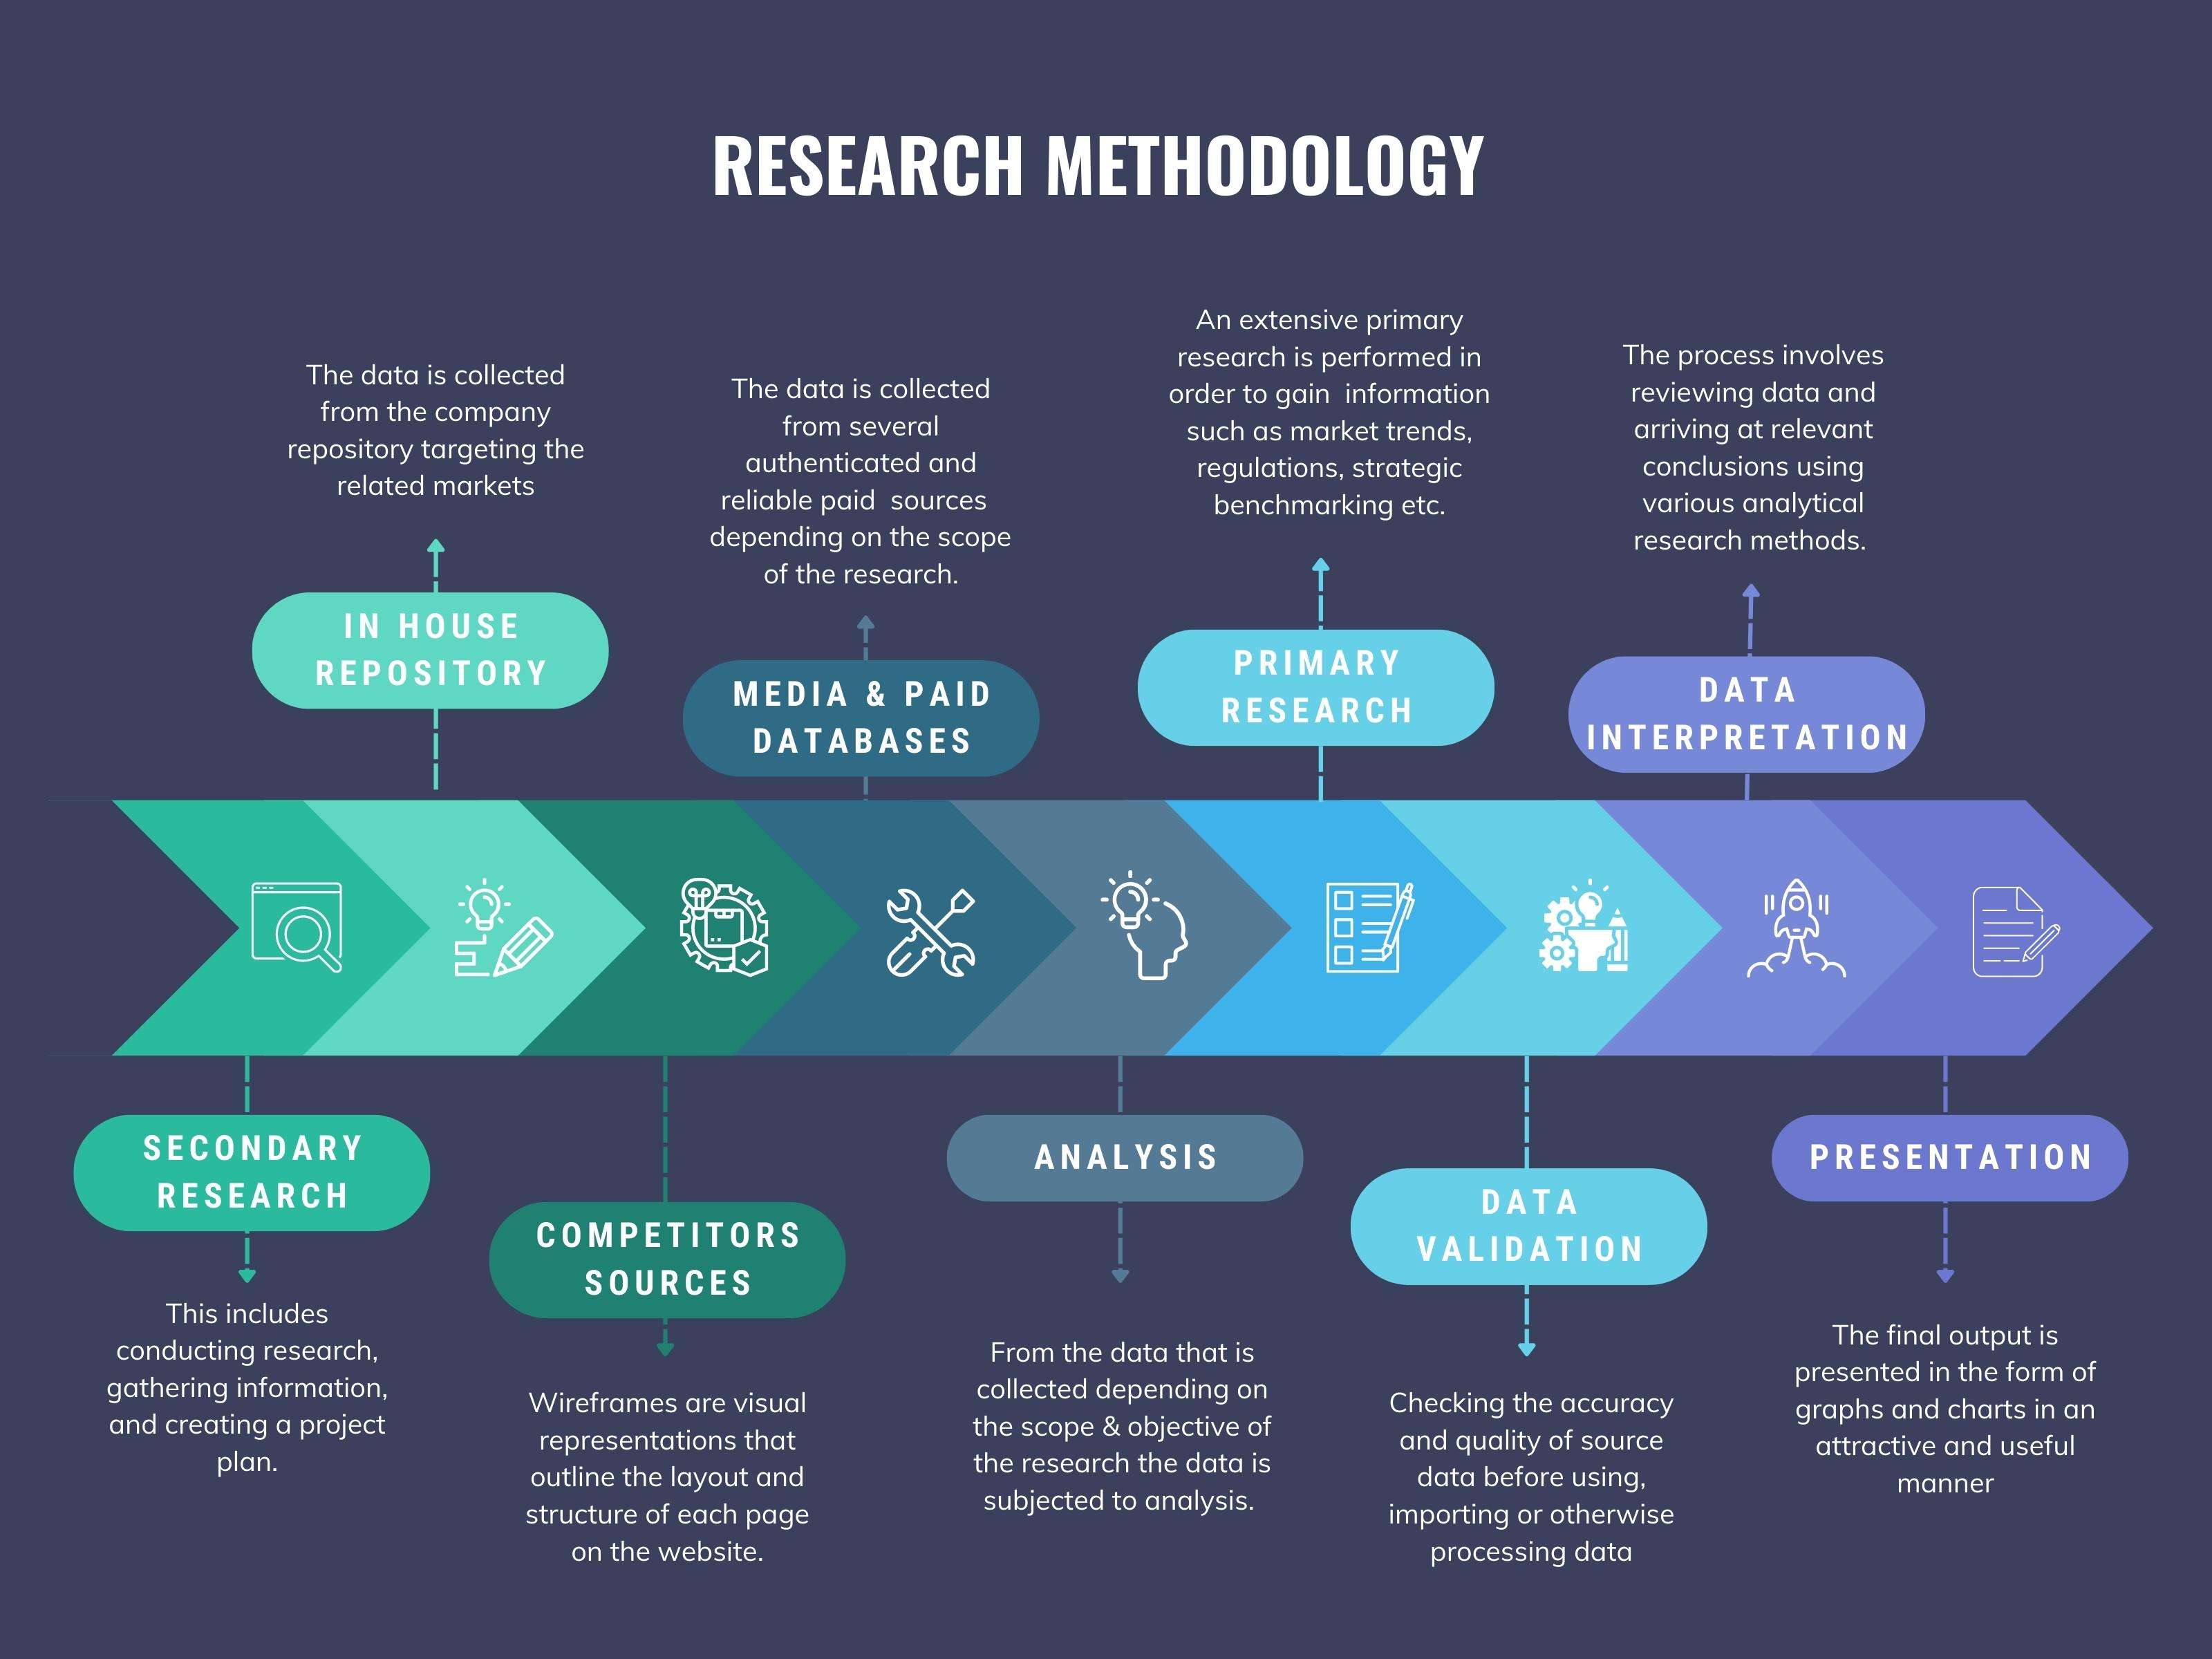
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.