Plastic Depolymerization Catalysts Market
Plastic Depolymerization Catalysts Market Forecasts to 2034 – Global Analysis By Catalyst Type (Enzymatic and Biocatalysts, Chemical Acid-Base Catalysts, Metal-Based and Organometallic Catalysts, Photocatalysts and Thermal and Solid-State Catalysts), Technology, Target Plastic, Form, Application, End User and By Geography
According to Stratistics MRC, the Global Plastic Depolymerization Catalysts Market is accounted for $0.4 billion in 2026 and is expected to reach $1.1 billion by 2034 growing at a CAGR of 13.4% during the forecast period. Plastic depolymerization catalysts are specialized chemical or biological agents designed to accelerate the breakdown of complex polymer chains into their constituent monomers or smaller oligomers. They function by lowering the activation energy required for bond cleavage, enabling efficient chemical recycling of plastic waste under milder conditions than traditional thermal processes. These catalysts encompass enzymatic, acid-base, metal-based, and photocatalytic formulations that facilitate targeted degradation of specific plastic types. Their application ensures the recovery of high-purity raw materials, supporting circular economy initiatives and reducing reliance on virgin fossil-fuel-derived plastics.
Market Dynamics:
Driver:
Rising Circular Economy Mandates
The escalating global emphasis on circular economy principles compels chemical manufacturers to adopt plastic depolymerization catalysts offering efficient waste-to-monomer alternatives. Growing regulatory pressure to minimize landfill accumulation and plastic pollution is accelerating the integration of these catalytic systems into advanced recycling facilities. This transition is supported by advancements in catalyst engineering, which enhance reaction selectivity and yield. Consequently, industries are investing in specialized depolymerization technologies to achieve compliance with stringent sustainability mandates while optimizing raw material recovery costs.
Restraint:
High Catalyst Development Costs
The substantial expenses associated with researching and developing advanced plastic depolymerization catalysts represent a significant barrier to widespread commercial adoption. Creating highly stable and efficient catalytic formulations often requires complex synthesis processes and sophisticated testing techniques, which escalate overall production costs. Furthermore, the sensitivity of certain biological or metal-based catalysts to specific impurities limits their operational lifespan in heterogeneous waste streams. These factors collectively constrain market expansion, particularly for enterprises with limited research budgets.
Opportunity:
Expansion in PET Recycling
The polyethylene terephthalate (PET) recycling sector presents substantial growth opportunities for plastic depolymerization catalyst manufacturers due to increasing demand for closed-loop material recovery. Advanced catalytic solutions offer a highly effective pathway to break down post-consumer PET into virgin-quality monomers without compromising material integrity, utilizing specialized enzymatic or chemical agents as primary inputs. As global investments in sustainable packaging expand and regulatory agencies favor circular material pathways, the adoption of advanced depolymerization catalysts is expected to surge significantly.
Threat:
Competition from Mechanical Recycling
The continuous innovation of advanced mechanical recycling technologies poses a considerable threat to the plastic depolymerization catalysts market. Traditional physical sorting and reprocessing methods often exhibit superior cost-effectiveness under current industrial conditions and can be more economically viable for high-volume, single-stream plastic waste. Additionally, the rapid advancement of automated sorting infrastructure is enhancing the efficiency of conventional mechanical recycling methods. This competitive pressure may hinder market penetration, particularly where initial capital investment is a primary operational consideration.
Covid-19 Impact:
The pandemic initially disrupted plastic depolymerization catalyst supply chains and delayed advanced recycling facility deployments due to logistical constraints. However, the subsequent surge in single-use plastic waste accelerated the adoption of chemical recycling solutions to manage mounting environmental pressures. Post-pandemic, the heightened focus on supply chain resilience and sustainable material sourcing has reinforced long-term investments in depolymerization technologies, driving robust market recovery and expansion across diverse chemical manufacturing sectors globally.
The chemical acid-base catalysts segment is expected to be the largest during the forecast period
The chemical acid-base catalysts segment is expected to account for the largest market share during the forecast period, due to their unparalleled reaction efficiency and widespread applicability across diverse plastic recycling environments. These catalysts offer exceptional depolymerization rates and operate effectively in breaking down complex polymer chains, which significantly reduces energy consumption and minimizes hazardous byproduct generation in recycling processes. As industries increasingly prioritize scalable and cost-effective material recovery methods, the demand for specialized acid-base catalysts continues to surge, thereby solidifying their dominant market position.
The enzymatic depolymerization segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the enzymatic depolymerization segment is predicted to witness the highest growth rate, driven by rapid advancements in synthetic biology and protein engineering. These technologies enable the precise modification of biological enzymes to produce highly specialized and robust catalysts tailored for specific plastic degradation applications. The ability to enhance reaction specificity, operational stability, and environmental compatibility through advanced bioengineering significantly improves process economics. Consequently, increasing investments in green chemistry research and favorable regulatory frameworks are accelerating commercial adoption globally.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, due to the presence of well-established chemical manufacturing industries and advanced recycling infrastructure that heavily utilize plastic depolymerization catalysts. The region benefits from substantial research and development investments, robust intellectual property protection, and supportive government initiatives promoting circular economy principles and sustainable material sourcing. Furthermore, the early adoption of advanced catalytic technologies by key industry players in the United States and Canada reinforces the region's dominant position globally.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, due to rapid industrialization and expanding chemical processing sectors in emerging economies. Countries such as China, India, and Japan are increasingly investing in advanced recycling infrastructure and sustainable manufacturing technologies to meet growing domestic waste management demands and stringent environmental regulations. Additionally, favorable government policies, rising foreign direct investment, and the availability of cost-effective research resources are collectively driving the accelerated adoption of depolymerization catalysts across the region.
Key players in the market
Some of the key players in Plastic Depolymerization Catalysts Market include BASF SE, Dow Inc., Carbios, Gr3n, Loop Industries, Eastman Chemical Company, Mitsubishi Chemical Corporation, Ioniqa Technologies, AMSilk GmbH, BioBTX B.V., Plastic Energy, Agilyx Corporation, Honeywell UOP, Brightmark, Mura Technology, Novoloop, PureCycle Technologies, and Alterra Energy.
Key Developments:
In September 2026, BASF SE launched a next-generation chemical acid-base catalyst optimized for PET depolymerization, achieving a thirty percent improvement in monomer yield while significantly reducing energy consumption requirements for global advanced recycling facilities.
In August 2026, Carbios expanded its enzymatic depolymerization capacity through a strategic partnership with a leading synthetic biology firm, enabling the scalable manufacturing of novel biological catalysts for sustainable plastic waste processing.
In July 2026, Eastman Chemical Company secured a major supply agreement to provide customized methanolysis catalysts for a prominent packaging producer, facilitating the efficient conversion of post-consumer plastic waste into virgin-quality monomers globally.
Catalyst Types Covered:
• Enzymatic and Biocatalysts
• Chemical Acid-Base Catalysts
• Metal-Based and Organometallic Catalysts
• Photocatalysts
• Thermal and Solid-State Catalysts
Technologies Covered:
• Hydrolysis
• Glycolysis
• Methanolysis
• Pyrolysis and Thermolysis
• Enzymatic Depolymerization
Target Plastics Covered:
• Polyethylene Terephthalate (PET)
• Polyurethanes (PU)
• Polyamides (Nylon)
• Polycarbonates (PC)
• Polyolefins (PE, PP)
Forms Covered:
• Liquid Solutions
• Solid Powders and Granules
• Immobilized and Supported Catalysts
• Gel and Paste Formulations
Applications Covered:
• Textile and Fiber Recycling
• Packaging and Container Recycling
• Automotive Parts and Components
• Electronics and E-Waste
• Construction and Building Materials
End Users Covered:
• Chemical and Advanced Recycling Facilities
• Virgin Plastic and Polymer Manufacturers
• Waste Management and Recovery Companies
• Textile and Apparel Manufacturers
• Research and Development Institutions
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary
1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global Plastic Depolymerization Catalysts Market, By Catalyst Type
5.1 Enzymatic and Biocatalysts
5.2 Chemical Acid-Base Catalysts
5.3 Metal-Based and Organometallic Catalysts
5.4 Photocatalysts
5.5 Thermal and Solid-State Catalysts
6 Global Plastic Depolymerization Catalysts Market, By Technology
6.1 Hydrolysis
6.2 Glycolysis
6.3 Methanolysis
6.4 Pyrolysis and Thermolysis
6.5 Enzymatic Depolymerization
7 Global Plastic Depolymerization Catalysts Market, By Target Plastic
7.1 Polyethylene Terephthalate (PET)
7.2 Polyurethanes (PU)
7.3 Polyamides (Nylon)
7.4 Polycarbonates (PC)
7.5 Polyolefins (PE, PP)
8 Global Plastic Depolymerization Catalysts Market, By Form
8.1 Liquid Solutions
8.2 Solid Powders and Granules
8.3 Immobilized and Supported Catalysts
8.4 Gel and Paste Formulations
9 Global Plastic Depolymerization Catalysts Market, By Application
9.1 Textile and Fiber Recycling
9.2 Packaging and Container Recycling
9.3 Automotive Parts and Components
9.4 Electronics and E-Waste
9.5 Construction and Building Materials
10 Global Plastic Depolymerization Catalysts Market, By End User
10.1 Chemical and Advanced Recycling Facilities
10.2 Virgin Plastic and Polymer Manufacturers
10.3 Waste Management and Recovery Companies
10.4 Textile and Apparel Manufacturers
10.5 Research and Development Institutions
10.6 Other End Users
11 Global Plastic Depolymerization Catalysts Market, By Geography
11.1 North America
11.1.1 United States
11.1.2 Canada
11.1.3 Mexico
11.2 Europe
11.2.1 United Kingdom
11.2.2 Germany
11.2.3 France
11.2.4 Italy
11.2.5 Spain
11.2.6 Netherlands
11.2.7 Belgium
11.2.8 Sweden
11.2.9 Switzerland
11.2.10 Poland
11.2.11 Rest of Europe
11.3 Asia Pacific
11.3.1 China
11.3.2 Japan
11.3.3 India
11.3.4 South Korea
11.3.5 Australia
11.3.6 Indonesia
11.3.7 Thailand
11.3.8 Malaysia
11.3.9 Singapore
11.3.10 Vietnam
11.3.11 Rest of Asia Pacific
11.4 South America
11.4.1 Brazil
11.4.2 Argentina
11.4.3 Colombia
11.4.4 Chile
11.4.5 Peru
11.4.6 Rest of South America
11.5 Rest of the World (RoW)
11.5.1 Middle East
11.5.1.1 Saudi Arabia
11.5.1.2 United Arab Emirates
11.5.1.3 Qatar
11.5.1.4 Israel
11.5.1.5 Rest of Middle East
11.5.2 Africa
11.5.2.1 South Africa
11.5.2.2 Egypt
11.5.2.3 Morocco
11.5.2.4 Rest of Africa
12 Strategic Market Intelligence
12.1 Industry Value Network and Supply Chain Assessment
12.2 White-Space and Opportunity Mapping
12.3 Product Evolution and Market Life Cycle Analysis
12.4 Channel, Distributor, and Go-to-Market Assessment
13 Industry Developments and Strategic Initiatives
13.1 Mergers and Acquisitions
13.2 Partnerships, Alliances, and Joint Ventures
13.3 New Product Launches and Certifications
13.4 Capacity Expansion and Investments
13.5 Other Strategic Initiatives
14 Company Profiles
14.1 BASF SE
14.2 Dow Inc.
14.3 Carbios
14.4 Gr3n
14.5 Loop Industries
14.6 Eastman Chemical Company
14.7 Mitsubishi Chemical Corporation
14.8 Ioniqa Technologies
14.9 AMSilk GmbH
14.10 BioBTX B.V.
14.11 Plastic Energy
14.12 Agilyx Corporation
14.13 Honeywell UOP
14.14 Brightmark
14.15 Mura Technology
14.16 Novoloop
14.17 PureCycle Technologies
14.18 Alterra Energy
List of Tables
1 Global Plastic Depolymerization Catalysts Market Outlook, By Region (2023-2034) ($MN)
2 Global Plastic Depolymerization Catalysts Market Outlook, By Catalyst Type (2023-2034) ($MN)
3 Global Plastic Depolymerization Catalysts Market Outlook, By Enzymatic and Biocatalysts (2023-2034) ($MN)
4 Global Plastic Depolymerization Catalysts Market Outlook, By Chemical Acid-Base Catalysts (2023-2034) ($MN)
5 Global Plastic Depolymerization Catalysts Market Outlook, By Metal-Based and Organometallic Catalysts (2023-2034) ($MN)
6 Global Plastic Depolymerization Catalysts Market Outlook, By Photocatalysts (2023-2034) ($MN)
7 Global Plastic Depolymerization Catalysts Market Outlook, By Thermal and Solid-State Catalysts (2023-2034) ($MN)
8 Global Plastic Depolymerization Catalysts Market Outlook, By Technology (2023-2034) ($MN)
9 Global Plastic Depolymerization Catalysts Market Outlook, By Hydrolysis (2023-2034) ($MN)
10 Global Plastic Depolymerization Catalysts Market Outlook, By Glycolysis (2023-2034) ($MN)
11 Global Plastic Depolymerization Catalysts Market Outlook, By Methanolysis (2023-2034) ($MN)
12 Global Plastic Depolymerization Catalysts Market Outlook, By Pyrolysis and Thermolysis (2023-2034) ($MN)
13 Global Plastic Depolymerization Catalysts Market Outlook, By Enzymatic Depolymerization (2023-2034) ($MN)
14 Global Plastic Depolymerization Catalysts Market Outlook, By Target Plastic (2023-2034) ($MN)
15 Global Plastic Depolymerization Catalysts Market Outlook, By Polyethylene Terephthalate (PET) (2023-2034) ($MN)
16 Global Plastic Depolymerization Catalysts Market Outlook, By Polyurethanes (PU) (2023-2034) ($MN)
17 Global Plastic Depolymerization Catalysts Market Outlook, By Polyamides (Nylon) (2023-2034) ($MN)
18 Global Plastic Depolymerization Catalysts Market Outlook, By Polycarbonates (PC) (2023-2034) ($MN)
19 Global Plastic Depolymerization Catalysts Market Outlook, By Polyolefins (PE, PP) (2023-2034) ($MN)
20 Global Plastic Depolymerization Catalysts Market Outlook, By Form (2023-2034) ($MN)
21 Global Plastic Depolymerization Catalysts Market Outlook, By Liquid Solutions (2023-2034) ($MN)
22 Global Plastic Depolymerization Catalysts Market Outlook, By Solid Powders and Granules (2023-2034) ($MN)
23 Global Plastic Depolymerization Catalysts Market Outlook, By Immobilized and Supported Catalysts (2023-2034) ($MN)
24 Global Plastic Depolymerization Catalysts Market Outlook, By Gel and Paste Formulations (2023-2034) ($MN)
25 Global Plastic Depolymerization Catalysts Market Outlook, By Application (2023-2034) ($MN)
26 Global Plastic Depolymerization Catalysts Market Outlook, By Textile and Fiber Recycling (2023-2034) ($MN)
27 Global Plastic Depolymerization Catalysts Market Outlook, By Packaging and Container Recycling (2023-2034) ($MN)
28 Global Plastic Depolymerization Catalysts Market Outlook, By Automotive Parts and Components (2023-2034) ($MN)
29 Global Plastic Depolymerization Catalysts Market Outlook, By Electronics and E-Waste (2023-2034) ($MN)
30 Global Plastic Depolymerization Catalysts Market Outlook, By Construction and Building Materials (2023-2034) ($MN)
31 Global Plastic Depolymerization Catalysts Market Outlook, By End User (2023-2034) ($MN)
32 Global Plastic Depolymerization Catalysts Market Outlook, By Chemical and Advanced Recycling Facilities (2023-2034) ($MN)
33 Global Plastic Depolymerization Catalysts Market Outlook, By Virgin Plastic and Polymer Manufacturers (2023-2034) ($MN)
34 Global Plastic Depolymerization Catalysts Market Outlook, By Waste Management and Recovery Companies (2023-2034) ($MN)
35 Global Plastic Depolymerization Catalysts Market Outlook, By Textile and Apparel Manufacturers (2023-2034) ($MN)
36 Global Plastic Depolymerization Catalysts Market Outlook, By Research and Development Institutions (2023-2034) ($MN)
37 Global Plastic Depolymerization Catalysts Market Outlook, By Other End Users (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above.
List of Figures
RESEARCH METHODOLOGY
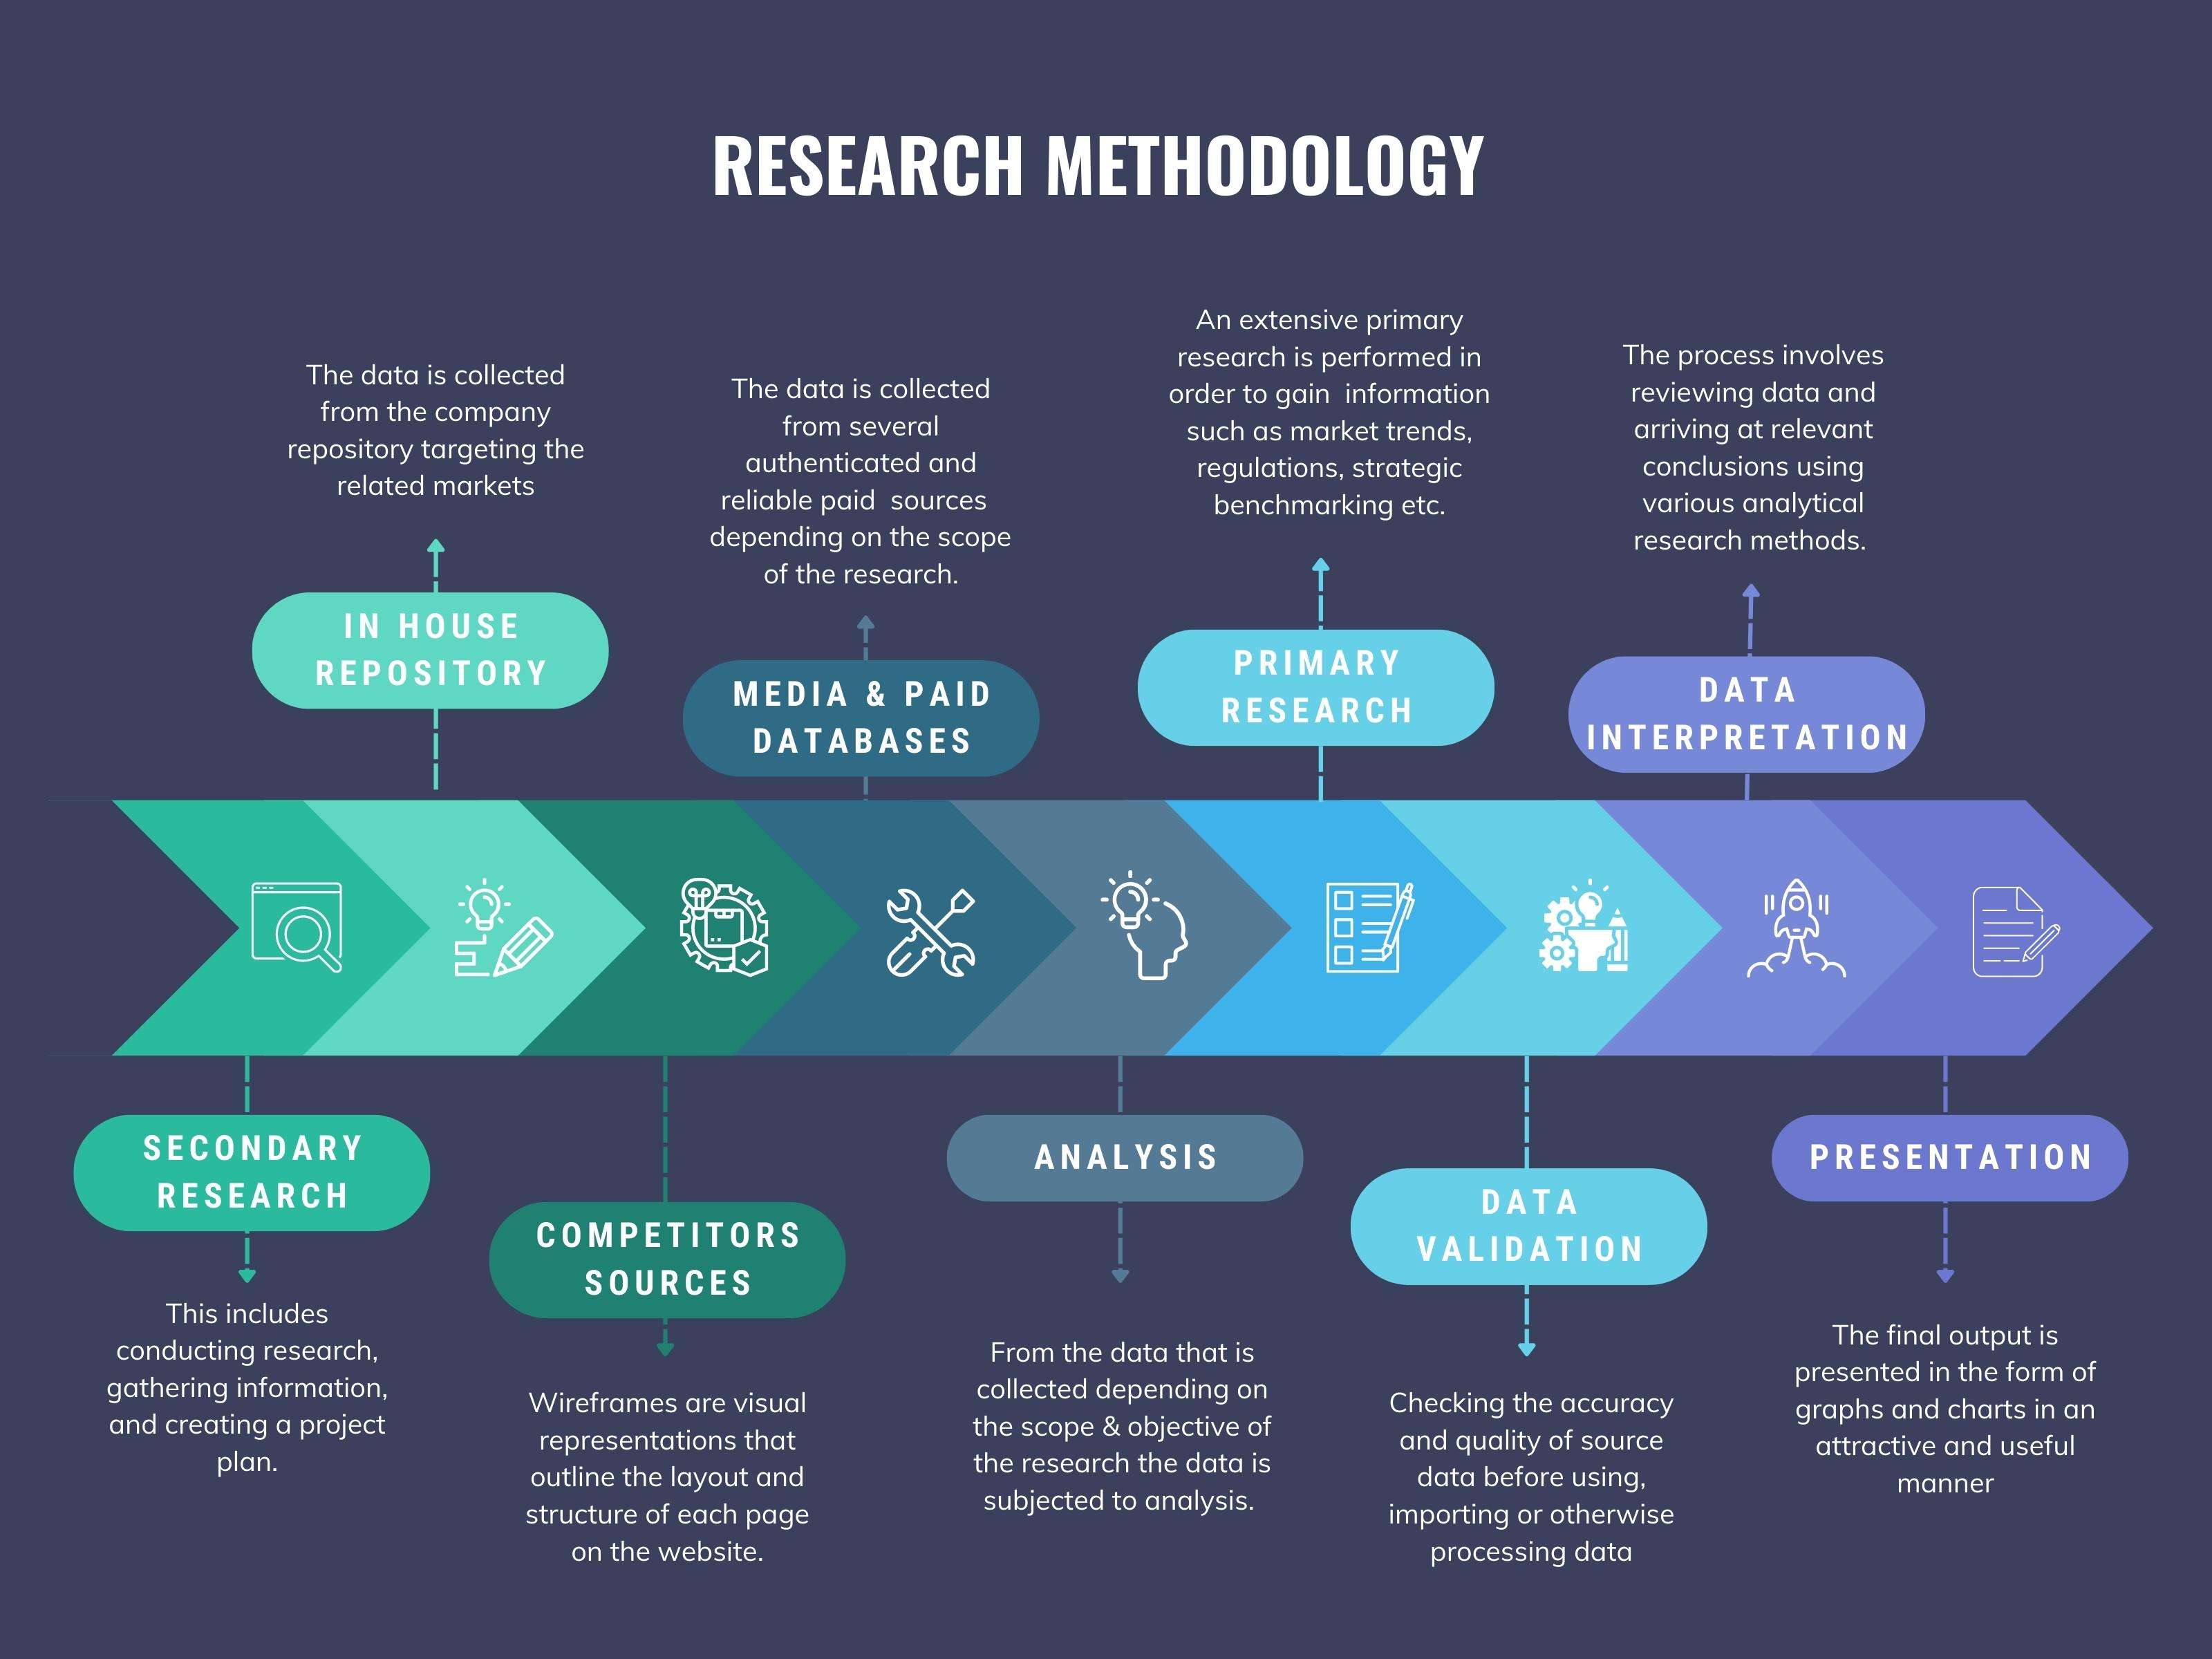
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.