6g Digital Beamforming Market
6G Digital Beamforming Market Forecasts to 2034 – Global Analysis By Component (Hardware, Software and Services), Beamforming Architecture, Antenna Configuration, Frequency Band, Technology, Application, End User and By Geography
Market Dynamics:
Driver:
Massive MIMO Scaling Toward 1,024-Element 6G Radios
The progression from 5G to 6G is driving an order-of-magnitude increase in antenna element counts per radio unit, creating computational demands that analog beamforming architectures cannot address. 5G radio units may integrate up to 128 antennas, already representing a 32-fold increase in processing load over earlier generations, while 6G radios are expected to reach 1,024 elements per unit. This scaling makes digital beamforming not merely advantageous but necessary for maintaining real-time beam management across hundreds of simultaneous spatial streams. NVIDIA is developing dedicated GPUs for 6G radio units specifically to replace the ASICs currently handling beamforming functions, recognizing that the combinatorial explosion of beamforming operations at 1,024 elements exceeds what fixed-function silicon can efficiently support. As operators plan 6G architectures, demand for digital beamforming hardware and software continues to expand.
Restraint:
Power Consumption and Thermal Density Constraints
Fully digital beamforming requires a dedicated RF chain and data converter for each antenna element, creating power consumption and thermal density challenges that escalate with array size. While digital architectures offer superior flexibility and array gain compared with hybrid approaches, the energy cost per element becomes a critical constraint as arrays scale toward 1,024 elements. NVIDIA’s strategy of introducing GPUs into radio units acknowledges this trade-off, with the company needing to convince operators that gains in flexibility and processing capability justify the additional energy burden. For operators already facing pressure on active equipment energy costs, the business case for fully digital beamforming at scale remains dependent on continued improvements in per-watt processing efficiency, constraining near-term adoption to high-value deployments.
Opportunity:
3GPP Standardization of Digital Beamforming for Device Architectures
The formal evaluation of digital beamforming for user equipment architectures in high-frequency bands represents a significant opportunity to embed the technology into 6G standards from the outset. BeammWave successfully introduced digital beamforming to the 3GPP RAN4#119 meeting agenda in Dalian, with the standards body commencing feasibility studies for FR2 device architectures. This evaluation covers cost and power efficiency relative to the initial 5G study phase, as well as system and specification impacts on base station implementations, radio resource management, and network procedures. If digital beamforming is adopted as a standard reference architecture alongside traditional analog beamforming, it would create a defined market for compliant components and accelerate ecosystem development, positioning early movers to capture standardization-driven demand.
Threat:
Incumbent Vendor Lock-In and Proprietary Ecosystem Resistance
The 6G digital beamforming market faces structural resistance from established network equipment vendors whose business models depend on proprietary beamforming implementations embedded in their radio portfolios. Ericsson, Nokia, and Huawei derive substantial revenue from integrated radio systems that bundle beamforming capabilities with hardware, and a shift toward open, standardized digital beamforming architectures threatens these revenue streams. NVIDIA’s push for an open, AI-native 6G stack supported by Deutsche Telekom, T-Mobile, SoftBank, Ericsson, and Nokia represents a direct challenge to closed proprietary models, but industry observers expect a gradual transition rather than abrupt displacement. This incumbency dynamic may slow the diffusion of best-in-class digital beamforming algorithms across multi-vendor environments and limit opportunities for independent component suppliers.
Covid-19 Impact:
The pandemic initially disrupted research collaboration and laboratory access, delaying digital beamforming testbed development and 3GPP standards contributions as universities and research institutes operated under restrictions. Mid-pandemic, accelerated digital transformation and the demonstrated importance of network capacity reinforced long-term investment in advanced antenna technologies. Post-pandemic, digital beamforming research has accelerated with renewed government funding and industry collaboration, embedding the technology as a strategic priority in 6G development agendas despite the extended timeline to commercial deployment.
The hardware segment is expected to be the largest during the forecast period
The hardware segment is expected to account for the largest market share during the forecast period, due to the essential role of antenna arrays, RF front-end modules, and digital signal processors in enabling digital beamforming capabilities. The transition from analog and hybrid architectures to fully digital beamforming requires new antenna designs, per-element RF chains, and high-performance data converters that represent substantial capital investment. Analog Devices introduced the ADSY2301 modular phased-array platform in October 2026, combining analog beamforming, X-band conversion, and RF digitization in a tile architecture built around the ADAR1000 beamformer IC and ADRV9009 transceiver . While software and services grow in importance as systems mature, the physical layer components remain the foundational technology upon which all digital beamforming capabilities depend.
The sub-terahertz and terahertz segment is expected to have the highest CAGR during the forecast period
Over the forecast period, the sub-terahertz and terahertz frequency band segment is predicted to witness the highest growth rate, driven by the unique suitability of digital beamforming for the extreme path loss and massive antenna counts required at these frequencies. Sub-terahertz and terahertz communications demand highly directional beams and precise beam tracking that only fully digital architectures can provide at scale. Research from Lund University demonstrated a 256-antenna distributed MIMO testbed with real-time fully digital beamforming, establishing practical feasibility for the large-scale digital arrays that 6G terahertz systems will require. As 6G research progresses toward higher frequencies to access the bandwidth needed for terabit-per-second links, demand for digital beamforming at sub-terahertz and terahertz bands is accelerating faster than at conventional frequencies.
Region with largest share:
During the forecast period, the North America region is expected to hold the largest market share, due to the concentration of major semiconductor and network infrastructure vendors, advanced operator research programs, and government investment in 6G technology. NVIDIA’s development of dedicated GPUs for 6G radio units and its $2 billion investment in Marvell, a key supplier of radio unit semiconductors, demonstrate the region’s leadership in digital beamforming silicon. Analog Devices’ ADSY2301 phased-array platform and Keysight’s collaboration with Qualcomm on RF digital twins for massive MIMO further reinforce the region’s dominant position. U.S. operators and vendors are actively engaged in 3GPP standardization and pre-commercial validation, supporting the region’s leading share.
Region with highest CAGR:
Over the forecast period, the Asia Pacific region is anticipated to exhibit the highest CAGR, due to substantial government-led 6G research programs and the concentration of antenna and RF component manufacturing across China, Japan, South Korea, and India. BeammWave introduced digital beamforming to the 3GPP RAN4 agenda in Dalian, China, signaling the region’s active engagement in standards development. China’s major operators and equipment vendors are investing in massive MIMO and digital beamforming research as part of national 6G programs, while Japan’s and South Korea’s advanced semiconductor capabilities support component development. The region’s manufacturing scale and government funding position it for rapid growth as 6G standards mature and commercial deployment approaches.
Key players in the market
Some of the key players in 6G Digital Beamforming Market include NVIDIA Corporation, Analog Devices, Inc., NEC Corporation, Qorvo, Inc., Samsung Electronics Co., Ltd., InterDigital, Inc., Nokia Corporation, Juniper Networks, Huawei Technologies Co., Ltd., Anritsu Corporation, Ciena Corporation, Keysight Technologies, Inc., Ericsson, NXP Semiconductors N.V., Cisco Systems, Inc., Qualcomm Incorporated, Rohde & Schwarz GmbH & Co. KG, and VIAVI Solutions Inc.
Key Developments:
In Oct 2026, Nokia Corporation and NVIDIA Corporation expanded their AI-RAN collaboration to integrate AI-based channel estimation, beamforming, multi-user MIMO pairing and scheduling into radio processing. The initiative combines Nokia's anyRAN software with NVIDIA's Aerial RAN Computer to improve spectral efficiency and support future AI-native 6G networks.
In Oct 2026, Ericsson partnered with KTH Royal Institute of Technology and Nanyang Technological University, Singapore, to research AI-enabled positioning for future 6G networks. The initiative combines automated antenna calibration, machine learning and advanced wireless localization to improve positioning reliability in complex indoor and outdoor environments.
In Sep 2026, Samsung Electronics Co., Ltd. signed agreements with KT and SK Telecom to develop AI-powered radio access network capabilities under South Korea's Hyper AI Network initiative. The projects involve private 5G Standalone deployments to validate intelligent radio processing and establish foundations for future 6G network architectures.
In Sep 2026, NVIDIA Corporation, Keysight Technologies, Inc., Rohde & Schwarz GmbH & Co. KG, Cisco Systems, Inc., and VIAVI Solutions Inc. joined Verizon's expanded 6G Innovation Forum. The collaboration aims to advance AI-native wireless networks, integrated sensing, next-generation radio architectures and testing technologies supporting future 6G deployments.
Components Covered:
• Software
• Services
Beamforming Architectures Covered:
• Fully Digital Beamforming
• Hybrid Beamforming
• Distributed Beamforming
Antenna Configurations Covered:
• Massive MIMO
• Ultra-Massive MIMO
• Cell-Free MIMO
Frequency Bands Covered:
• Mid-Band
• Millimeter Wave
• Sub-Terahertz and Terahertz
Technologies Covered:
• AI-Assisted Beamforming
• Adaptive Beam Steering
• Multi-User Beamforming
Applications Covered:
• High-Capacity Wireless Access
• Integrated Sensing
• Backhaul Communications
• Indoor Connectivity
• Other Applications
End Users Covered:
• Telecom Equipment Manufacturers
• Semiconductor Vendors
• Telecom Operators
• Research Institutions
• Other End Users
Regions Covered:
• North America
o United States
o Canada
o Mexico
• Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Netherlands
o Belgium
o Sweden
o Switzerland
o Poland
o Rest of Europe
• Asia Pacific
o China
o Japan
o India
o South Korea
o Australia
o Indonesia
o Thailand
o Malaysia
o Singapore
o Vietnam
o Rest of Asia Pacific
• South America
o Brazil
o Argentina
o Colombia
o Chile
o Peru
o Rest of South America
• Rest of the World (RoW)
o Middle East
§ Saudi Arabia
§ United Arab Emirates
§ Qatar
§ Israel
§ Rest of Middle East
o Africa
§ South Africa
§ Egypt
§ Morocco
§ Rest of Africa
What our report offers:
- Market share assessments for the regional and country-level segments
- Strategic recommendations for the new entrants
- Covers Market data for the years 2023, 2024, 2025, 2026, 2027, 2028, 2030, 2032 and 2034
- Market Trends (Drivers, Constraints, Opportunities, Threats, Challenges, Investment Opportunities, and recommendations)
- Strategic recommendations in key business segments based on the market estimations
- Competitive landscaping mapping the key common trends
- Company profiling with detailed strategies, financials, and recent developments
- Supply chain trends mapping the latest technological advancements
Free Customization Offerings:
All the customers of this report will be entitled to receive one of the following free customization options:
• Company Profiling
o Comprehensive profiling of additional market players (up to 3)
o SWOT Analysis of key players (up to 3)
• Regional Segmentation
o Market estimations, Forecasts and CAGR of any prominent country as per the client's interest (Note: Depends on feasibility check)
• Competitive Benchmarking
o Benchmarking of key players based on product portfolio, geographical presence, and strategic alliances
Table of Contents
1 Executive Summary1.1 Market Snapshot and Key Highlights
1.2 Growth Drivers, Challenges, and Opportunities
1.3 Competitive Landscape Overview
1.4 Strategic Insights and Recommendations
2 Research Framework
2.1 Study Objectives and Scope
2.2 Stakeholder Analysis
2.3 Research Assumptions and Limitations
2.4 Research Methodology
2.4.1 Data Collection (Primary and Secondary)
2.4.2 Data Modeling and Estimation Techniques
2.4.3 Data Validation and Triangulation
2.4.4 Analytical and Forecasting Approach
3 Market Dynamics and Trend Analysis
3.1 Market Definition and Structure
3.2 Key Market Drivers
3.3 Market Restraints and Challenges
3.4 Growth Opportunities and Investment Hotspots
3.5 Industry Threats and Risk Assessment
3.6 Technology and Innovation Landscape
3.7 Emerging and High-Growth Markets
3.8 Regulatory and Policy Environment
3.9 Impact of COVID-19 and Recovery Outlook
4 Competitive and Strategic Assessment
4.1 Porter's Five Forces Analysis
4.1.1 Supplier Bargaining Power
4.1.2 Buyer Bargaining Power
4.1.3 Threat of Substitutes
4.1.4 Threat of New Entrants
4.1.5 Competitive Rivalry
4.2 Market Share Analysis of Key Players
4.3 Product Benchmarking and Performance Comparison
5 Global 6G Digital Beamforming Market, By Component
5.1 Hardware
5.1.1 Antenna Arrays
5.1.2 RF Front-End Modules
5.1.3 Digital Signal Processors
5.2 Software
5.2.1 Beamforming Algorithms
5.2.2 Beam Management Software
5.3 Services
5.3.1 Design and Integration
5.3.2 Testing Services
6 Global 6G Digital Beamforming Market, By Beamforming Architecture
6.1 Fully Digital Beamforming
6.2 Hybrid Beamforming
6.3 Distributed Beamforming
7 Global 6G Digital Beamforming Market, By Antenna Configuration
7.1 Massive MIMO
7.2 Ultra-Massive MIMO
7.3 Cell-Free MIMO
8 Global 6G Digital Beamforming Market, By Frequency Band
8.1 Mid-Band
8.2 Millimeter Wave
8.3 Sub-Terahertz and Terahertz
9 Global 6G Digital Beamforming Market, By Technology
9.1 AI-Assisted Beamforming
9.2 Adaptive Beam Steering
9.3 Multi-User Beamforming
10 Global 6G Digital Beamforming Market, By Application
10.1 High-Capacity Wireless Access
10.2 Integrated Sensing
10.3 Backhaul Communications
10.4 Indoor Connectivity
10.5 Other Applications
11 Global 6G Digital Beamforming Market, By End User
11.1 Telecom Equipment Manufacturers
11.2 Semiconductor Vendors
11.3 Telecom Operators
11.4 Research Institutions
11.5 Other End Users
12 Global 6G Digital Beamforming Market, By Geography
12.1 North America
12.1.1 United States
12.1.2 Canada
12.1.3 Mexico
12.2 Europe
12.2.1 United Kingdom
12.2.2 Germany
12.2.3 France
12.2.4 Italy
12.2.5 Spain
12.2.6 Netherlands
12.2.7 Belgium
12.2.8 Sweden
12.2.9 Switzerland
12.2.10 Poland
12.2.11 Rest of Europe
12.3 Asia Pacific
12.3.1 China
12.3.2 Japan
12.3.3 India
12.3.4 South Korea
12.3.5 Australia
12.3.6 Indonesia
12.3.7 Thailand
12.3.8 Malaysia
12.3.9 Singapore
12.3.10 Vietnam
12.3.11 Rest of Asia Pacific
12.4 South America
12.4.1 Brazil
12.4.2 Argentina
12.4.3 Colombia
12.4.4 Chile
12.4.5 Peru
12.4.6 Rest of South America
12.5 Rest of the World (RoW)
12.5.1 Middle East
12.5.1.1 Saudi Arabia
12.5.1.2 United Arab Emirates
12.5.1.3 Qatar
12.5.1.4 Israel
12.5.1.5 Rest of Middle East
12.5.2 Africa
12.5.2.1 South Africa
12.5.2.2 Egypt
12.5.2.3 Morocco
12.5.2.4 Rest of Africa
13 Strategic Market Intelligence
13.1 Industry Value Network and Supply Chain Assessment
13.2 White-Space and Opportunity Mapping
13.3 Product Evolution and Market Life Cycle Analysis
13.4 Channel, Distributor, and Go-to-Market Assessment
14 Industry Developments and Strategic Initiatives
14.1 Mergers and Acquisitions
14.2 Partnerships, Alliances, and Joint Ventures
14.3 New Product Launches and Certifications
14.4 Capacity Expansion and Investments
14.5 Other Strategic Initiatives
15 Company Profiles
15.1 NVIDIA Corporation
15.2 Analog Devices, Inc.
15.3 NEC Corporation
15.4 Qorvo, Inc.
15.5 Samsung Electronics Co., Ltd.
15.6 InterDigital, Inc.
15.7 Nokia Corporation
15.8 Juniper Networks
15.9 Huawei Technologies Co., Ltd.
15.10 Anritsu Corporation
15.11 Ciena Corporation
15.12 Keysight Technologies, Inc.
15.13 Ericsson
15.14 NXP Semiconductors N.V.
15.15 Cisco Systems, Inc.
15.16 Qualcomm Incorporated
15.17 Rohde & Schwarz GmbH & Co. KG
15.18 VIAVI Solutions Inc.
List of Tables
1 Global 6G Digital Beamforming Market Outlook, By Region (2023-2034) ($MN)
2 Global 6G Digital Beamforming Market Outlook, By Component (2023-2034) ($MN)
3 Global 6G Digital Beamforming Market Outlook, By Hardware (2023-2034) ($MN)
4 Global 6G Digital Beamforming Market Outlook, By Antenna Arrays (2023-2034) ($MN)
5 Global 6G Digital Beamforming Market Outlook, By RF Front-End Modules (2023-2034) ($MN)
6 Global 6G Digital Beamforming Market Outlook, By Digital Signal Processors (2023-2034) ($MN)
7 Global 6G Digital Beamforming Market Outlook, By Software (2023-2034) ($MN)
8 Global 6G Digital Beamforming Market Outlook, By Beamforming Algorithms (2023-2034) ($MN)
9 Global 6G Digital Beamforming Market Outlook, By Beam Management Software (2023-2034) ($MN)
10 Global 6G Digital Beamforming Market Outlook, By Services (2023-2034) ($MN)
11 Global 6G Digital Beamforming Market Outlook, By Design and Integration (2023-2034) ($MN)
12 Global 6G Digital Beamforming Market Outlook, By Testing Services (2023-2034) ($MN)
13 Global 6G Digital Beamforming Market Outlook, By Beamforming Architecture (2023-2034) ($MN)
14 Global 6G Digital Beamforming Market Outlook, By Fully Digital Beamforming (2023-2034) ($MN)
15 Global 6G Digital Beamforming Market Outlook, By Hybrid Beamforming (2023-2034) ($MN)
16 Global 6G Digital Beamforming Market Outlook, By Distributed Beamforming (2023-2034) ($MN)
17 Global 6G Digital Beamforming Market Outlook, By Antenna Configuration (2023-2034) ($MN)
18 Global 6G Digital Beamforming Market Outlook, By Massive MIMO (2023-2034) ($MN)
19 Global 6G Digital Beamforming Market Outlook, By Ultra-Massive MIMO (2023-2034) ($MN)
20 Global 6G Digital Beamforming Market Outlook, By Cell-Free MIMO (2023-2034) ($MN)
21 Global 6G Digital Beamforming Market Outlook, By Frequency Band (2023-2034) ($MN)
22 Global 6G Digital Beamforming Market Outlook, By Mid-Band (2023-2034) ($MN)
23 Global 6G Digital Beamforming Market Outlook, By Millimeter Wave (2023-2034) ($MN)
24 Global 6G Digital Beamforming Market Outlook, By Sub-Terahertz and Terahertz (2023-2034) ($MN)
25 Global 6G Digital Beamforming Market Outlook, By Technology (2023-2034) ($MN)
26 Global 6G Digital Beamforming Market Outlook, By AI-Assisted Beamforming (2023-2034) ($MN)
27 Global 6G Digital Beamforming Market Outlook, By Adaptive Beam Steering (2023-2034) ($MN)
28 Global 6G Digital Beamforming Market Outlook, By Multi-User Beamforming (2023-2034) ($MN)
29 Global 6G Digital Beamforming Market Outlook, By Application (2023-2034) ($MN)
30 Global 6G Digital Beamforming Market Outlook, By High-Capacity Wireless Access (2023-2034) ($MN)
31 Global 6G Digital Beamforming Market Outlook, By Integrated Sensing (2023-2034) ($MN)
32 Global 6G Digital Beamforming Market Outlook, By Backhaul Communications (2023-2034) ($MN)
33 Global 6G Digital Beamforming Market Outlook, By Indoor Connectivity (2023-2034) ($MN)
34 Global 6G Digital Beamforming Market Outlook, By Other Applications (2023-2034) ($MN)
35 Global 6G Digital Beamforming Market Outlook, By End User (2023-2034) ($MN)
36 Global 6G Digital Beamforming Market Outlook, By Telecom Equipment Manufacturers (2023-2034) ($MN)
37 Global 6G Digital Beamforming Market Outlook, By Semiconductor Vendors (2023-2034) ($MN)
38 Global 6G Digital Beamforming Market Outlook, By Telecom Operators (2023-2034) ($MN)
39 Global 6G Digital Beamforming Market Outlook, By Research Institutions (2023-2034) ($MN)
40 Global 6G Digital Beamforming Market Outlook, By Other End Users (2023-2034) ($MN)
Note: Tables for North America, Europe, APAC, South America, and Rest of the World (RoW) Regions are also represented in the same manner as above
List of Figures
RESEARCH METHODOLOGY
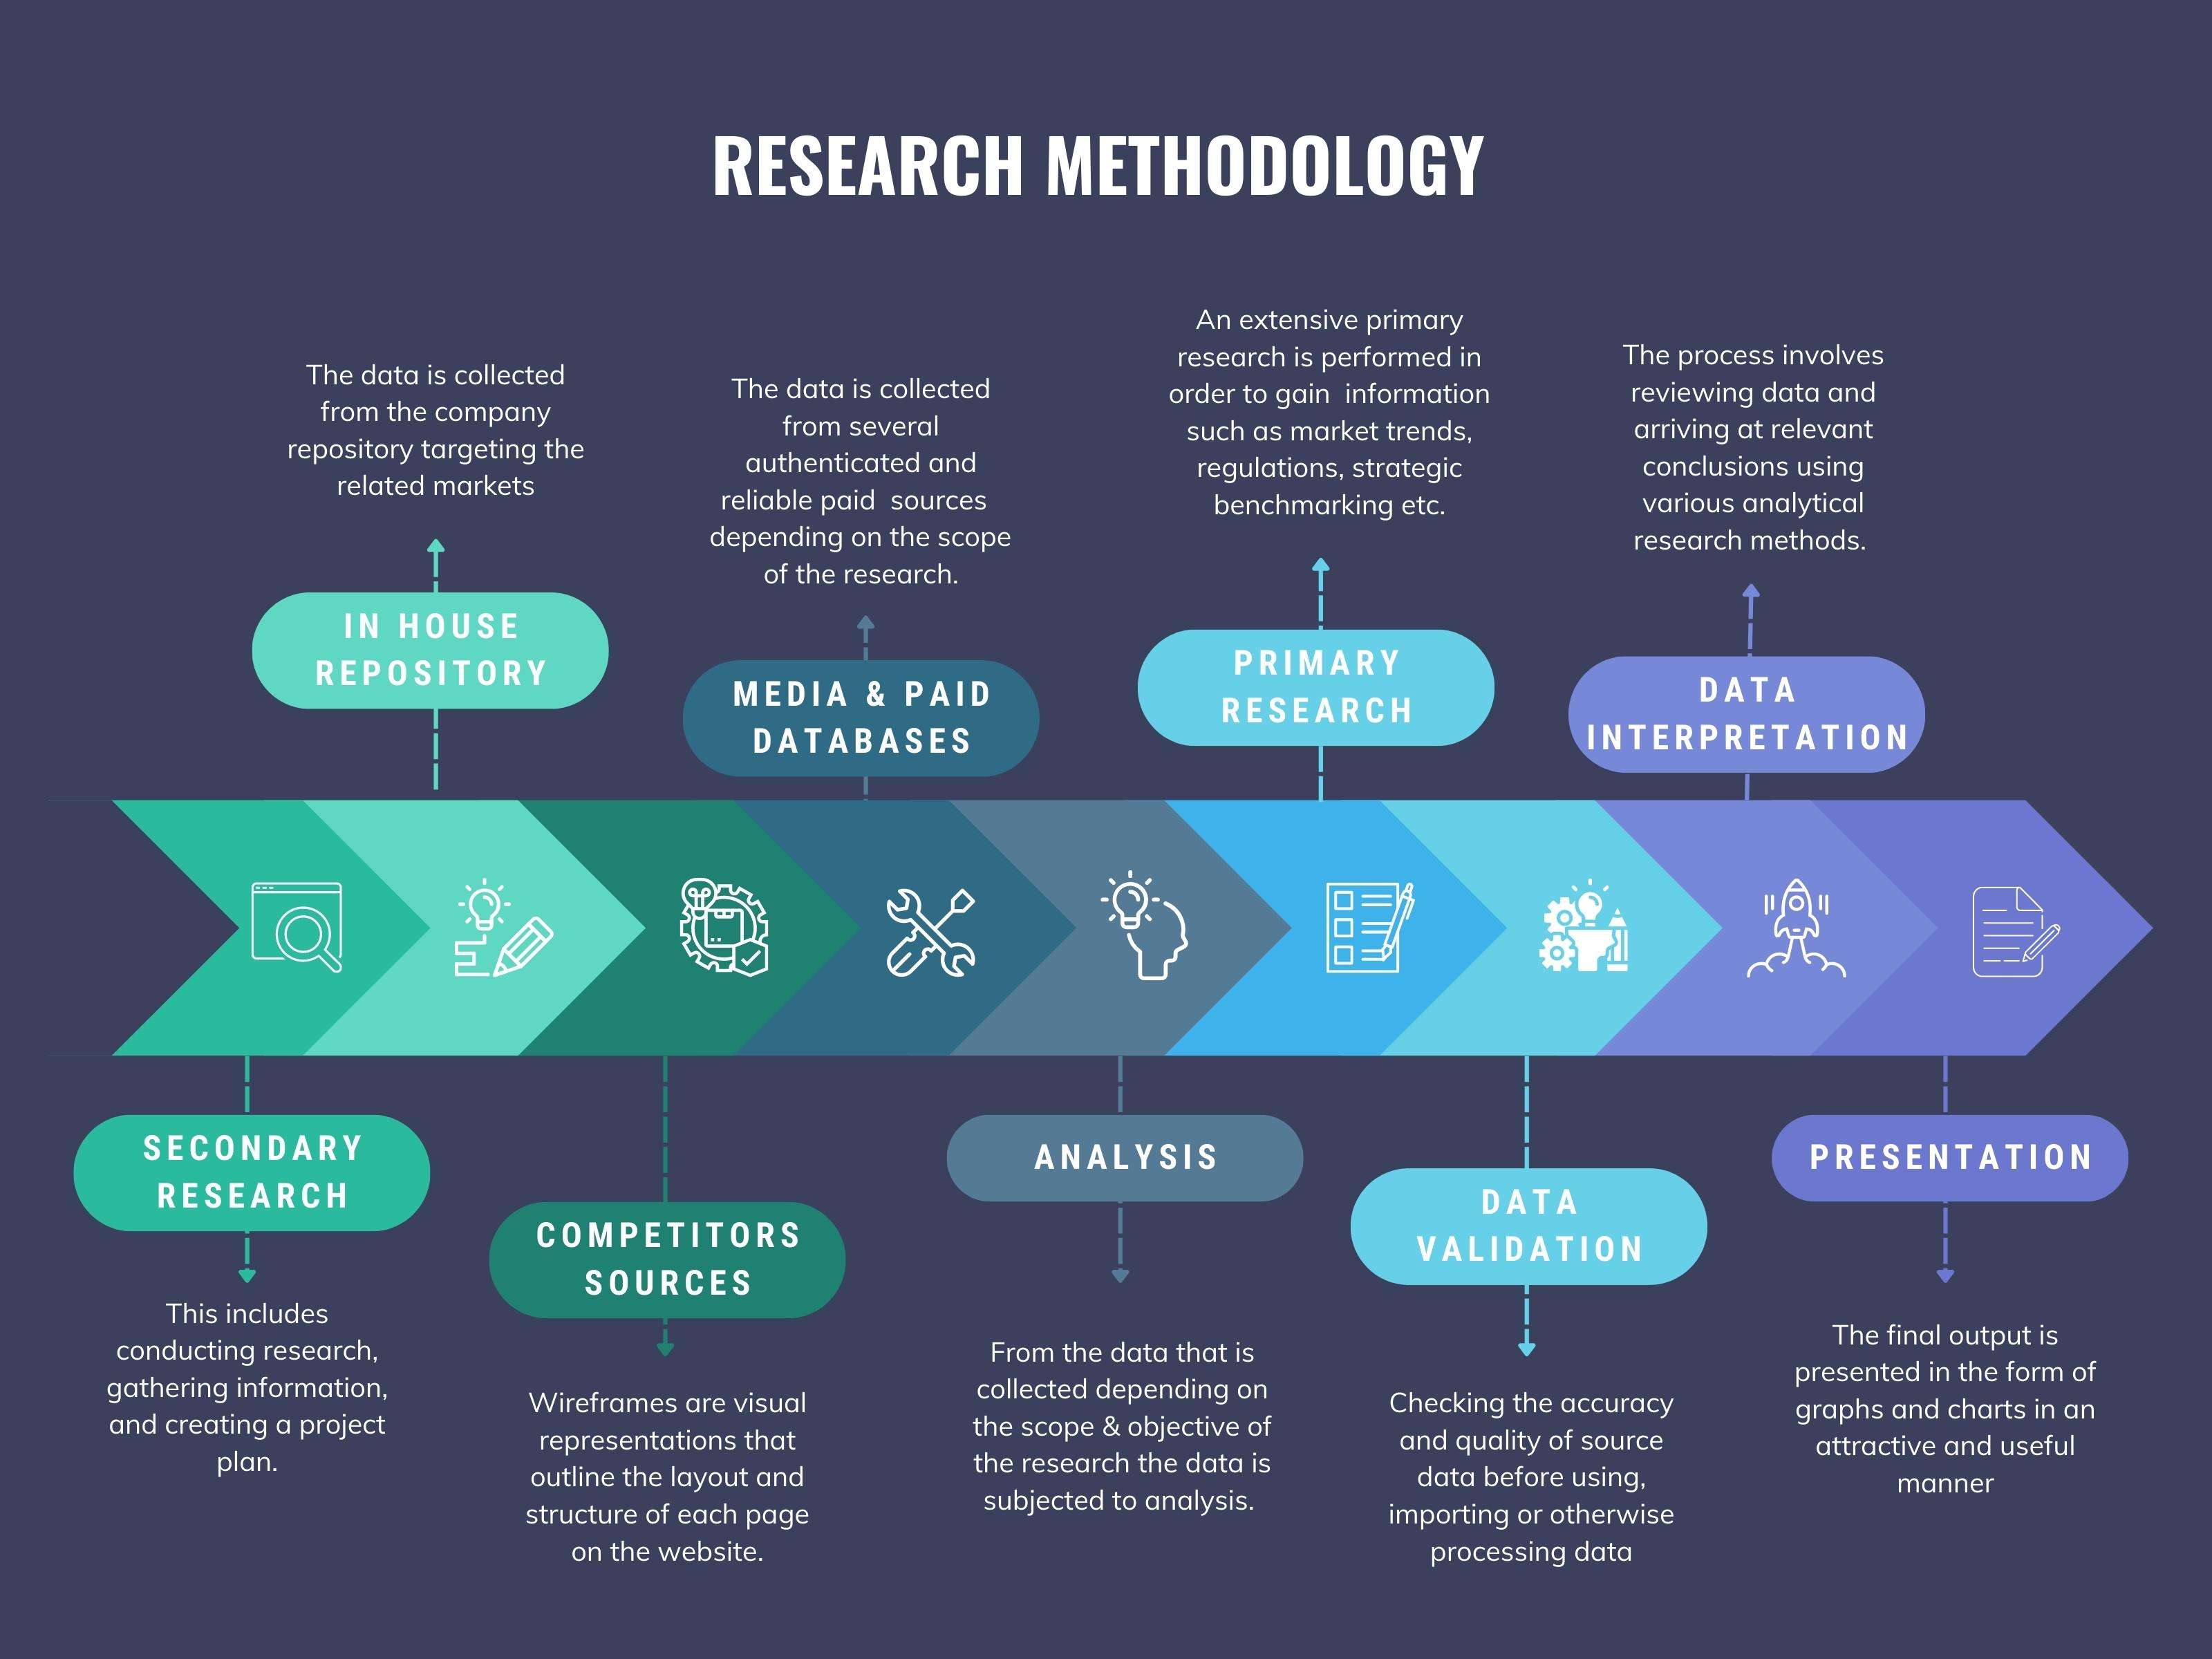
We at ‘Stratistics’ opt for an extensive research approach which involves data mining, data validation, and data analysis. The various research sources include in-house repository, secondary research, competitor’s sources, social media research, client internal data, and primary research.
Our team of analysts prefers the most reliable and authenticated data sources in order to perform the comprehensive literature search. With access to most of the authenticated data bases our team highly considers the best mix of information through various sources to obtain extensive and accurate analysis.
Each report takes an average time of a month and a team of 4 industry analysts. The time may vary depending on the scope and data availability of the desired market report. The various parameters used in the market assessment are standardized in order to enhance the data accuracy.
Data Mining
The data is collected from several authenticated, reliable, paid and unpaid sources and is filtered depending on the scope & objective of the research. Our reports repository acts as an added advantage in this procedure. Data gathering from the raw material suppliers, distributors and the manufacturers is performed on a regular basis, this helps in the comprehensive understanding of the products value chain. Apart from the above mentioned sources the data is also collected from the industry consultants to ensure the objective of the study is in the right direction.
Market trends such as technological advancements, regulatory affairs, market dynamics (Drivers, Restraints, Opportunities and Challenges) are obtained from scientific journals, market related national & international associations and organizations.
Data Analysis
From the data that is collected depending on the scope & objective of the research the data is subjected for the analysis. The critical steps that we follow for the data analysis include:
- Product Lifecycle Analysis
- Competitor analysis
- Risk analysis
- Porters Analysis
- PESTEL Analysis
- SWOT Analysis
The data engineering is performed by the core industry experts considering both the Marketing Mix Modeling and the Demand Forecasting. The marketing mix modeling makes use of multiple-regression techniques to predict the optimal mix of marketing variables. Regression factor is based on a number of variables and how they relate to an outcome such as sales or profits.
Data Validation
The data validation is performed by the exhaustive primary research from the expert interviews. This includes telephonic interviews, focus groups, face to face interviews, and questionnaires to validate our research from all aspects. The industry experts we approach come from the leading firms, involved in the supply chain ranging from the suppliers, distributors to the manufacturers and consumers so as to ensure an unbiased analysis.
We are in touch with more than 15,000 industry experts with the right mix of consultants, CEO's, presidents, vice presidents, managers, experts from both supply side and demand side, executives and so on.
The data validation involves the primary research from the industry experts belonging to:
- Leading Companies
- Suppliers & Distributors
- Manufacturers
- Consumers
- Industry/Strategic Consultants
Apart from the data validation the primary research also helps in performing the fill gap research, i.e. providing solutions for the unmet needs of the research which helps in enhancing the reports quality.
For more details about research methodology, kindly write to us at info@strategymrc.com
Frequently Asked Questions
In case of any queries regarding this report, you can contact the customer service by filing the “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
Yes, the samples are available for all the published reports. You can request them by filling the “Request Sample” option available in this page.
Yes, you can request a sample with your specific requirements. All the customized samples will be provided as per the requirement with the real data masked.
All our reports are available in Digital PDF format. In case if you require them in any other formats, such as PPT, Excel etc you can submit a request through “Inquiry Before Buy” form available on the right hand side. You may also contact us through email: info@strategymrc.com or phone: +1-301-202-5929
We offer a free 15% customization with every purchase. This requirement can be fulfilled for both pre and post sale. You may send your customization requirements through email at info@strategymrc.com or call us on +1-301-202-5929.
We have 3 different licensing options available in electronic format.
- Single User Licence: Allows one person, typically the buyer, to have access to the ordered product. The ordered product cannot be distributed to anyone else.
- 2-5 User Licence: Allows the ordered product to be shared among a maximum of 5 people within your organisation.
- Corporate License: Allows the product to be shared among all employees of your organisation regardless of their geographical location.
All our reports are typically be emailed to you as an attachment.
To order any available report you need to register on our website. The payment can be made either through CCAvenue or PayPal payments gateways which accept all international cards.
We extend our support to 6 months post sale. A post sale customization is also provided to cover your unmet needs in the report.
Request Customization
We offer complimentary customization of up to 15% with every purchase. To share your customization requirements, feel free to email us at info@strategymrc.com or call us on +1-301-202-5929. .
Please Note: Customization within the 15% threshold is entirely free of charge. If your request exceeds this limit, we will conduct a feasibility assessment. Following that, a detailed quote and timeline will be provided.
WHY CHOOSE US ?

Assured Quality
Best in class reports with high standard of research integrity

24X7 Research Support
Continuous support to ensure the best customer experience.

Free Customization
Adding more values to your product of interest.

Safe & Secure Access
Providing a secured environment for all online transactions.

Trusted by 600+ Brands
Serving the most reputed brands across the world.